@ReynStorms@alojohhardcore I also work for a well known telecom vendor. The level of improvement in development both in Hw and Sw due to AI is very well noticed to everyone. Despite the positive financial results the "restructuring plans" (aka headcount reduction) are chilling. Just like Meta,MSFT,GOOGL...
@ChristianSimpk3@alojohhardcore I would expect xpeng to present something interesting during this event. Perhaps it is worth waiting until then with the hope that the xpev price will allow a better exchange...
https://t.co/9tXkFeKOi4
XPENG AI Day is coming on November 25.
The next frontier of AI isn't just about making models smarter. It's about making intelligence work in the physical world.
Why is Physical AI fundamentally different? Why can't a more powerful model alone solve it?
On November 25, we'll share our latest thinking, explore the co-evolution of AI models and physical systems, showcase the latest capabilities of IRON humanoid robot, and unveil how physical AI will reshape the future mobility experience.
See you there!
@alojohhardcore@Merlin__8 Then for investments we are in the best hands.
I will try to stay calm until I hear from you:
"Sell everything, turn your money into canned beans, and move somewhere with goats."
😁
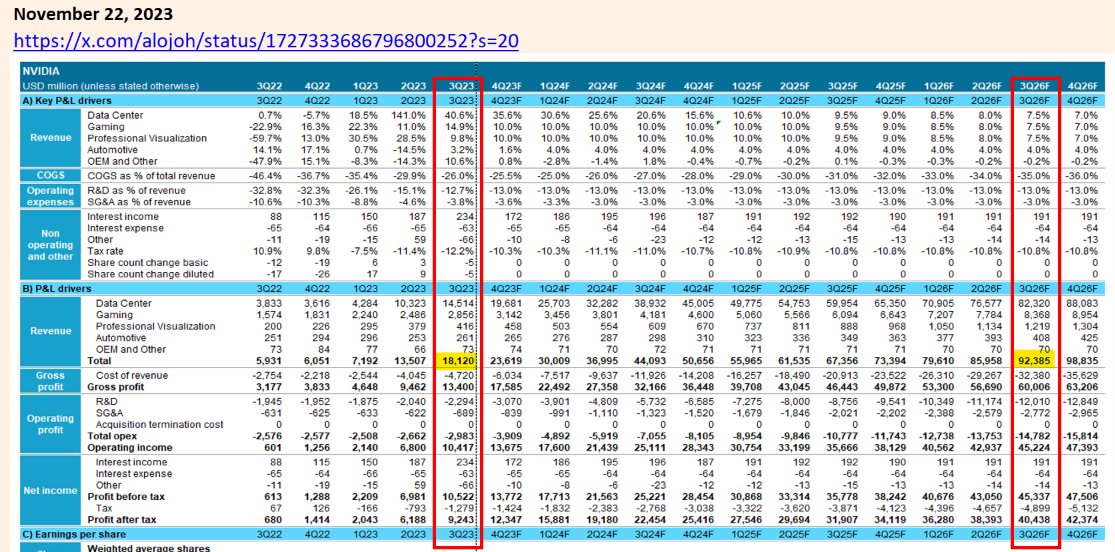
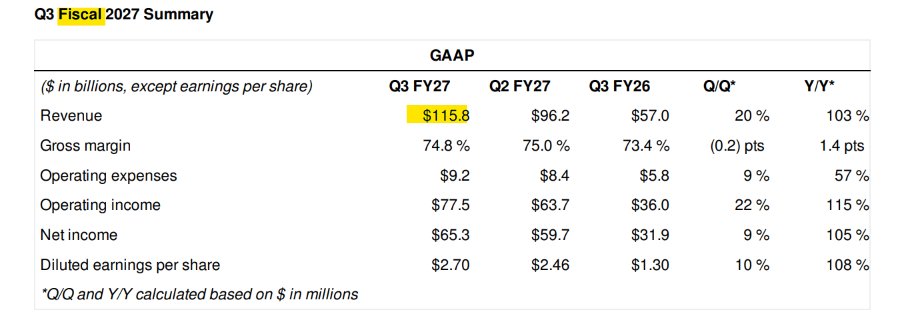
3 years ago, we forecast Nvidia would report today $92.3 billion in revenue (when Nvidia just had reported $18.1 billion. Everyone thought we were crazy. I still remember the conversations with investors at the time. Today Nvidia reported $115.8 billion. Consensus at the time was off by well over 50%.
(Note: our quarter labelling reflects the closest calendar quarter, not Nvidia's nomenclature: eg Nvidia's Q3 2026 (ending October 2026) is Nvidia's fiscal Q3 2027. We apply this convention in all our research to facilitate readability of financial statements).
@NyMoneyHawk@alojohhardcore@degenlurker_@TuttiInvesting@myfyAI@FoxNews Considering Elon/X/SpaceX one of the hyperscalers I can imagine he will tweak the X algorithm to slow down the flow of negative news and boost the positive ones before any real damage gets done/affects him. The same for the PR departments of the other hyperscalers.
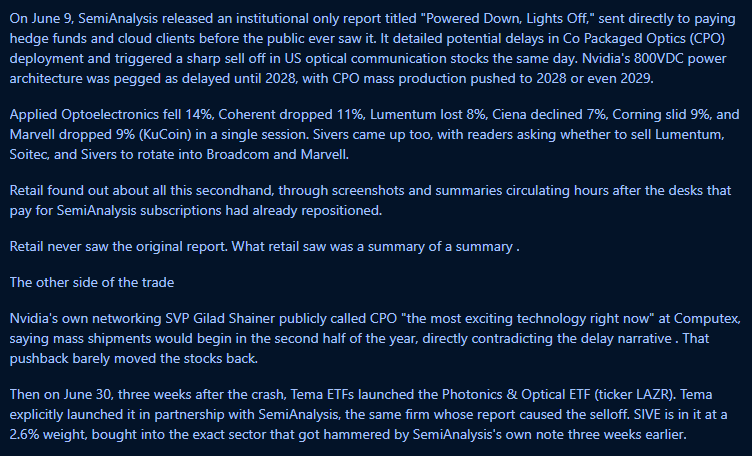
@SemiAnalysis_, a timeline:
June 9: SA sends clients a bearish report on co-packaged optics. Photonics gets destroyed. $AAOI down 17% in a day, $LITE down 8%. Nvidia disputes the report.
June 30: The LAZR photonics ETF launches "in partnership with SemiAnalysis." It holds names that sold off on their report.
ETFs don't get built in three weeks. So when SA published the report that tanked the sector, was a photonics fund with their name on it already in the works?
Sept 11: SA buys Citrini.
Nov 13: SA cuts its 2028 AI infrastructure capex forecast from $2.64T to $1.90T. $740B gone in one update. Chip stocks plunge.
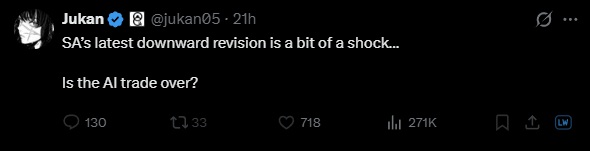
Then: @jukan05, now on SA's payroll, posts "Is the AI trade over?" to 271K views. Known for selling the bottom on memory and spreading more FUD right afterwards.
Multiple times this year the same firm has moved a sector with a report and then had a commercial interest sitting on the other side of that move.
And the forecast itself: either $2.64T was never real, or $1.90T isn't. They sold both with the same confidence.
Now the question here is, a 30% revision is quite rough, so when did you lie to us. Before, or now? Cause either way your model seems to be shit.
Maybe it's all coincidence. But a research shop that moves markets, co-brands ETFs in the sectors it moves, and owns the accounts that amplify the move is not independent research. It's a conflict of interest with a newsletter.
@SemiAnalysis_ needs to be boycott. These people are sensationalists disguised as professional analysts.
@alojohhardcore@ausinvestornew I have terrible memory, but your post before the downturn saying that you were felling uncomfortable after several weeks of all time high after ATH, and that you were reducing leverage/starting to get cash is something I am not forgetting. Next time I will follow on that signal.
@alojohhardcore@robertpuklin I wouldn't discard as motivation the removal of an important open source AI supporter, endangering important interests in frontier business in the proximity of Anthropic and OpenAI IPO's.
Turmoil in the sector until these get settled?
🤔
At over 300 votes this is already a statistically significant result and the result is clear: the overwhelming majority wants Jensen to stay. I don't think 10 board members should decide over @JensenHuang 's fate. Let's not dispose of our best business leaders so easily.
@alojohhardcore@MattsterT3 You never stop amazing me. Every single day. Your company insights, analogies drawn from deep experience, eye for detail, work capacity, ability to outperform Wall Street estimates consistently, and the ever-growing toolkit.
Thank you AJ! 🙌
Obama’s CIA coup in Kiev in 2014 toppled Viktor Yanukovych. Poroshenko's regime (2014-2019) began attacking Donbas, the ethnic Russian region historically close to Russia. After 2014, #Ukraine turned against Russia, the Orthodox faith, and the shared history of the two peoples.
@alojohhardcore@AndersMcKrensh I am eagerly awaiting Xpeng quarterly results. I imagine the soaring oil prices and overall uncertainty should be a nice tailwind
@alojohhardcore We are below the price you entered yesterday RIVN ($14.01 vs 14.02)...any interest in reentering the rinse at repeat, or the market conditions suggest to wait?
Here is how Cathie tries to gaslight everyone in this video and provides us with a useful case to analyse how it works.
Her defense of ARKK is a great example of how you can make an awful long term record sound great by carefully choosing the denominator ("end point, as she calls it"), comparison group and time periods.
Her claim is that ARKK ranks in the "top 5% to 10% of the Morningstar database within its category over 1 year, 3 years, 10 years and since inception".
She then argues that comparing ARKK with QQQ is "incorrect" because ARK invests in technologically enabled innovation across all sectors.
It sounds compelling until you actually look at the numbers.
1. Watch the qualifiers. They are doing almost all the work.
Cathie is not saying ARKK ranks in the top 5% to 10% of investment alternatives available to investors.
She says it ranks there within its Morningstar category.
That is a very different statement.
Morningstar is one of the world's largest and most established investment research and data providers. Its fund database, classifications and ratings are widely used by investors, financial advisers and institutions.
The issue is that being highly ranked within a peer group tells you nothing about whether investors would have been better off simply buying an obvious passive alternative.
For example, I am a grown man. Put me in the diaper league of soccer and I would probably rank in the top 5% to 10%. Sounds impressive, provided you don't know what the diaper league is. Now expand the peer group to all soccer players, including the Premier League, and suddenly my “top 5% to 10%” ranking disappears rather quickly. That is the point: a percentile ranking is only as impressive as the peer group you are being ranked against.
If you are the best runner in a slow race, you are still running slowly.
Investors do not spend Morningstar percentile rankings. They spend money.
And then there is the wording:
"Top 5% to 10%". Interesting.
If you are comfortably in the top 5%, you normally say:
"Top 5%".
You do not say "top 5% to 10%."
That wording creates the psychological impression of "top 5%" without actually saying it. Convenient.
2. Even more conveniently, Cathie skipped five years.
Cathie specifically highlighted:
1 year. 3 years. 10 years. Since inception.
Notice anything missing?
Five years.
And five years happens to be an absolute horror show for ARKK.
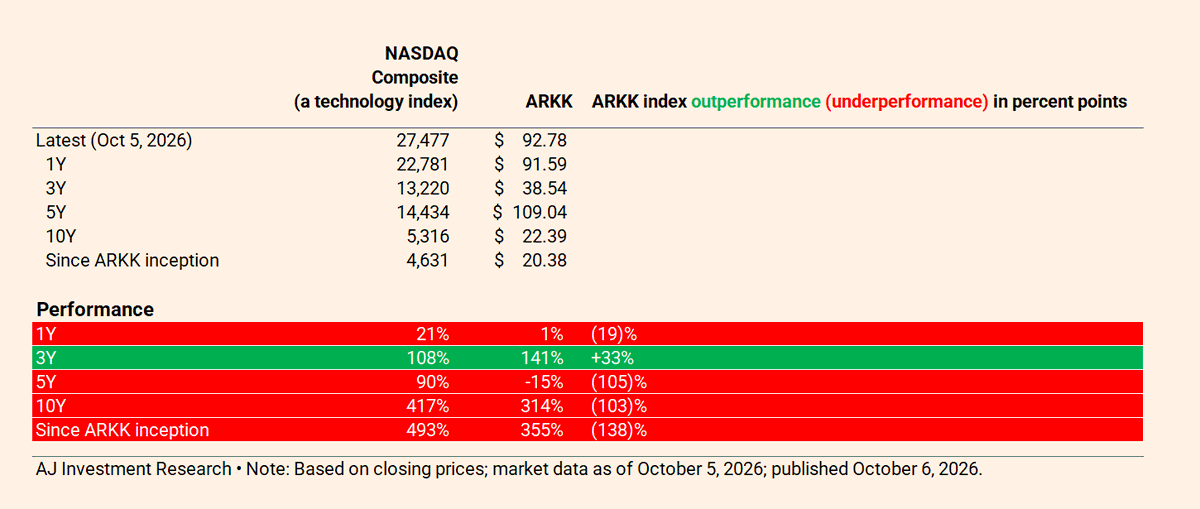
Over the last five years, the NASDAQ gained approximately 90%. ARKK lost approximately 15%.
That is 105 percentage points of underperformance.
Read that again. The technology index gained 90%.
Cathie Wood's innovation fund lost money.
And somehow five years was the period that did not make it into her performance defense.
What a coincidence. (She obviously prepared for this)
3. Even using Cathie’s own selected periods, the record is terrible versus the NASDAQ.
Look at our attached table. Over one year, ARKK trails the NASDAQ by approximately 19 percentage points.
Over ten years, it trails by approximately 103 percentage points. Since inception, it trails by approximately 138 percentage points. ARKK wins over the last three years by 33 percentage points.
And we will happily give Cathie that win.
We have no interest in doing the same cherry picking we are criticizing her for. ARKK has materially outperformed over the last three years. Good.
But one winning window does not erase the rest of the record. Since ARKK's inception, the NASDAQ is up approximately 493%. ARKK is up approximately 355%.
That is 138 percentage points of underperformance over the life of the fund.
4. Cathie got an exceptional starting point.
This part is particularly important when she advertises ARKK's "since inception" return. ARKK launched in 2014. That was an exceptional time to start the clock for an "innovation fund".
We do not even need some complicated macroeconomic study to demonstrate this.
Just look at the NASDAQ. It is up nearly 500% since ARKK's inception!!! This was an incredible bull run for technology/innovation. That is f**king enormous (excuse my French but this is epic).
Cathie launched an innovation fund immediately before one of the greatest periods for technology and growth investing in history.
Software exploded. Cloud exploded. Semiconductors exploded. Digital advertising exploded. Electric vehicles exploded. AI exploded.
The largest technology businesses became THE largest and most profitable companies the world has ever seen.
If you wanted to launch a fund whose entire marketing proposition was based around technological innovation, you could hardly have asked for a better decade.
And yet, ARKK still underperformed the NASDAQ by roughly 138 percentage points.
Think about how absurd that makes the "since inception" victory lap. 🤦♂️
A +355% return sounds fantastic if you present it without context.
It sounds substantially less fantastic when the obvious technology index sitting next to it returned approximately 493%. Cathie had the theme, she had the sector, she had the timing, she had an incredible bull market behind her, AND STILL lost investors money relative to the tech index which the key hurdle for every tech equity investor.
5. Calling the NASDAQ or QQQ comparison "incorrect" is nonsense.
Nobody claims ARKK and QQQ are identical portfolios.
Of course they are not. ARKK invests across multiple conventional sectors, owns smaller and less mature businesses, and runs a concentrated actively managed portfolio. QQQ tracks the Nasdaq 100. Our comparison uses the broader Nasdaq Composite. Fine.
But Cathie takes:
"These portfolios are different." And magically turns it into: "Therefore you cannot compare their investment outcomes." is bulls**t.
An investor interested in technology, innovation, secular growth and businesses benefiting from technological disruption had an obvious alternative:
Buy freaking the NASDAQ, buy QQQ, and pay close to nothing relative to ARKK. And, do nothing. That is the opportunity cost.
The investor's question is not merely:
"How did ARKK perform relative to a collection of other actively managed funds Morningstar put in the same category?"
The relevant question is:
"What did I get for taking all of this additional risk instead of owning the obvious passive alternative?"
If Cathie thinks the NASDAQ is the wrong benchmark, fine. Give us the right benchmark.Pick a transparent, investable benchmark and compare ARKK against it consistently over all relevant periods.
But you cannot dismiss an uncomfortable benchmark as "incorrect" and then hide behind whichever peer group produces the prettiest percentile ranking.
That is not performance analysis. That is benchmark shopping.
6. The additional risk makes ARKK’s record worse, not better.
ARKK is not a boring diversified index. It is an actively managed, concentrated portfolio of highly volatile growth companies. Investors therefore must accept substantially greater stock specific risk, and other risks. That additional risk is supposed to have a purpose, ie upside. Taking more risk is not an achievement. Generating enough additional return to compensate investors for that risk is. Over the last three years, ARKK did. Whether it's enough, given the extra risk, is up for debate. Personally, given ARKK's massive volatility (which is a sign of a fund manager's immaturity), 33% wasn't enough for me over three long years while every other period underpefromed.
Over five years, ten years and since inception versus the NASDAQ, it obviously did not.
Cathie, you do not deserve applause for taking enormous risk and then underperforming a diversified index. Do not pretend it would be any other way. That's dishonorable.
The entire purpose of taking that additional risk was supposed to be to beat it.
7. Lastly, there is the Morningstar part. This one is comedic and makes Cathie's comments so ridiculous.
Cathie cites Morningstar as the authority validating ARKK's supposed excellence. Fine. Let's use Morningstar.
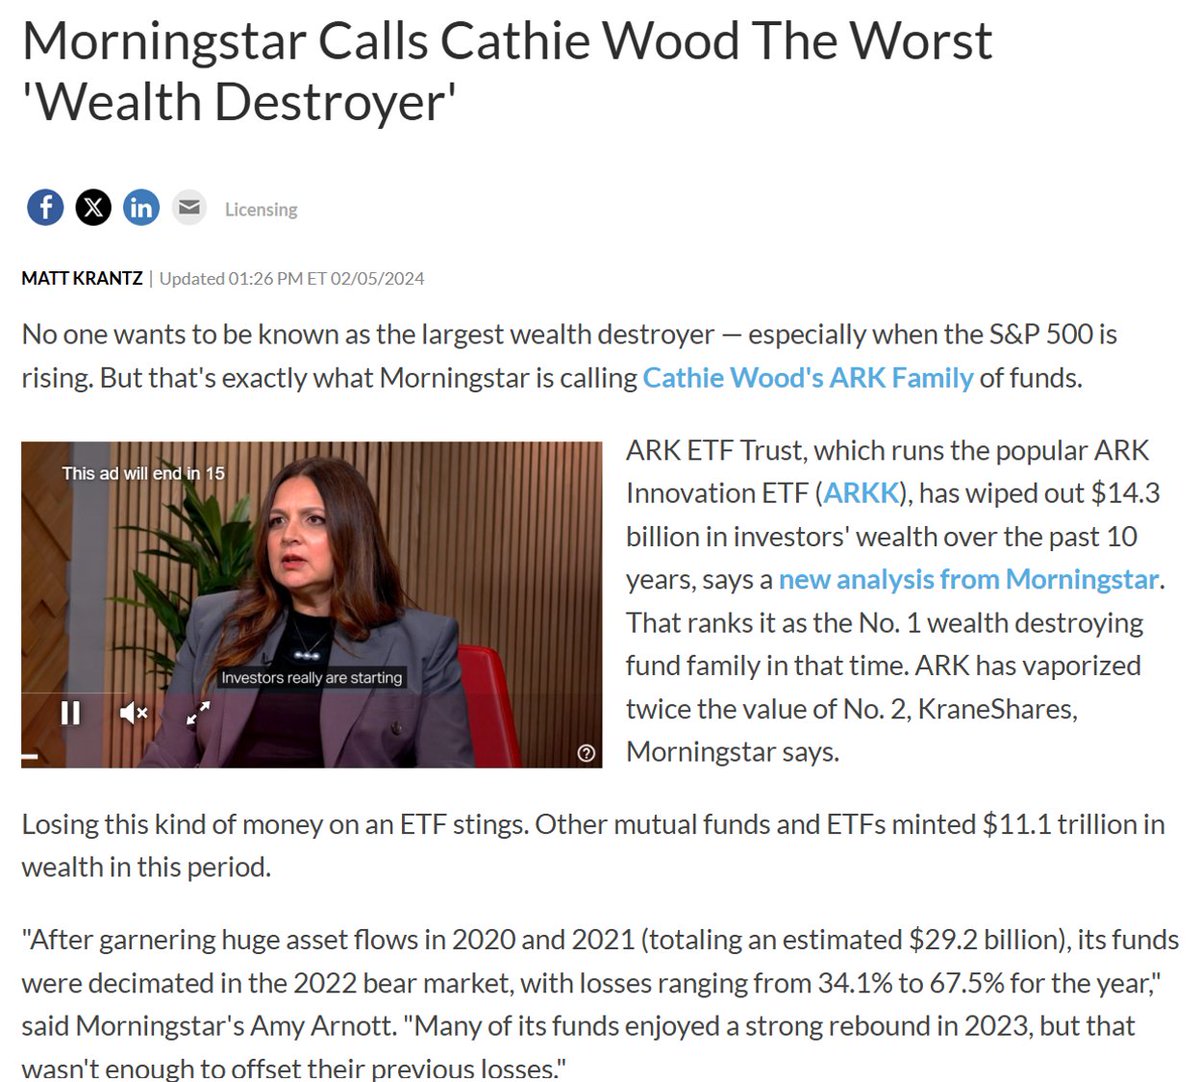
Two years ago, Morningstar analyzed shareholder wealth creation and destruction across fund families (see attached screenshot). Guess who came out dead last, as the largest wealth destroyer in the study?
ARK.
Morningstar estimated that ARK funds had destroyed approximately $14.3 billion of shareholder wealth over the preceding decade.
ARKK alone accounted for roughly $7.1 billion.
Why can a fund have positive point to point performance while destroying enormous amounts of shareholder wealth? Because investors do not all invest on inception day, obviously.
Huge amounts of money flooded into ARK after its spectacular rise, when prices were already extremely elevated. Those investors then participated in the collapse.
So while Cathie likes quoting a hypothetical return beginning in 2014, Morningstar looked at something very different: What actually happened to the dollars investors put into these funds? The answer was devastating and countless investors told me their horrific anecdotes and how they pulled their funds out after sustaining massive losses.
This is the same Morningstar Cathie now cites as validation of ARKK's performance.
Apparently, Morningstar is an authoritative source when its percentile ranking makes ARKK look good.
Then it should probably also count when its analysis puts ARK at the very top of the wealth destruction leaderboard.
You cannot cite the referee only when you like the call.
Bottom line
Cathie is answering a different question from the one investors should care about.
Her question is:
"How highly does ARKK rank within its Morningstar peer category?"
Our question is:
"Did investors get adequately compensated for taking the enormous additional risk of ARKK instead of simply buying an obvious technology heavy passive alternative?" The answer from the numbers is pretty ugly. ARKK trails the NASDAQ by approximately 19 percentage points over one year, 105 percentage points over five years, 103 percentage points over ten years and 138 percentage points since inception.
It wins over three years by 33 percentage points.
That is the record.
And the since inception result is arguably the most damning of all because Cathie started the clock in 2014, immediately before an extraordinary era for technology and innovation stocks. The NASDAQ went up almost 500%. ARKK still couldn't beat it.
And if Cathie wants Morningstar to referee this debate, we are perfectly happy with that. Just don't forget that Morningstar already put ARK at number one on a very different leaderboard: wealth destruction.
***
Personal note: Why does AJ spend time on this?
Because this is exactly why AJ Investment Research exists. We are hardcore investors who became completely fed up with the noise, the bulls**t, the pumping and the endless: "I scratch your back by pumping your stock if you scratch my back by promoting me" on social media. You get rich and powerful business leaders on your podcast or get them to repost your stuff, and this will bring in AuM/fees:
Everybody wants access.
Everybody wants relationships.
Everybody wants to be invited back.
Everybody has something to sell.
And therefore almost nobody calls bulls**t when bulls**t deserves to be called bulls**t.
We set out to do the opposite. Call BS where others will not. Professional investors understand perfectly well what ARKK's record looks like. They understand the drawdowns, the risk, the benchmark problem and the enormous destruction of investor capital.
Privately, many of them will tell you exactly what they think. Publicly? Well, not so much since they have no upside in doing so. Professional etiquette and business interests kick in.
You do not call anoher fund manager's product a joke. You say things like "we have a different investment philosophy" or "we would use a different benchmark" or some other corporate nonsense. We do not have that problem.
We are meta investors. We look through the bulls**t and exploit it for our advantage.
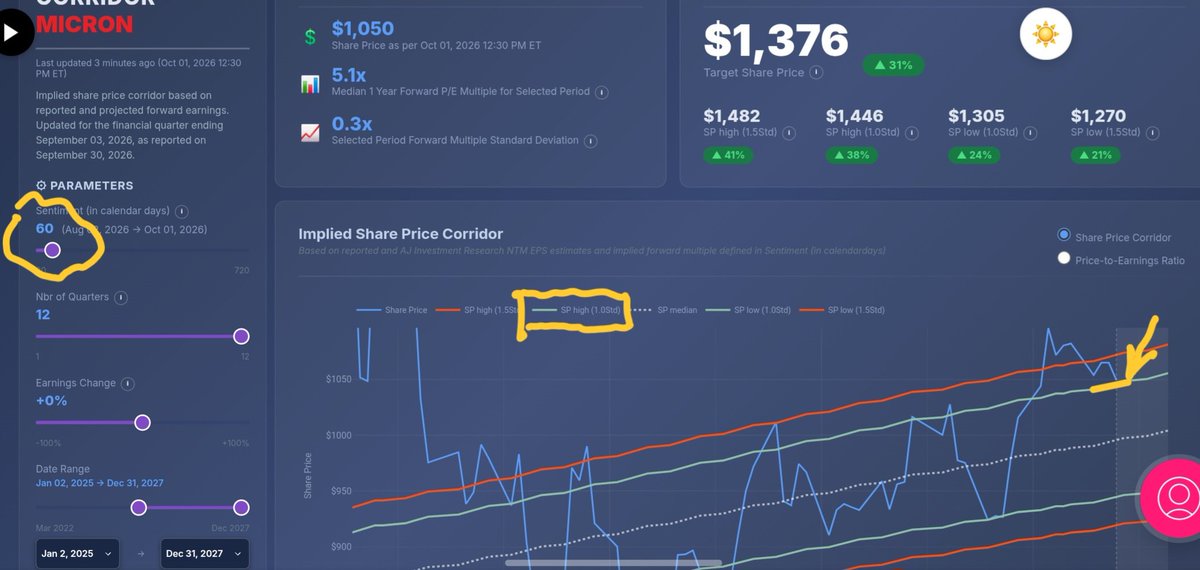
@JefeMcOwnage@alojohhardcore Applying the 60 day corridor MU is scoring slightly above the +1 standard deviation.
If you are looking to hold the stock for a longer period of time this could be one entry...but if you look for shorter term opportunities, others show a more appealing entry point right now
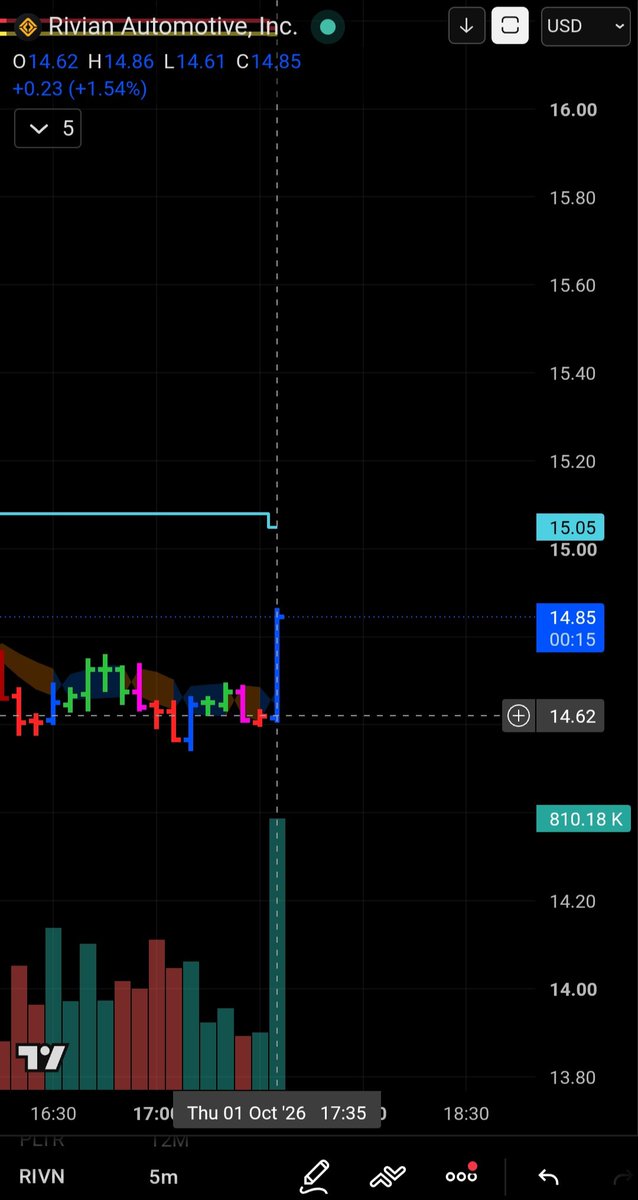
@alojohhardcore Well, i think we can already guess the weight and attention of the HC group: right after your post, in 5 min chart, the price has gone up from 14.62 straight to 14.85 (~1.5%) with a sudden peak in volume...
Could this be? 😀
Hi - there seems to be some kind of bug with the reported daily stock price shown in the corridor. See the post to which I replied here
@ajhardcore_tech