decentralized finance enthusiast, art & design admirer, appreciator of all things digital. Marketing and Advertising Industry. $LINK, $HIMS, $PLTR, $SOFI.
Bangkok Suvarnabhumi Airport right now: lines at the Thai Airways transfer desk amid ongoing disruptions following the recent flooding. September 30, 2026. #Bangkok#Thailand#ThaiAirways
someone built an OpenClaw agent that SELLS pool installations on autopilot.
finds $500k–$1.2M homes without pools
renders a pool in their backyard
and mails a before/after postcard.
In today's episode @superpower CEO Max Marchione came on the pod to discuss whether my $2,000/share intrinsic value target for $HIMS by 2030 is absolutely idiotic or not.
Also, AI doctors, peptides, gene editing and generally, the future of healthcare.
Enjoy.
Only a few years ago in 2021, it was popular belief that Nvidia $NVDA would struggle to overcome Ethereum's merge to proof of stake causing a 60% drop in the stock around that time.
Today, Nvidia is worth more than the entire crypto market.
If you're a $SoFi investor, you really need to listen to this interview by @Futurenvesting .
Devin Ryan is a legendary analyst and outlines his bull case for SoFi in this interview. He recently changed his rating on SoFi from 'Outperform' to 'Market Perform'—not because he's no longer bullish, but because he's recalibrating his price target in response to positively changing market conditions. Will likely see a new (potentially much higher) price target after Q2 results.
Here is the link:
https://t.co/exIAi8EgaA
$HIMS CEO Andrew Dudum nails it: Hims feels like $AMZN and $NFLX in their early days.
The market still doesn’t get it — $HIMS is way more than just a GLP-1 play
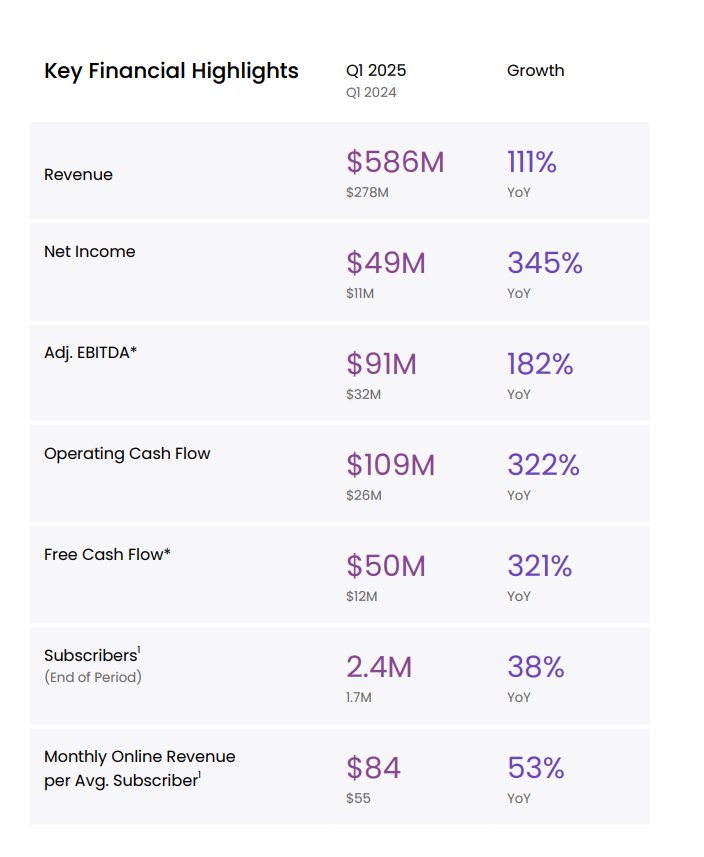
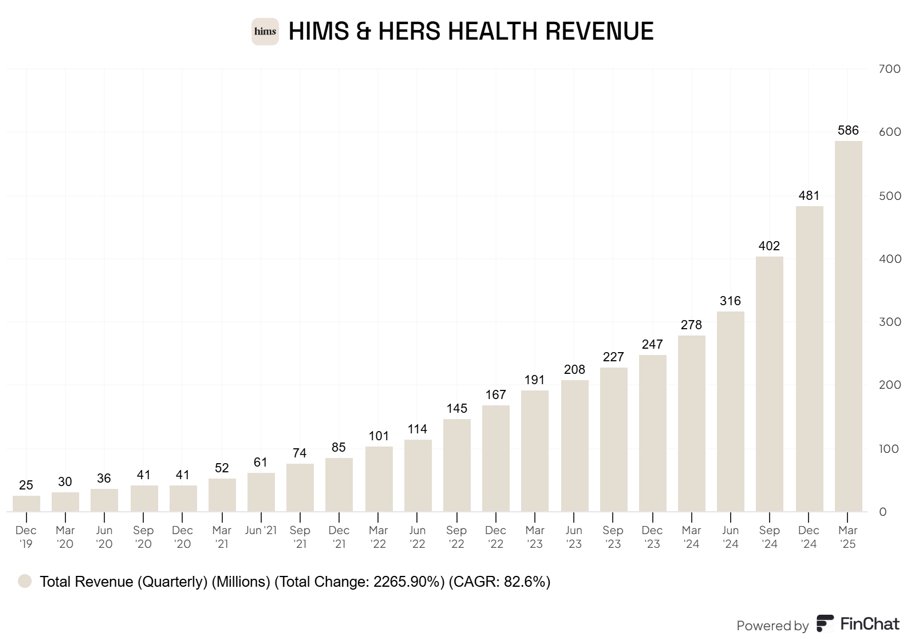
$HIMS just posted their Q1 2025 earnings. Let’s break it down.
Some serious wins, a couple things to watch — but the long-term setup? Still undeniable.
Let’s start off with the incredible fundamentals this quarter:
-Revenue: $586M (+111% YoY) — an absolute monster
-Net Income: $49.5M (vs $11.1M last year)
-Adjusted EBITDA: $91.1M, up +182% YoY
-Subscribers: 2.4M (+38% YoY)
-Monthly Revenue per Subscriber: $84 (up from $55)
-Free Cash Flow: $50M (vs $11.9M last year)
-Gross Margin: 73%
-Cash & ST investments: ~$323M
-Still no debt
The market expected a beat — but not this big:
-Street expected: $538.9M
-HIMS delivered: $586M
➡️ That’s a $47M beat, and 17 points ahead of expected YoY growth (111% vs ~94%)
They’re still guiding to $2.3B–$2.4B for FY25 (same as before), which implies some conservatism. But…
They raised EBITDA guidance and dropped a 2030 Estimate:
-FY25 EBITDA guidance raised to $295M–$335M (from $245M–$285M) 🟢
-Targeting $6.5B rev and $1.3B EBITDA by 2030
➡️That’s a 22%+ CAGR, with 20% EBITDA margin🟡
What’s working best? GLP-1 + Personalization 🟢
CEO @AndrewDudum confirmed that:
-1.4M of the 2.4M subs are using personalized solutions 🟢
-GLP-1 weight loss program is scaling faster than expected
-Average revenue per subscriber is up 53% YoY — this is massive
They’re upselling more effectively, and GLP-1 tailwinds haven’t even fully hit yet.
The Not-So-Good (but not dealbreakers):
Gross margins fell from 82% → 73% YoY 🟡
➤ Why? GLP-1s are higher cost to deliver (branded meds, more touch points)
➤ Still strong, and management reaffirmed mid-70s GM target by 2030
Q2 guidance implies flat QoQ revenue 🟡
➤ Q2 revenue guide = $530M–$550M
Neither issue changes the trajectory — but worth watching.
Now pause and think about this:
$HIMS is trading at ~3.9x forward sales.
They just grew revenue 111% YoY, beat top-line expectations by $47M, and raised EBITDA guidance by $50M.
And that 2025 guidance?
Still only includes a partial impact of branded GLP-1s (Novo deal just kicked in).
If weight loss ends up doing $700M+ this year — the current guidance is already obsolete.
Overall, this was a great—but not perfect—quarter.
$HIMS absolutely crushed revenue and earnings expectations, continued to scale profitably, and raised EBITDA guidance with confidence. The GLP-1 program is clearly gaining traction, and subscriber monetization is improving fast.
That said, gross margin compression and relatively conservative Q2 guidance remind us this is still an execution game quarter-by-quarter. But big picture? The long-term setup is stronger than ever.
This is a company growing >100% at scale, with cash flow, margin expansion, and a massive TAM. If they keep stacking quarters like this, the market won't sleep on them much longer.
Anything I missed?