Rates implied volatility has risen sharply following the latest inflation report and Waller’s comments on a potential 50bp move, led shorter-expiry SOFR swaptions. Markets have modestly increased expected tightening from 20bp to 28bp, while ATM implied volatility has risen 13–15bp across 1M–1Y expiries. The divergence highlights persistent uncertainty around the policy outlook, with investors pricing greater rate volatility despite a relatively modest repricing of the expected policy path.
Fiscal deficits remain structural drivers of 30y swap spreads. CBO estimates 6% of GDP in deficits going forward, and likely to drift higher if Fed delivers on hikes. Regression shows 1% of deficit as a % GDP tightens swaps by about 12.5bps.
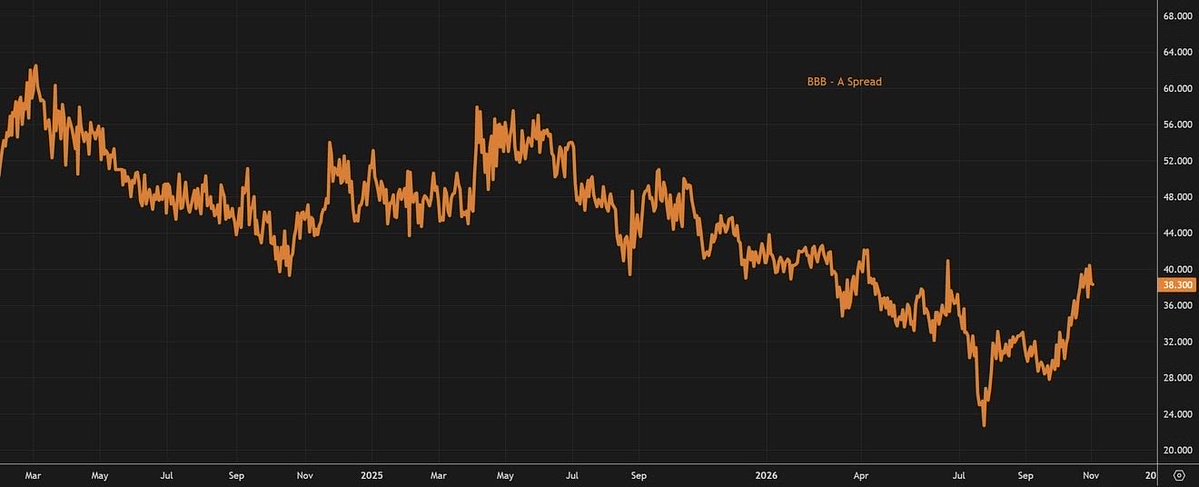
With S&P 500 earnings reported, results have been notably resilient, tracking nearly 10% above already elevated expectations for 29% quarterly earnings growth. The next week will be pivotal, with another 36% of the index set to report. Continued earnings strength should provide a fundamental tailwind for high-grade credit, particularly BBB-rated spreads, which have widened materially in recent weeks.
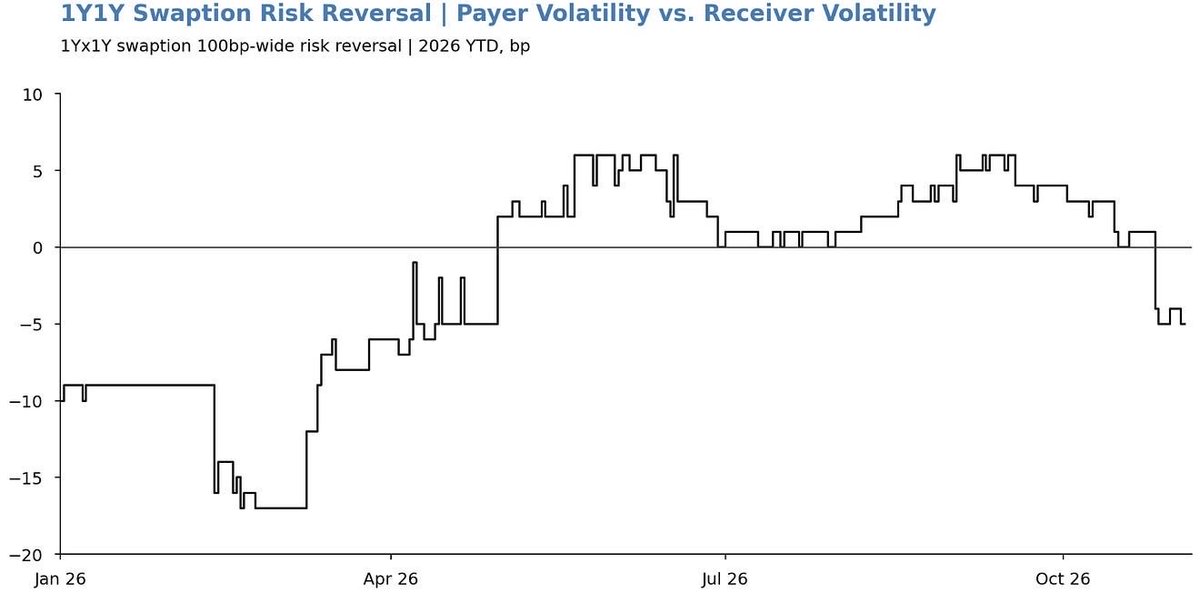
Rates volatility has increasingly skewed toward lower yields. While inflation concerns and Fed repricing drove demand for higher-yield protection throughout the year, renewed AI-related uncertainty has revived left-tail risks. For the first time since the summer lows, lower-yield protection has richened meaningfully relative to higher-yield protection.
Fed tightening expectations continue to reprice higher alongside resilient US economic data. The futures-implied Fed funds trough has risen 110bp from its 2026 lows to 4.1%, as positive economic surprises reinforce a higher-for-longer policy outlook. The market is increasingly questioning how much easing the Fed can deliver. Personally feel the market is mis-pricing how hawkish Fed will be, personally think 1 more hike is delivered and that is it.
Rates volatility has increasingly skewed toward lower yields, with exchange-traded call buying and OTC receiver demand reflecting greater appetite for downside yield protection.
The 1Y1Y swaption risk reversal (OTM payer vol − OTM receiver vol) has turned negative for the first time in months, reversing the sharp payer skew that emerged following the Middle East conflict. The shift suggests markets are increasingly pricing lower-yield tail risks relative to renewed upside pressure on rates.