Is BTC lending the next $1 TRILLION opportunity?
@RiseoftheJAPES walked away from Harvard + Goldman to build @Votre_Inc (part of the @a16z crypto accelerator.... the investment bank of the future:
~ No custody
~ No margin calls
~ Just smart contracts + Bitcoin collateral
Here’s what we cover:
00:00 – Intro to the Block Fuel Podcast
00:09 – Harvard CS → Goldman Sachs: Masterclass in markets before going full Bitcoin
00:25 – WTF “institutions” really are in crypto: RIAs, broker-dealers, hedge funds, corps
03:17 – Leaving TradFi: The system’s broken. Time to build something new.
06:10 – Votre’s mission: A non-custodial lending protocol for crypto’s new wealthy
08:00 – Buy. Borrow. Die. Use BTC as collateral, borrow cash, avoid taxes
11:33 – America is over-leveraged: Why BTC lending is the spread trade of the century
14:49 – The rise of the Bitcoin economy
20:38 – What a16z taught him about building in public and building it right
It was a privilege to play for SDSU. Ultimately, it prepared me for the NFL. When I had a chance to leave the program for $, it was the same coaches who are urging you to leave that urged me to stay. Not every path that presents itself is the one worth taking. Think critically.
got liquidated?
The Public Beta is live! Try it out at https://t.co/jigGNIBNTg
Borrow against crypto in seconds
No liquidations, low rates, high LTVs
Learn how it works at https://t.co/gFwN3qm1rL
Join the LaunchList at https://t.co/5W52YjmPaW
Coolest thing I've seen in the last month:
A 17 yr old is building a world-class mountain bike park in Austin
he found a land investor to buy a $3.2M property (then lease it to back to him) so the total cost is only $350K to do full buildout + begin operations 🤯🤯🤯
"I'm trying to find a quick way to determine if a deal will attract equity investors"
Here it is (ignoring the quality of the business):
-IRR >35% AND MoM > 3.0x in flat/low growth base case without changing historical assumptions
-Price: <4.5X EBITDA (otherwise it prob won't pencil with debt)
-Structure: get close to 80/10/10 (80% senior / 10% seller note / 10% equity)
-Must have seller note. Bonus for forgivable component for downside protection. Bonus for 5% full standby note to maximize the structure
-DSCR >1.5. Anything lower and you're a maniac.
-Operator: obvious or clear fit with business in some way
-No customer concentration >10%. If greater than 10%, must have seller note forgiveness or extreme confidence customer won't go away for 3 years
All the above can flex if there's a unique situation (good or bad)
Above is what I'd put on a pencil napkin and make sure it fits before I waste time sending out an LOI
Miss anything?
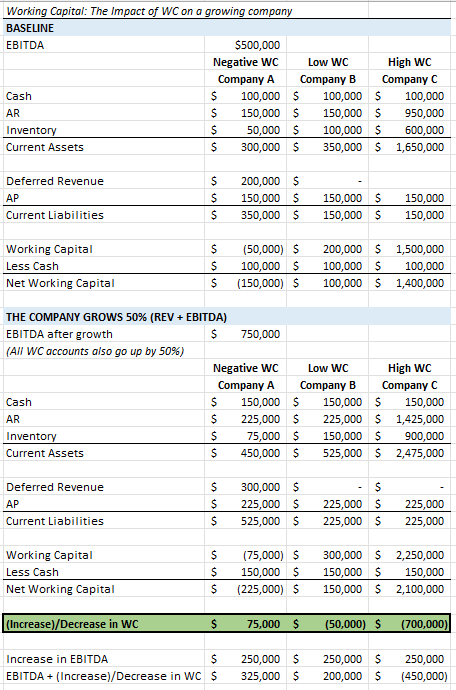
Working Capital 101 🔥
Let me save you years of headache. I've put together an example that should explain everything you've ever wanted to know about working capital
Now you know everything
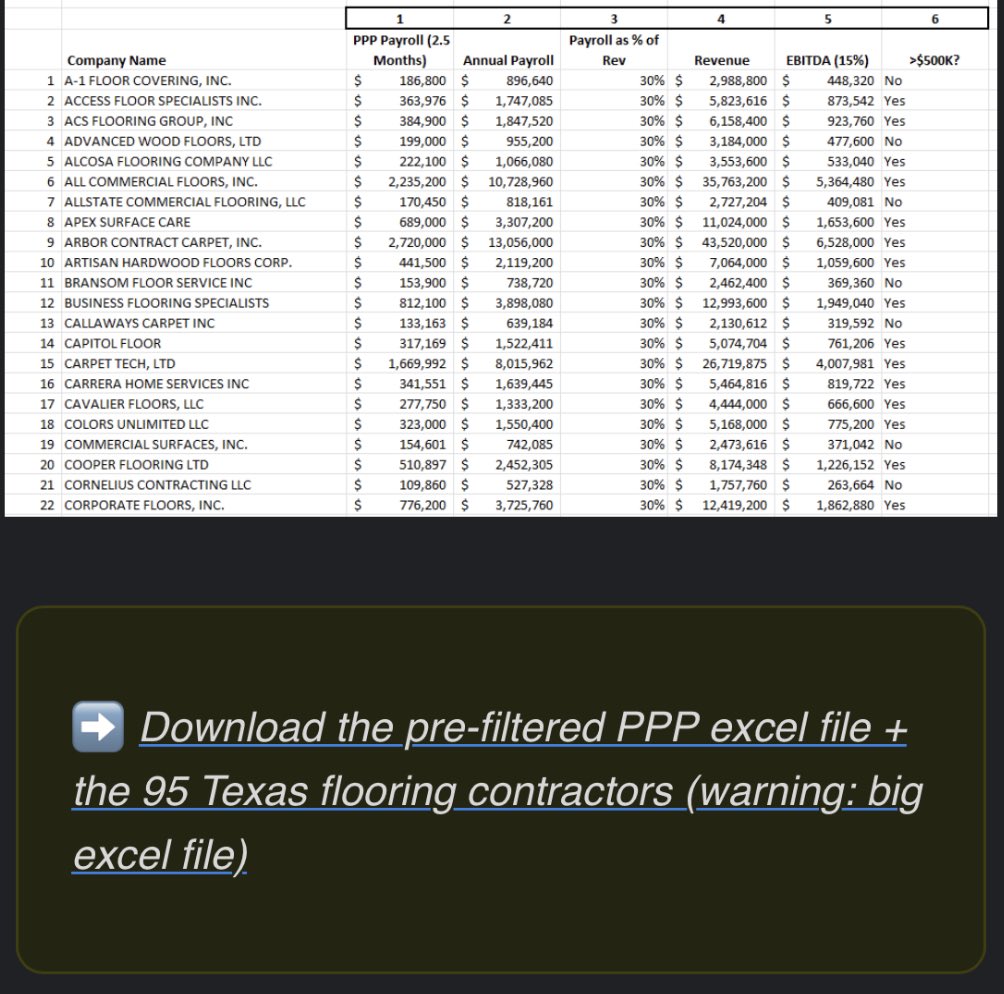
“How to use PPP loan data to find a cash flowing business to acquire?” 🔥
I created a 6 step guide to create actionable acquisition lists from PPP data in less than 10 min
I promise it’ll blow your socks off
Link in the comment:
In my PE days we’d run across ‘SIN’ businesses frequently that fit our criteria
-weapons manufacturing
-gambling / casinos
-tobacco
-alcohol
-military enablement products
However we’d always pass because of 4 main reasons:
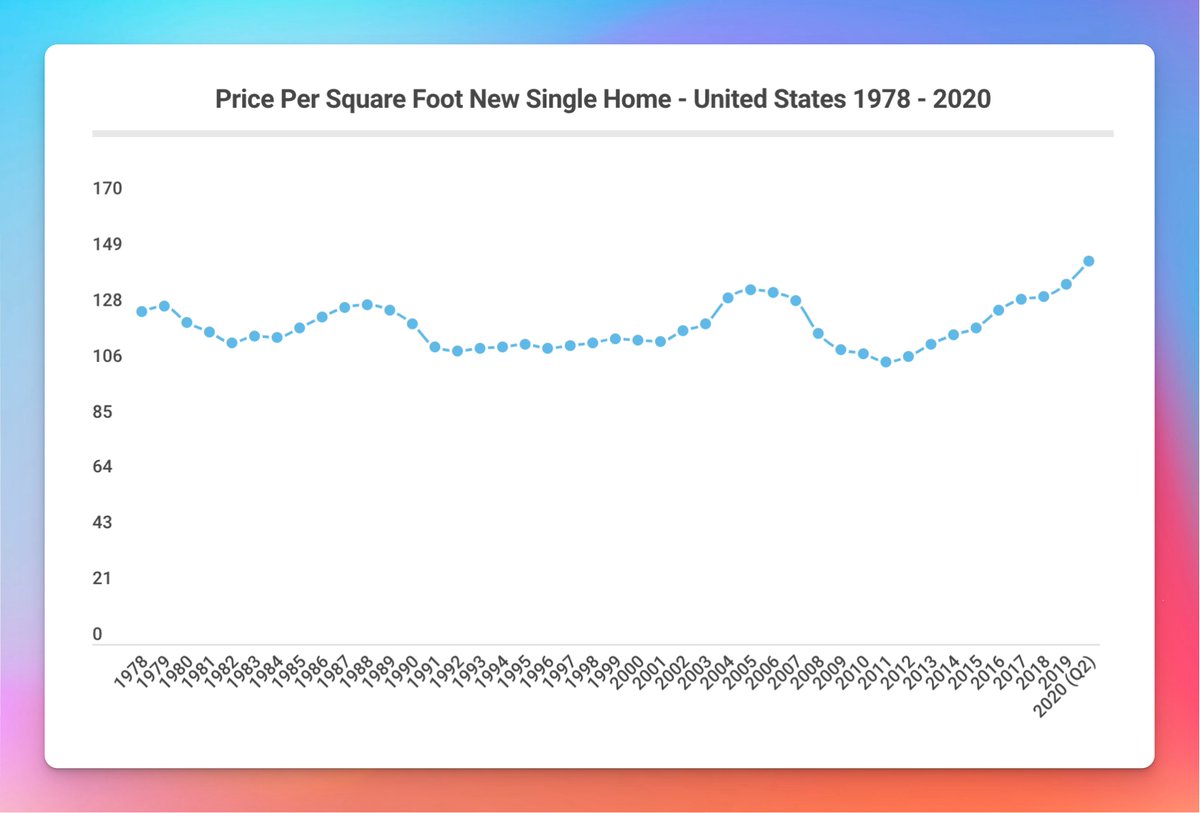
Believe it or not, house affordability hasn't changed much in the last 40 years.
What got inflated was people's desire for bigger and more luxurious homes. The median new house today is almost 1000 sqft bigger than 40 years ago.
Price per sqft, inflation adjusted:
Insider info: One thing you should know about SMB deals is that most are sold between 3.5x and 4x EBITDA
And it’s not driven by buyers unique valuation of a company…it’s mostly driven by how much debt it can support according to SBA underwriting methodologies…this is NOT related to the ACTUAL quality of the company
Many misunderstand this concept
90% recurring rev B2B services = 4x
Construction GC = 4x
They were sold at the same price, but they are not the same quality of biz
What underpins the max purchase price is SBa lending practices, interest rates, and brokers pricing deals….all this puts a max purchase price in a deal assuming 10% equity / 10% seller note / 80% SBA debt of just over 4x (today)
Knowing *why* and *how* you can pay 4x for an excellent company is where massive wealth is made
6 reasons why you won’t ever buy a business
1. Uncommitted
2. Don’t have a Get Shit Done personality
3. Volume way too low
4. Criteria is bad / aimless meandering
5. Low confidence - unwilling to bet on yourself
6. It’s hard
Raising capital for an SMB deal?
Protip: Finding investors is more than $...they are partners 🤜🤛
I'd give up economics for a great investor any day of the week
Recent deal through the Capital Connector...the investor interest is 🔥 and the 'value add' responses are 🤯🤯🤯
Investors: the best self funded deals to invest in are structured well:
1. the price is right (3.5-4x)
2. ~90% leverage (80 sba debt and 10 seller note)
3. step up conversion to equity is fair (2x)
4. pref return 8-12%
Veer too far from this, make sure you’re not the sucker