On @GavinSBaker point about memory LTAs enforceability: $GOOG went from $149bn of purchase commitments at FY, to $332bn in Q1 and $811bn in Q2 (!!). Interestingly, the fine print changed form "mostly related to technical infrastructure and inventory orders" in the 25' 10K to
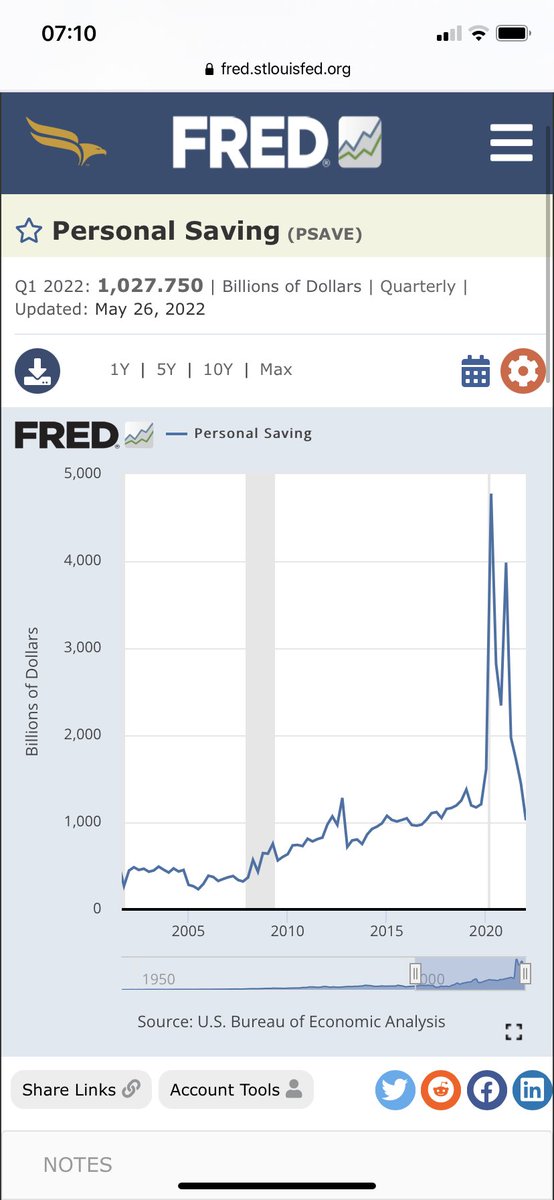
@jay_21_@1MainCapital@modestproposal1 Absolute savings is now back to pre-covid levels as they’ve been depleted by above trend spending on durable and non durable goods. The key question is how low us citizens deplete this further before they stop consuming.
@StratusYoung Over provisionning during an acquisition and releasing it in subsequent years in the P&L. Often goes jointly with an account receivable build up at the target level, which the acquier unwinds once the acquisition completes to mask the non cash income from provision release.
@RyanWilkes20 Think it is more linked to the sector news flow than anything company specific. Amigo going under would actually be another positive news for Morses. Really looking forward to the TU and comments on customer demand / funding arrangement for growth. Time to be greedy.
@chriswmayer@_inpractise Not CEO anymore but Kenny Alexander has transformed GVC (now Entain) from a small German online social casino club in 2008 into an online gambling juggernaut thanks to astute capital allocation.
@RyanWilkes20 You’ve seen that with the digital division which has seen impairment levels à touch above the long term range following the strong customer additions in the past year
@RyanWilkes20 In line but remember that with IFRS 9, big customer growth is followed by upfront impairments, which hurts the P&L in y1 (but not the cash flows!). I.e. if they double users, accounting wise they would have to do a profit warning because of the associated impairments.
@RyanWilkes20 @JimTechAIM If growth is constrained by funding, the flip side is that they will only lend to their best customers, who have lower than average impairment rate, which would make the biz very profitable. Either way, at these prices, barring some unexpected claim deluge, the company is a steal
@RyanWilkes20 @JimTechAIM The plan, as far as we know, was that each sub would have its own credit line since they attracted lenders with different risk appetite. Unclear how scrapping the holdco impacts this. We think it doesn’t, maybe it makes funding slightly more expensive but it wouldn’t be material.
@1MainCapital Best practice would be Ryanair, 2 videos out at 7am with the results: 1/ prepared remarks and 2/ a basic Q&A session with their house broker. The call goes straight to Q&A with the common stuff out of the way. A process as efficient as the company.
@Hedgeman16 Yeah agreed, it’s possible but very unlikely. The takeover is clearly designed to steal the company from minority shareholders so I doubt they would sell post approval.