@rustapharian I hope they don't gamify the Mutual Fund.
I like the Kuvera Clean UI approach, this is the only reason I am using Kuvera other wise there are many better apps nowadays
Hope for the best 🤞
Fund of Funds (FoFs) expense ratio can be misleading! Why? FoF invests in another fund. You actually need to know 'combined' expense ratio. Not always reported in fund factsheets/AMFI & hence in websites that take data from AMFI. Story by @sashindnj
https://t.co/NgN7Q7BBHA
Kind Attention Taxpayers!
CBDT has decided to extend the due date of filing of ITRs, which are due for filing by 31st July 2025, to 15th September 2025
This extension will provide more time due to significant revisions in ITR forms, system development needs, and TDS credit reflections. This ensures a smoother and more accurate filing experience for everyone. Formal notification will follow.
NIFTY to hit 28,300! Part 3 of the Market Strategy 2025 by ICICI Direct research gives our top picks to ride this wave! A 🧵.
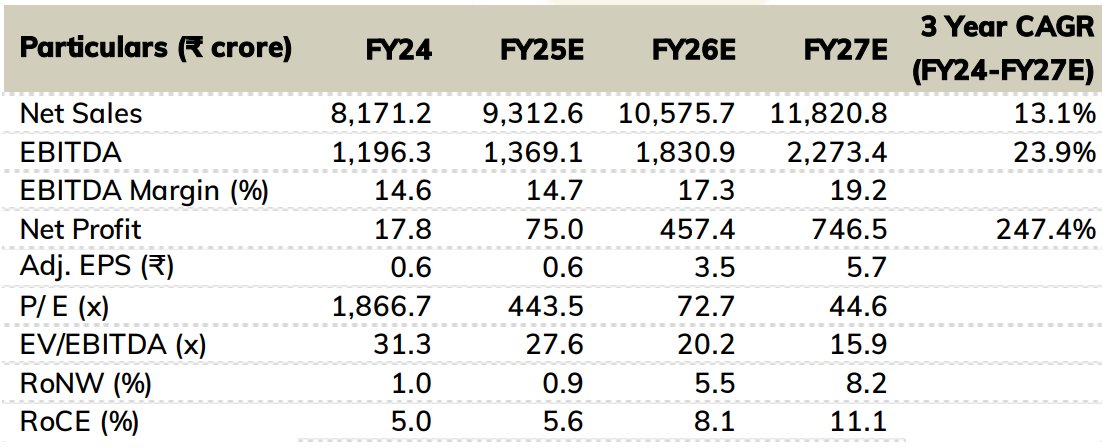
Piramal Pharma (PIRPHA)
A pharma powerhouse, excelling in CRDMO and complex hospital generics, and well-positioned for growth in GLP-1 and ADCs.
Target Price: ₹ 320 (26% Upside)
(1/n)
I am an admirer of #Asianpaints as a company. I grew up hearing from my grandfather about how Champaklal Choksi built the company. When he passed away and his shares were sold to Akzo Nobel, it appeared the company was going to become an MNC. But, it already had all the essentials of a great MNC. There was no need for an MNC to own it. It could remain Desi.
To his credit, Ashwin Dani worked the Indian political system, and somehow stalled the move, despite the best efforts of the Investment banker, who was a formidable and feisty member of his own tribe. Asian paints stayed an Indian firm. Reliance has been an unseen player in this company owning 5% stake in it through one of its numerous investment vehicles.
The Asian paints fable as it was authored and mutated was an exaggeration. It was apocryphal, rehearsed and wantonly done. It lacked depth, understanding and analytical heft. It was based on licentious thinking, allegorical evidence and creative excess. The company’s competitive position, its relative pricing power, the power of its branding were all blown out of proportion. It was primarily a beneficiary of disciplined and rather soft competition. The fable did not factor in the entry of strong competition.
When strong competition entered, the whole edifice of story telling came apart. The reality is not going to live upto the story telling. This has a lot to do with the dynamics of the paint industry. The dealer is a creature of income, an inducer of purchase and an influencer of painter loyalties. He was earning the least margins on Asian paint products. He was using the margins earned from SME’s to fund the Asian paints business. Now the business of SME’s has collapsed with the entry of Birla Opus, JSW paints and the rise of midsized players like Indigo.
It will become impossible for dealers to push SME products the way it happened in the past. Dealers are forced to push Birla+JSW to customers. As Birla+JSW offer better terms than Asian paints and are also getting decent acceptance with painters+customers, this is triggering a shift in dealer loyalties.
To counter this, Asian paints has done a very credible outreach, offered better pricing and tried its best to minimise the damage. This will lead to more aggressive sales generation at lower margins. The evidence is there in the Q2 results.
The decision of Akzo Nobel to exit India by selling its Indian business is further threatening to add more competitive intensity into the paint industry. Akzo Nobel is a sleepy MNC that allowed Asian to gain domination of the entire premium paints segment with least resistance. But, its own brand equity is still very much intact. If the Akzo Nobel business gets acquired by Birla or JSW or A-co, it will further put tremendous pressure on the Asian paints biz. This will start showing in the premium segment, which is still to see deeper impact yet. The battle will then become market wide and this will significantly weigh on the pricing power, margins and volumes of Asian paints.
Asian paints may now be in a tough spot. It may need to buy Akzo Nobel at a very high valuation to ward off the threat from the Birla-JSW duo in the premium segment. Needless to say, this will be a very expensive buy and the markets may not like it at first look.
The story-telling and narratives which were peddled on Asian paints were very raw, unthinking and superficial at so many levels. We were varnishing the truth all along. We completely ignored industry structure changing dramatically, competitive intensity transforming permanently and the industry becoming completely dominated by large organised players. We failed to foresee competition from big players, heavy investment in the industry and the impact of the industry growing capacity way ahead of demand. This will take force start turf wars in every segment of the paint market.
Even a champion like Asianpaints is now on a sticky wicket. The wet paint may end up drying a lot faster.
🚨Early Access To Exclusive Swiggy Report🚨
Swiggy is going for IPO at Rs 95,000 cr valuation - 8.5 times its trailing FY24 revenue.
Rival Zomato has a market cap of Rs 218,257 cr - 18 times its trailing FY24 revenue.
So, Swiggy is giving a 50% valuation multiple discount.
Why❓
Swiggy won the first leg of the race for food and quick deliveries between 2015 and 2021, but now Zomato holds the top position in both segments.
More importantly, Zomato has also been able to reach profitability and break-even across both these segments.
This raises important questions about Swiggy’s future. If Swiggy is to outpace Zomato in the coming decade, incremental gains in market share or marginal growth will not be enough.
The company will need to deliver new products that significantly expand its total addressable market (TAM).
While a publicly listed Zomato chases aggressive targets, Swiggy continues to move carefully in every area, whether monetisation or cost-cutting.
All of this goes back to the very different DNAs of the two companies, which are driven by their founders.
In this extensively researched report, @thearc_hq provides an exclusive profile of Swiggy’s reclusive founder, Sriharsha Majety, based on over a dozen interviews.
We also explore how Swiggy’s top management team is structured, how its product strategy differs from Zomato’s, and what the future may hold.
Link - https://t.co/uO1gTJTIvo
I am extremely frustrated with @Flipkart's so-called “7-day easy return” policy, which has turned out to be nothing more than a scam. I ordered a Skybag bag advertised as 35L, only to discover that it’s actually just 27L—completely misleading!
I am extremely frustrated with @Flipkart's so-called “7-day easy return” policy, which has turned out to be nothing more than a scam. I ordered a Skybag bag advertised as 35L, only to discover that it’s actually just 27L—completely misleading!
I am extremely frustrated with @Flipkart's so-called “7-day easy return” policy, which has turned out to be nothing more than a scam. I ordered a Skybag bag advertised as 35L, only to discover that it’s actually just 27L—completely misleading!
I am extremely frustrated with @Flipkart's so-called “7-day easy return” policy, which has turned out to be nothing more than a scam. I ordered a Skybag bag advertised as 35L, only to discover that it’s actually just 27L—completely misleading!
I am extremely frustrated with @Flipkart's so-called “7-day easy return” policy, which has turned out to be nothing more than a scam. I ordered a Skybag bag advertised as 35L, only to discover that it’s actually just 27L—completely misleading!