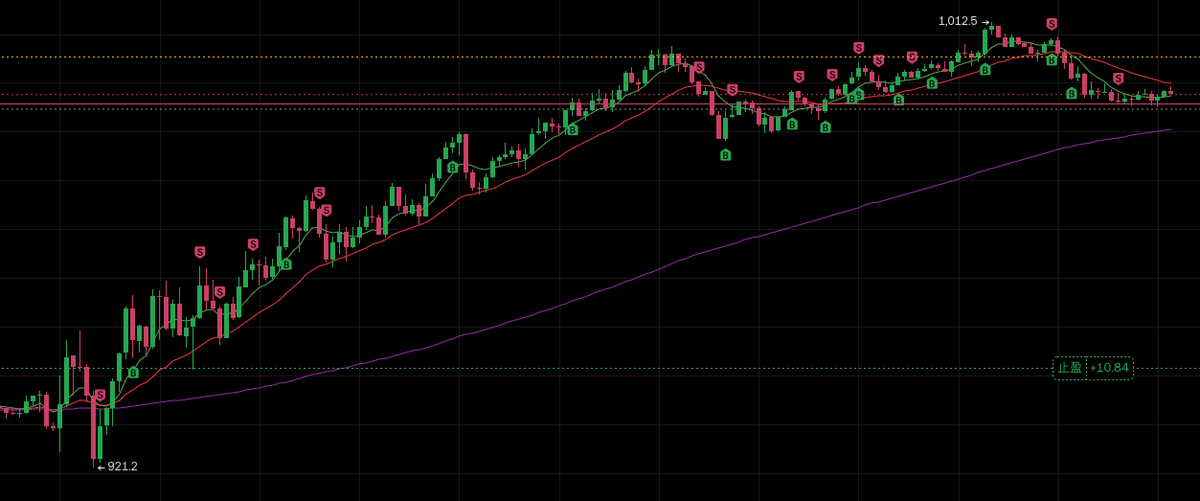
$AAOI is a shitco imo, and demand has nothing to do with it. Demand is fine. The problem is that management's forecasts last about one quarter before they get walked back.
Guidance vs reality:
> Q3'25 call: "meaningful" 800G shipments in Q4'25 → came in below the $4M to $8M they'd expected (firmware)
> Feb: 800G "more than $25M" in Q2 → $12.8M
> Aug: 800G to roughly 5x in Q3 → 3.7x ($47.5M)
> Aug: >$70M of 1.6T revenue in Q4 → now $50M to $70M
> Aug: CEO floats Q4 above $500M → guide is $385M to $420M
> FY26 ">$1.1B" (raised in May, softened to "around $1.1B" in Aug) → implied ~$1.015B, quietly not reiterated
Margins tell the same story:
> Exit 2026 GM target: 35% (May) → 32 to 33% (Aug) → 29.5 to 31% Q4 guide (Nov)
> Q3 non-GAAP GM 28.7% vs a 29 to 30.5% guide, and below 31.0% a year ago
Timelines slip too:
> End 2026 capacity: 650k units/month → >500k (Texas Phase 2 delayed "several months" on power)
> $471M/month revenue run rate: mid 2027 → end 2027
> 2025 capex plan $120M to $150M → spent $209M
This isn't new either. In 2017 the Q3 guide of $107M to $115M got cut to $88M to $89M when Amazon pulled back. In 2018 a laser defect led to suspended shipments, a guidance cut and a securities suit (later dismissed). Same founder CEO throughout.
What bugs me more is in the 10Q:
> Receivables of $413.8M on a $270M quarter. That's ~140 days of sales unpaid
> $234.5M of that is owed by one CATV distributor (Digicomm), which was billed ~$257M in the first nine months. Mgmt says it gave them longer than typical payment terms
> Inventory ~$378M, roughly doubled since Dec
> Q3 GAAP profit came from $8.2M of government subsidies. The operating line was still a $1.4M loss
> ~68M shares a year ago → 90.8M now. Three ATMs this year, plus $125M of 2030 converts now convertible
To be fair, the bull case is real:
> Revenue +127% YoY, 6 straight record quarters
> Demand exceeds supply. A hyperscaler pulled 1.6T forward, and the CEO says there's ~$450M of 1.6T orders in hand
> Signed a multi year 1.6T deal with a Tier 1 hyperscaler. Mgmt sees $1.0B to $1.5B, with a min 10% share through May 2029
> In house InP lasers while the whole industry is laser constrained
> The CATV 1.8GHz cycle is printing: record $110.9M
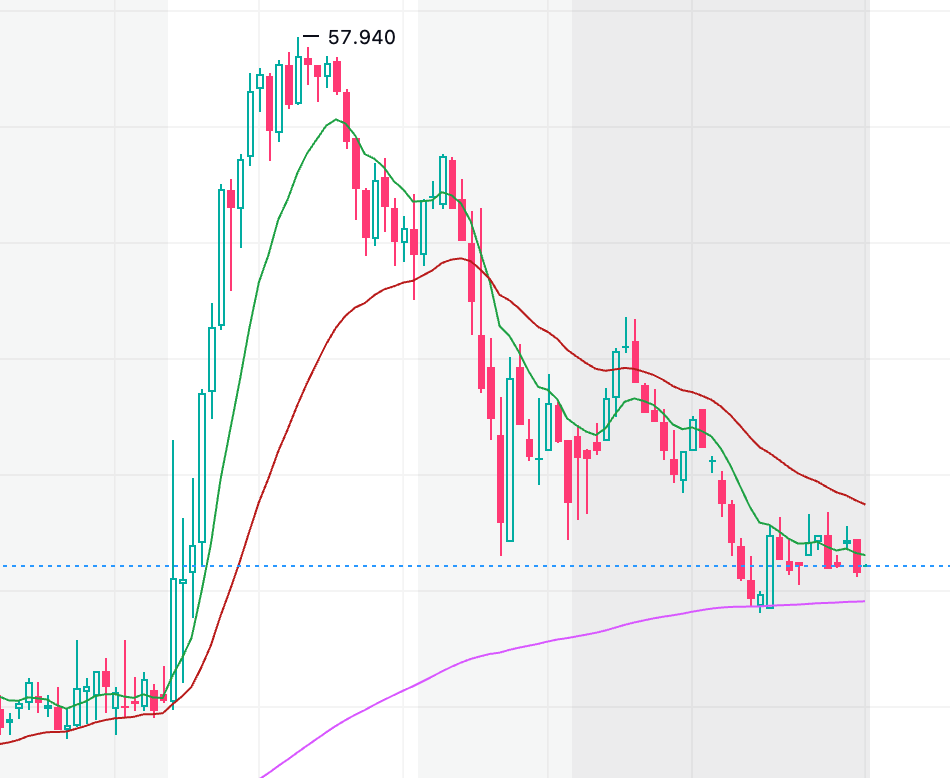
> Credit where due: the last ATM raised ~$588M at ~$105/share. The stock is ~$48 now
> Q4 non-GAAP EPS guide is $0.48 to $0.63. Annualise the midpoint and it's a low 20s P/E
The caveat is that the deal has built in price cuts and no customer capital commitment. The "5x larger" second deal is in "final stages", which is what this team says about everything.
Demand isn't the question. Credibility is. A company that's capacity bound should be the easiest to forecast, and they still miss on nearly every timeline. Until they hit a number they set two quarters earlier, I'm haircutting everything they guide. Q4 is the test: $385M to $420M revenue, 29.5 to 31% GM, $50M to $70M of 1.6T.
Poke holes if you see them.