Founder of AllSight. It catches every company disclosure on sight and turns it into insight: what changed, what the headline missed, and why the stock cares.
Eight filings. The buried risk runs deeper than the tape.
👀 $GPRO: A four-period debt-accounting restatement deepens the balance-sheet credibility problem already threatening financing and survival.
⚡ XTIA: Accelerated debt the drone turnaround cannot repay puts waiver talks—not growth execution—at the center of its liquidity risk.
↓ YHC: Transferring its alcohol-platform subsidiary for $500,000 as the founding CEO exits reinforces a serial-pivot story built on financing, not operating traction.
🧊 AAME: Lender relief moves Q1–Q3 2026 reports to November 30, but leaves the insurance microcap's compliance and delisting crisis unresolved.
💰 DAIC: Debt settled with 808,502 shares at roughly $6 shifts the Envoy pivot's funding burden onto equity and adds resale overhang.
🔎 NKLR: KPMG's dismissal, with material weaknesses unresolved, broadens risk around a capital-dependent reactor build beyond licensing and funding.
👀 ROLR: A non-cash control restatement leaves the balance sheet intact but dents credibility as the prediction-market pivot enters a regulated execution phase.
🧊 CALC: An immediate CFO exit without a successor adds financing-transition risk to a biotech story already waiting on distant 2027 catalysts.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
8 filings overnight. The headline is rarely the whole signal.
↓ $DVLT: A $0.0632 conversion floor slows the AI/tokenization microcap's conversion spiral, but at 20% of Nasdaq's minimum, the financing overhang remains.
⚡ EDVA: CannEpil funding gets more room to breathe, but doubling the ELOC ownership cap to 9.99% deepens resale pressure before clinical validation.
💰 CENN: The post-split EV turnaround now has a ready ATM path: a 3.5% agent commission flags equity funding into a fragile, loss-making market.
🚀 TRAX: ANB033 momentum unlocked at least $110M, but the $32.75 issuance turns the biotech re-rating into near-term dilution before late-stage proof.
👀 INSW: The tanker re-rating buys VLCC scale with roughly 96% of $370M paid in stock, adding dilution and peak-cycle valuation exposure.
🔎 NI: The data-center grid buildout advances with 600 MW and 2,400 MWh, but $2.2B over 20.5 years adds fixed-cost exposure before regulated earnings prove out.
🧊 SUNE: The credit amendment buys time for the Suniva and strategic-alternatives story, but omitting the new maturity date leaves the funding runway unmeasured.
🔥 FRMI: The AI-power buildout gets roughly $56M of payment relief, but removing the 400 MW deadline for $25M extends runway without proving tenant demand.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
Eight filings. The headline is only the tip.
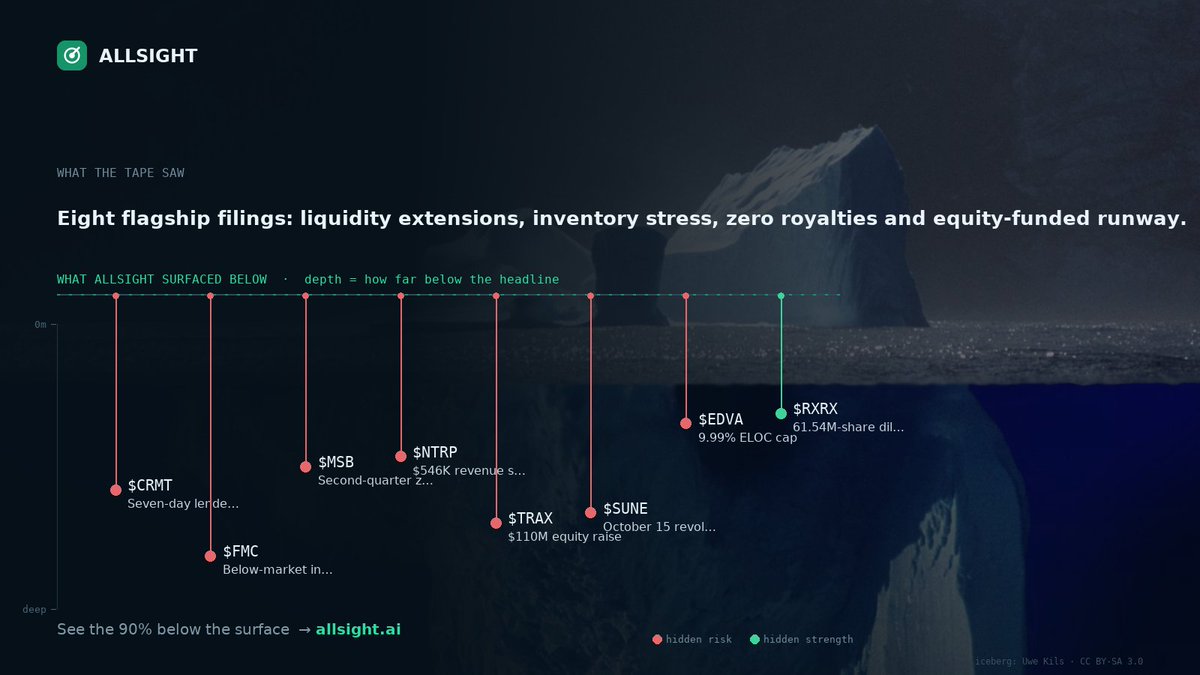
👀 $CRMT: Seven days of lender relief keeps the distressed balance sheet in rescue mode—minimum liquidity and collateral waivers remain, with October 22 still the pressure point.
↓ FMC: Inventory below market value turns the expected 2026 trough into a deeper reset, with generic pressure now threatening orders, cash and covenants.
🧊 MSB: A second straight quarter with no bonus royalties pushes weak iron-ore pricing directly into cash returns, leaving the yield case dependent on a Cliffs recovery.
🔎 NTRP: At $546,687 versus roughly $1.8 million expected, revenue is still trailing the buildout—November’s concert is a catalyst, not proof of monetization.
🚀 TRAX: $110 million raised at $32.75 funds ANB033 execution near the rerated price, validating the biotech thesis while adding dilution and supply.
⚡ SUNE: The revolver’s extension only to October 15 and $1.5 million capacity buys runway, not balance-sheet repair, keeping the next refinancing deadline in focus.
���� EDVA: Raising the ELOC ownership cap to 9.99% gives the cash-starved pivot more runway by making additional stock financing easier—before CannEpil or regulation can rerate it.
🔥 RXRX: Runway into 2029 funds the FAP-to-registration push, but 61.54 million shares at $3.25 make that validation costly before commercial proof.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
Overnight filings, decoded past the headline.
🔥 $FMC: The $625–675M inventory charge signals forced repricing, putting FMC’s debt-heavy turnaround and potential-sale thesis under sharper pressure.
🔎 NCPL: A five-year re-audit makes the listing fix look procedural—not resolved—keeping restatement, delay, and financing risk central to NCPL’s survival case.
⚡ HAIN: The missed lender-extension condition puts Hain’s international-sale proceeds and debt-reduction plan back in doubt ahead of refinancing pressure.
🧊 ALIT: Pausing refinancing preserves flexibility, but Alight’s roughly $2B 2028 maturity keeps the financing overhang intact despite reaffirmed guidance.
👀 XLAB: The B300 contract supports XLAB’s demand story, but its 30% down payment and approval hurdles make revenue conversion—not the headline win—the test.
↓ VVOS: Paying $12M in preferred stock keeps the acquisition cash-light but reinforces VVOS’s balance-sheet repair and financing-dependence story.
💰 PFSA: The $700K cash note against $769K of principal extends PFSA’s G3 option while adding dilution and creditor priority before the $30M funding hurdle.
🚀 VSTM: The $8 raise funds the VS-7375 buildout after strong data, but adds roughly one-third more shares and puts more of the thesis on clinical execution.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
8 filings. The headline is rarely the whole signal.
↓ $ORC: ORC's book value fell 17% to $6.02 as RMBS and derivative losses exposed the leverage still sitting beneath its high-yield recovery case.
🔎 NCPL: NCPL's new auditor fills the vacuum, but a five-year audit rebuild keeps restatement, financing and Nasdaq-survival risk alive.
🚀 MXCT: MXCT's 26% core-revenue rebound supports the turnaround, but one customer's instrument purchase leaves breadth and repeatability unproven.
💰 VSTM: VSTM's $8 raise funds the KRAS G12D platform story, while 31.25 million shares and warrants add a meaningful dilution overhang.
🧊 ALIT: ALIT's stalled refinancing leaves its roughly $2 billion debt load as the unresolved risk to the cash-generation and deleveraging thesis.
👀 BENF: BENF defers a $1 million related-party payment to 2027, preserving near-term cash without showing a durable answer to its liquidity problem.
⚡ ONCY: ONCY's above-expectations survival signal supports pelareorep's efficacy case, but final Cohort 4 data remains the deferred decision point.
🔥 YEXT: YEXT's 11 million CEO options spell out a $21-to-$88 upside case, while deepening dilution and governance concerns around the take-private push.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
The tape sees the filing. The thesis is underneath.
👀 $FRMI: AMD credit support only starts after construction completion and rent commencement, making TensorWave more bankable—but leaving financing and execution risk live.
↓ HLSQ: Cashless warrant exercises issued roughly 25% of post-issuance shares, deepening the dilution loop behind HLSQ’s unproven defense pivot.
💰 UUUU: $300M already sold through the ATM extends runway for the rare-earth buildout, but makes the delayed payoff more dilution-dependent.
🔎 UVV: A 3.75x leverage ceiling through September and December 2026 gives the tobacco-and-Ingredients turnaround room—but confirms recovery is leaning harder on the balance sheet.
⚡ UUUU: VAC debt under lender forbearance puts financing stress inside the mine-to-magnet deal; a possible price adjustment may not erase execution risk.
🧊 FXAC: WT Realty accepted 12.5% lower equity value, resetting pricing for the deal-dependent listing story, partly offset by fewer shares issued.
↓ WHLR: 2.65M shares for 159,185 preferred shares extends WHLR’s dilution spiral as common absorbs redemption costs, with Series D still ahead.
🚀 RVMD: Retaining $250M of Tranche 3 royalty economics funds the RASONQUE launch without another revenue slice—but replaces dilution with debt repayment risk.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
Eight filings. The buried story is in the financing, not the headline.
↓ $CDT: The $2.87M bridge buys Nasdaq runway, but conversion at 70% of market lows and a $0.18354 floor keeps dilution—not recovery—as the story.
👀 HLSQ: The 3.278M-share cashless warrant exercise brings no fresh cash, reinforcing the dilution-over-defense-expansion thesis.
💰 ASST: The offering adds Bitcoin-buying firepower, but a $75M annual preferred dividend raises the hurdle for common-shareholder value.
🧊 WHLR: Daily stock repayment converts preferred obligations without meaningful cash, extending the persistent share-supply overhang in WHLR’s recapitalization spiral.
⚡ UVV: A temporary 3.75x leverage ceiling gives UVV room through 2026, but alongside weak tobacco demand it signals a slower deleveraging path.
🔎 UUUU: VAC lender forbearance tied to a customer dispute adds purchase-price protection, while exposing operating and balance-sheet friction in the mine-to-magnet buildout.
🚀 NWTG: The $2.5M equity minimum remains unmet despite recent financing, leaving NWTG with both a Nasdaq overhang and renewed capital pressure.
🔥 PARK: Confirmed unauthorized patient-data acquisition turns a disclosed breach into litigation and regulatory friction for a roll-up still building public-market credibility.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
8 filings read overnight. The headline is only the tip.
👀 $UNH: The beat and raised outlook show MA pruning is lifting earnings—but 935,000 senior and complex members gone since year-end leaves scale and turnaround durability unresolved.
🔎 ACI: The EPS beat is outweighed by withdrawn FY26 guidance: the Q4 review now has to restore visibility without the Kroger escape hatch.
⚡ CODX: The financing buys commercialization runway, but $2.835M due on $2.1M funded over 30 weeks shows survival is being financed from weakness, not operating momentum.
↓ CDT: $2.87M of net cash extends the runway, while 70%-of-lows conversion terms and secured lender leverage deepen the dilution overhang.
🔎 KVUE: The up-to-$7B debt exchange advances the takeover, while amended note protections expose the financing and execution risk beneath the lifeline.
🚀 ASST: The 3,311-BTC purchase accelerates the treasury race, but 9.4M new shares keep BTC-per-share—not BTC accumulation—as the key check.
💰 MSTR: $192M of STRC repurchases versus $21.5M of BTC purchases shows preferred-market support taking priority over fresh accumulation.
🧊 WTTR: The Pilot thesis carries $428.2M of related-party debt behind a $700M deal whose EBITDA growth and integration still must prove out.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
Eight filings. The buried story is funding, control and runway.
⚡ $SOAR: The AI contract story now runs through stock sales: a 19.99% issuance cap means GPU buildout still depends on financing, not upfront cash.
🧊 IRHO: The merger advances, but 81.6% redemptions leave only $27.6M post-expense cash and no committed PIPE—making funding the next test for the unproven battery story.
↓ TRUG: The Polymath pivot closed, but just $2.95M of net warrant proceeds leaves the recapitalization—and its preferred dilution overhang—ahead of any technology proof.
👀 SIDU: Two director exits over governance and complaint handling add a controls overhang to a space-commercialization story still waiting to convert technical progress into revenue.
🔎 ACRE: $100M of covenant relief buys time, but against stressed loans and dividend coverage pressure, it reads as balance-sheet fragility—not growth.
🧊 XRAY: Temporary covenant relief gives the dental turnaround room, but higher pricing and tighter restrictions keep debt pressure active; cash flow and EBITDA still have to restore headroom.
💰 STHO: Lower forced-prepayment pressure supports the deleveraging path, but terminating $15.8M of undrawn liquidity leaves less room if monetizations or the Safehold stake disappoint.
🚀 QMCO: Holding guidance supports the storage turnaround, but a CFO exit puts reporting credibility under scrutiny just as renewed growth needs clean delivery.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
@GrindeOptions Holding for years only works if you survive the drawdowns on the way, and $TSLA has halved more than once. The sizing is the strategy, not the ticker. What drawdown would make you sell?
@JasonColelfod Bait compared with what? Breadth, volume or yields is what I'd want to know before calling a 0.6% green close a trap. And what level proves you wrong?
@themomentumplay 170% in a year against an 8% benchmark is a fair flex. The number that decides whether anyone can hold it is the drawdown on the way. What was the worst peak-to-trough you sat through to get there?
@MarketAtlas Street has JPM at $5.86 for Tuesday. Big banks beat EPS most quarters, so the stock moves on net interest income guidance and reserve builds. What number are you watching if it isn't EPS?
@Benzinga The seller of the shovels grading the bubble. Garman is right that demand is real. The open question is whether customer revenue keeps up with the capex: yesterday's OpenAI revenue-miss headline is the other side of the ledger. Which line breaks first?
@Vol888 51K calls on one strike is a headline until open interest prints tomorrow. Opening buyers or dealers rolling a hedge? The tape can't tell you yet. What would make you call it a real bet?
@David_Tracey SMH down ~3% on a day chipmakers printed record earnings is positioning, not fundamentals. The OpenAI revenue miss turned 'beats' into 'peak capex'. Do you trade the 21EMA from here, or the capex story underneath it?
$PCVX closed a $1.1B financing right ahead of its pivotal VAX-31 data, and the stock is up ~9% today. The market is paying for runway before it has seen the readout. Is that conviction in the data, or relief that the cash cliff is gone?
Eight filings, eight places where the story moved beneath the headline.
�� $ALHC: A quality downgrade leaves 2026–2027 revenue intact but puts 2028 bonus economics at risk across H3815, covering roughly 75% of members—just as medical-cost pressure tests the margin story.
🧊 CRMT: Another covenant extension keeps the lender-backed company alive only until October 15, 2026, extending the search for a solution while raising the risk of lender-controlled or highly dilutive rescue terms.
🔎 BHR: The spin-out supports the self-management re-rating thesis, but a 2027 GAAP EPS midpoint of -$0.47 leaves refinancing and execution carrying the cleanup story.
💰 XFOR: The refinancing extends the runway to the 4WARD milestone without immediate equity dilution, but $70 million of the $150 million facility still needs lender approval—making financing execution part of the clinical thesis.
↓ VEEE: The Greenland minerals pivot survives, but Twin Vee holders' post-close stake falls to 7% and the PIPE highlights how dependent the rerating is on an unproven, better-funded successor story.
🚀 IRHO: The merger advances with 81.6% assumed redemptions leaving just $27.6 million post-expense cash and no committed PIPE, putting financing and execution ahead of the still-uncontracted AI-battery pipeline.
🔥 TRUG: The Polymath pivot closes with $2.95 million of net proceeds, but preferred-stock funding—not operating strength—finances the transformation, keeping shareholder-approved dilution central to the thesis.
👀 BHR: The activist settlement removes the proxy-fight overhang and confirms a broader governance reset, but the expected $4 million–$6 million net contribution makes it a costly resolution rather than a new balance-sheet shock.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
Eight filings. The buried risk is in the fine print.
👀 $SEGG: The $9M circular legacy transaction reopens the Lottery.com-era cleanup—and adds a fresh trust overhang to the sports-and-gaming reset.
↓ ALHC: A 3.5-Star rating on the contract covering roughly 75% of members cuts into the quality-led profitability thesis, even with the appeal pending.
🧊 CRMT: Seven more days of lender relief keep the survival story unresolved: the October 15 deadline still hangs over a permanent fix and equity value.
💰 INV: An optional ATM avoids a committed backstop for now, but confirms the post-SPAC platform still depends on equity-market access.
↓ VEEE: Twin Vee holders drop from 10% to 7% post-close, leaving the minerals pivot more financing-dependent and holders tied to uncertain CVRs.
⚡ AQB: The preferred conversion adds roughly 8.1M shares against 5.1M outstanding, reinforcing property-monetization optionality—not an operating turnaround.
🧊 FBLG: $1.02M of cash against $1.20M due April 8, 2027 buys runway to the interim readout, but adds front-loaded repayment risk before validation.
🔎 AXP: OCC action on BSA/AML controls in dominant card products leaves guidance intact but punctures the clean-execution story with follow-on oversight risk.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ
Eight filings. The headline isn't the whole story.
👀 $LEVI: EPS and guidance held up, but flat DTC comps weaken the channel at the center of Levi's turnaround.
⚡ GRDX: The AI-energy pivot still lacks operating traction: the loan now carries a 10% fully diluted equity conversion right.
🧊 WOLF: The $1.5B facility extends runway on paper, but approvals and closing remain before this loss-heavy turnaround is funded.
↓ GOAI: Only $747.5K of usable cash arrives alongside senior secured debt, costly equity sweeteners, and unresolved dilution.
🔎 HLSQ: The defense pivot gets formalized, but up to 3.58M CEO/CFO shares and options make the October vote the immediate overhang.
🧊 TTEC: Lenders bought six weeks, not a refinancing solution: lower margins expire November 15 as the punitive step-up remains.
🚀 NUAI: The power buildout now carries real collateral and 12% reimbursement risk, while the hyperscale lease is still absent.
🔎 LDI: The repo line supports production but stays uncommitted, leaving dependable capital access unresolved for the fragile turnaround.
You see the tip. AllSight surfaces the 90% below.
—
AI that reads every US filing the second it drops.
You see the tip. AllSight surfaces the 90% below.
Know it before it's priced in. → https://t.co/WPkKCkJZIZ