A US-based professional who frequently travels globally for business shares insights on US stock investment and reminds investors to manage risk rationally
Trade the setup not the hype
I focus on AI, semiconductors, memory & ETFs
looking for opportunities backed by real momentum, not FOMO
I share trading plans, entry/exit points, and risk management in my community
Contact me to join👉https://t.co/egk1sNBJt0
Some new followers bought the dip after days of market declines, only to lose money. I’m sorry to hear that.
I’ve been warning my community about these risks. Don’t guess the bottom. Let the market confirm it.
Haven’t joined yet? Contact me
Trade the setup not the hype
I focus on AI, semiconductors, memory & ETFs
looking for opportunities backed by real momentum, not FOMO
I share trading plans, entry/exit points, and risk management in my community
Contact me to join👉https://t.co/egk1sNBJt0
What if $TSLA and $SPCX built a combined AI empire spanning robotics, energy, satellites, and space? The potential is huge but will shareholders actually benefit? Let’s look beyond the hype and follow the numbers. 👇 https://t.co/qN01SxBaSG
@GreenDarts88 I don’t think the bears betting against $SMCI will win. In the long run, I believe the bulls have the higher probability of coming out ahead
$SMCI : Strong Earnings, But Wall Street Still Doubts It
SMCI just delivered a major upside surprise
• Revenue guidance raised to $18.5B–$19.5B, well above expectations
• Gross margin guidance improved to 12%–12.5%
• Strong AI server demand continues to drive growth
Goldman Sachs still rates it Sell with a $34 price target, citing valuation and funding risks
My take: I remain bullish on SMCI’s growth potential. AI demand is real, and improving margins are an encouraging sign. The key is whether the company can turn explosive revenue growth into sustainable profits and cash flow.
Watch the Nov. 3 earnings call. The opportunity is there, but execution matters
Not investment advice
$META & $GOOGL : I’m Still Bullish, but I’m Not Buying the Dip Yet.
I highlighted this risk in my community earlier: AI spending is growing rapidly, and cash flow and revenue growth deserve just as much attention.
META reported negative free cash flow of $2.1 billion in Q3 as capital expenditures exceeded operating cash flow. The market is questioning whether these massive AI investments will generate sufficient returns.
My view hasn’t changed.
I still believe META and GOOGL have strong long-term opportunities in AI and digital advertising. But even great companies aren’t always great buys at every price.
I’m not rushing to buy the dip. Before opening new positions, I want to see spending translate into sustainable growth, cash flow improve, and price action stabilize.
When I’m ready to establish a position, I’ll share my research and trading plan in the community.
I’m bullish on the businesses, but cautious about timing.
Would you buy this pullback or wait for further confirmation?
$META : Revenue beat expectations, while earnings fell short; AI investments continue to ramp up
Meta Platforms Q3 revenue rose 26% to $64.6B, beating guidance. But a $9.9B legal charge weighed on earnings as AI spending continues to climb
Goldman Sachs maintains a "Buy" rating on META, with a price target of $860
The core question remains: Can these AI investments be translated into sustainable profits?
The community will be publishing my views today
I have been emphasizing this point both within the community and on X : now is definitely not the time to blindly open new positions. You should re-evaluate your investment portfolios and, if necessary, consider reducing your risk exposure.
For those who have not yet joined the community, please click on my pinned post to get in touch with me $SPY $QQQ $NVDA $SNDK
US stocks may be heading for a short-term pullback.
The real risk may not be an AI bubble it could be Treasury yields, with the 10-year yield approaching 5.7%
If yields spike too quickly, high-valuation tech stocks could be among the first to feel the pressure
Don’t just watch $NVDA Watch Treasury yields too.
I’ll be keeping a close eye on this and sharing the trades I’m watching inside my community
Join us and be part of the discussion
AI stocks just took a beating. Is the next big opportunity forming?
The $QQQ fell 5.49% in a week, $SOXX dropped 11.41%, $MU lost 14.59%, and $SNDK plunged 17.86%.
NVIDIA’s Berlin GTC brings fresh optimism: faster AI data center deployment, expanding supply chains, and new real-world AI applications.
But a rebound isn’t a confirmed bottom.
I’m watching $NVDA, $MU, $SNDK and optical stocks. Follow the money, watch earnings, and don’t buy every dip. Great companies aren’t buys at every price
Traders, we opened a new position in $WORX yesterday
As I mentioned, this is a short-term trade, not a long-term hold
On Oct. 19, the company announced an agreement with a community healthcare system serving New Mexico, Arizona, Colorado, and Utah to provide healthcare supply chain data management services
Combined with speculative interest and momentum trading in small caps, this has created short-term upside potential. $WORX continued moving higher today
Updated entry and exit levels are posted in the community. Check the latest updates and stick to the trading plan
The market may be overlooking the broader picture.
This brings $NBIS and $IREN into focus.
Microsoft’s ($MSFT ) withdrawal from its partnership with NScale does not mean that demand for artificial intelligence (AI) is fading. Instead, it highlights a more pressing challenge: power supply and delivery timelines.
Microsoft still requires computing power. If one provider fails to deliver on schedule, companies with already-energized capacity and a proven track record of execution may stand to benefit.
In the realm of AI infrastructure, while demand is certainly important, it is the ability to deliver that ultimately converts demand into revenue
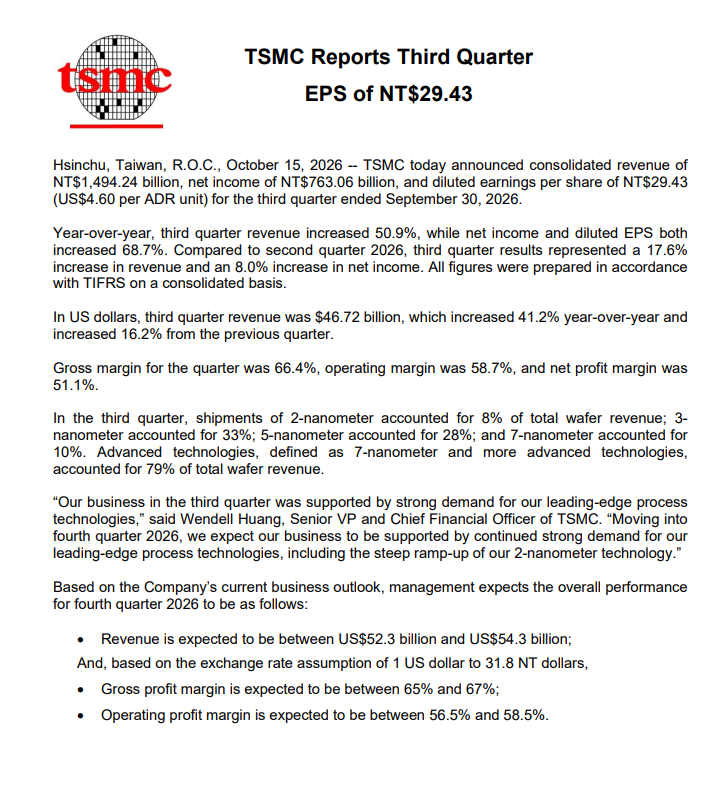
$TSM Q3 Earnings: AI Demand Is Still Strong
TSMC just delivered a powerful quarter.
📈 Revenue: $46.72B (+41.2% YoY)
💰 EPS: NT$29.43
🔥 Net income: +68.7% YoY
📊 Gross margin: 66.4%
⚡ Operating margin: 58.7%
Q4 guidance:
• Revenue: $52.3B–$54.3B
• Gross margin: 65%–67%
Advanced nodes (7nm and below) accounted for 79% of wafer revenue, highlighting continued demand for leading-edge chips
My takeaway: AI chip demand remains strong, and TSMC is still a key player in the AI supply chain.
But with expectations already high, can $TSM keep delivering enough growth to justify its valuation?
Are you bullish on $TSM here, or waiting for a pullback?
Honestly, I’m not too worried about AI today.Don’t just watch $NVDA, $AVGO, $AMZN, $GOOG, or $AMD
What worries me more is:
Oil $100+
10Y Treasury 5.3%+
30Y Treasury 5.7%+
I think the market has already started to reprice valuations.
AI demand is still there. But if the cost of capital keeps rising, the stocks most likely to get repriced first are the ones with the highest valuations and the biggest expectations.
So today, I’m not rushing to sell, and I’m not rushing to buy the dip either.
I want to see first:
Where is the money coming out of, and where is it going next?
If you’re also watching AI / semiconductors / memory, that question may matter more over the next few days than simply asking, “Which stock should I buy?”
I’ll share my watchlist and the specific price levels I’m watching inside the community