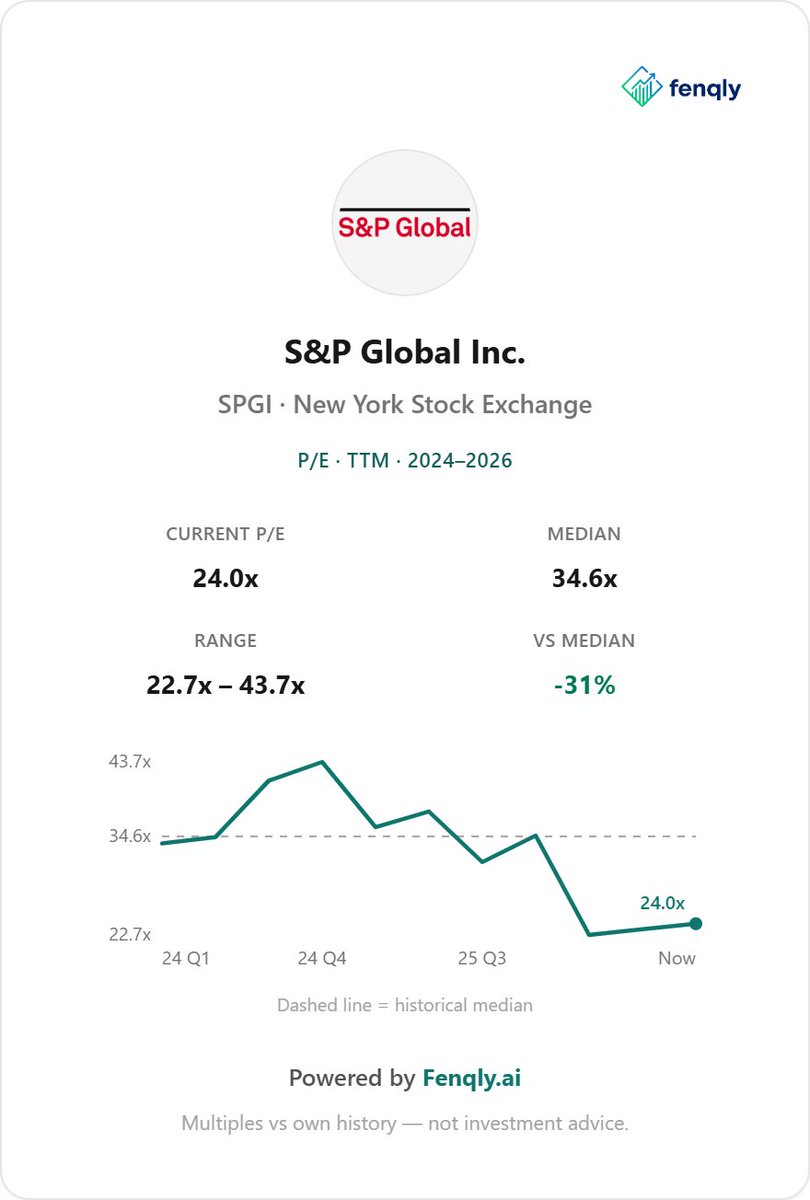
@WillBiddy_ agree on the business. a 46% operating margin is the pricing power in the print. and 24x is cheap versus a 35x median of its own history. the line i wouldn't sign is nearly 0 downside. a 5% fcf yield still needs the growth to get you to 10.
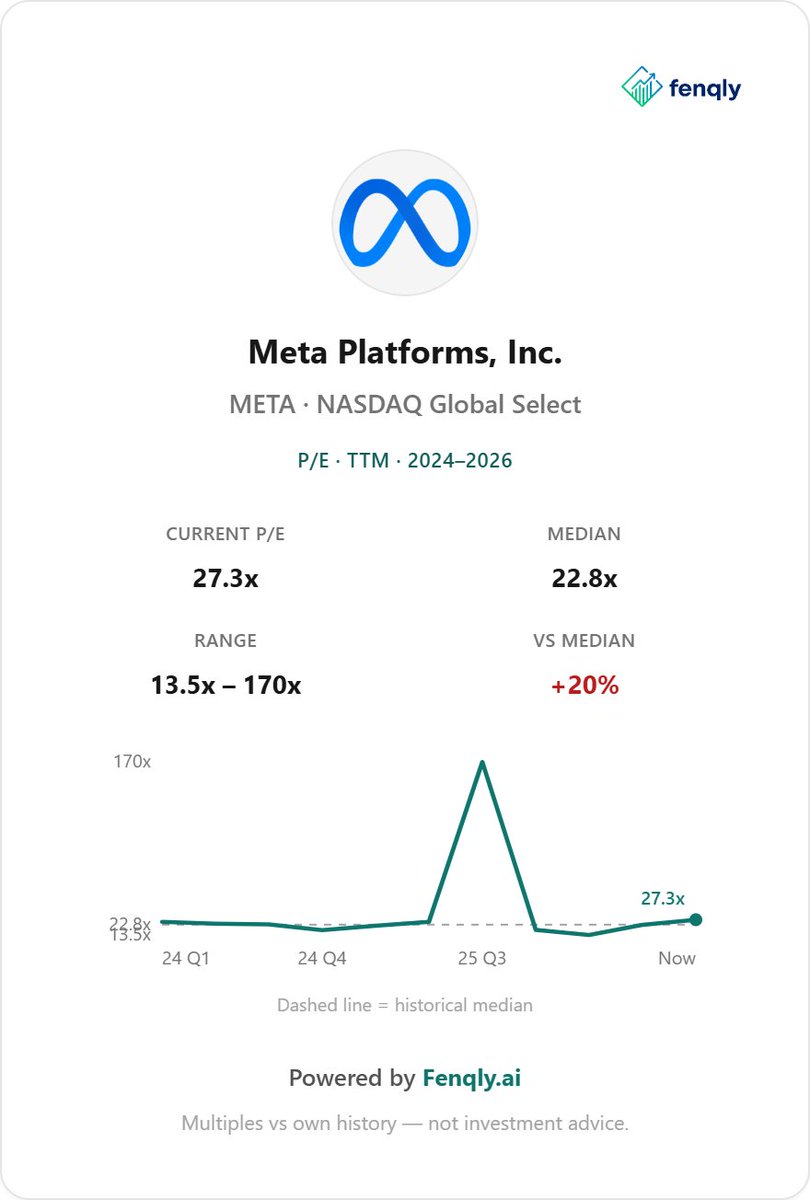
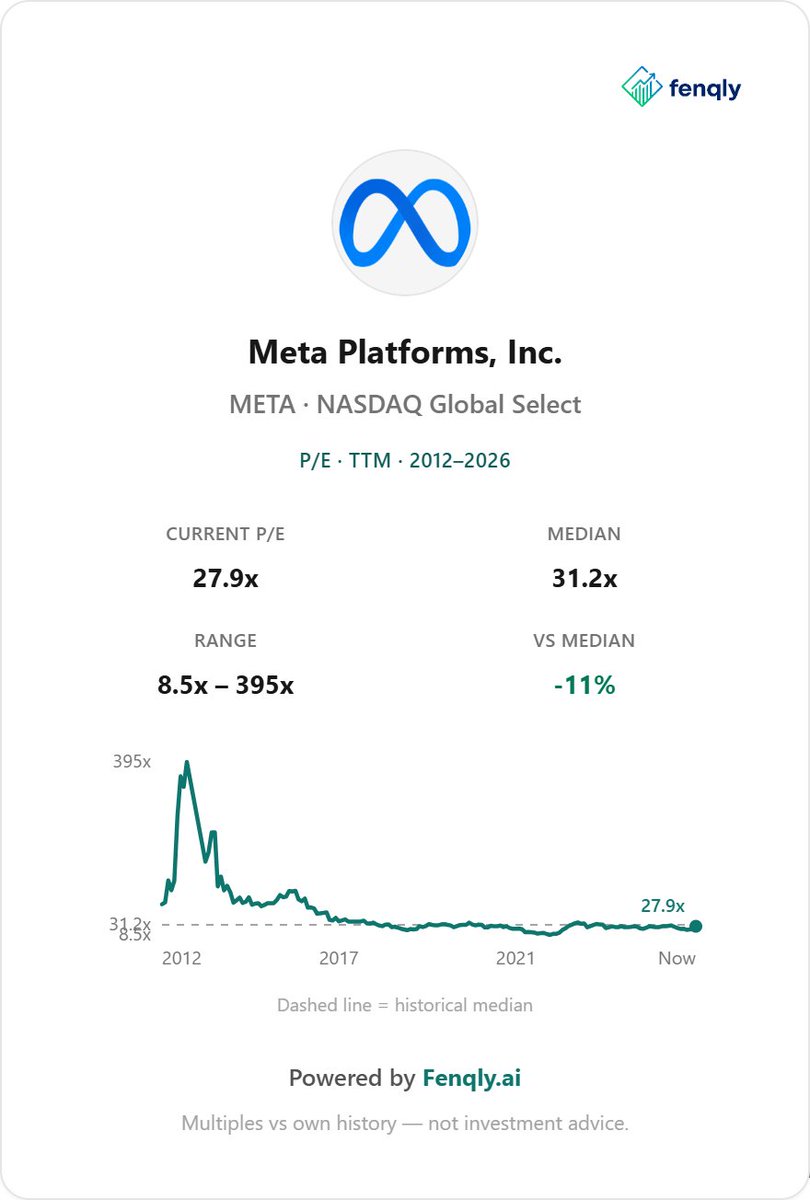
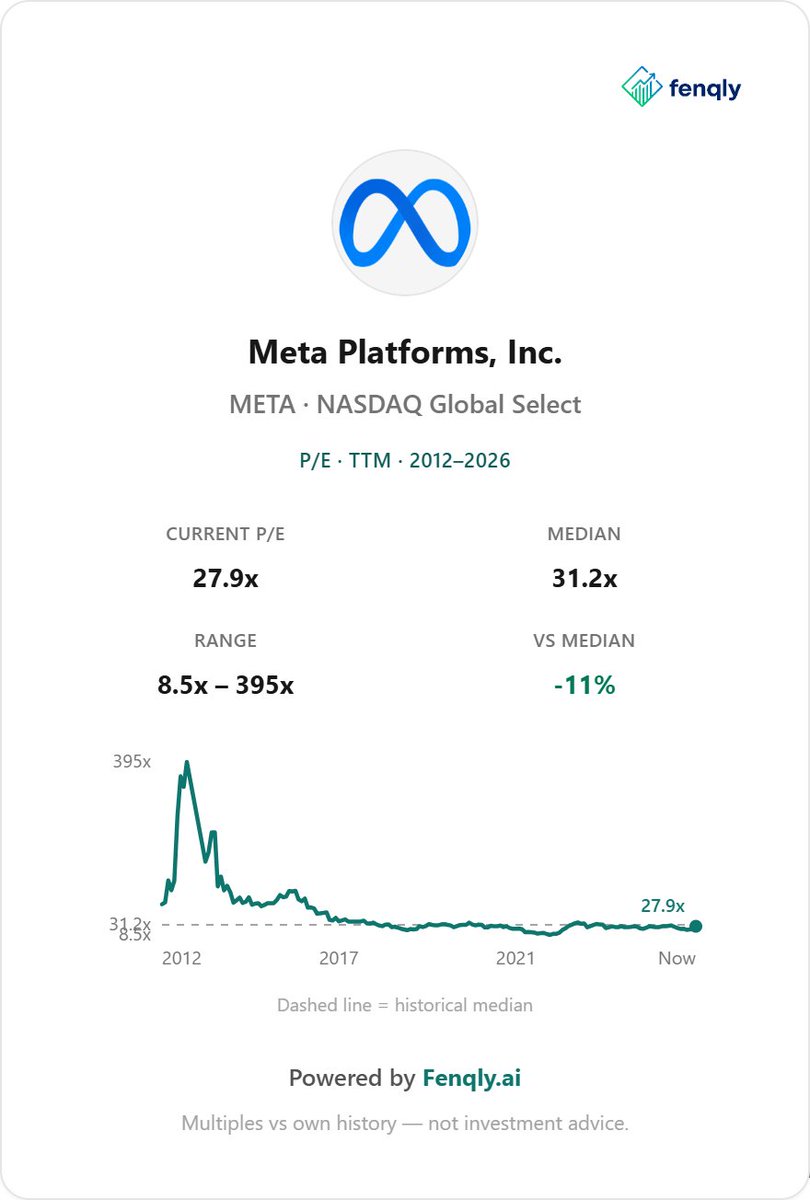
@LukeBruni17 love the chart. on the current print $META already keeps a fatter operating margin than $GOOGL, about 38% versus 33. so the buy is whether 27x, above its own history, is the right price for a lead that hasn't shown up in ad revenue yet.
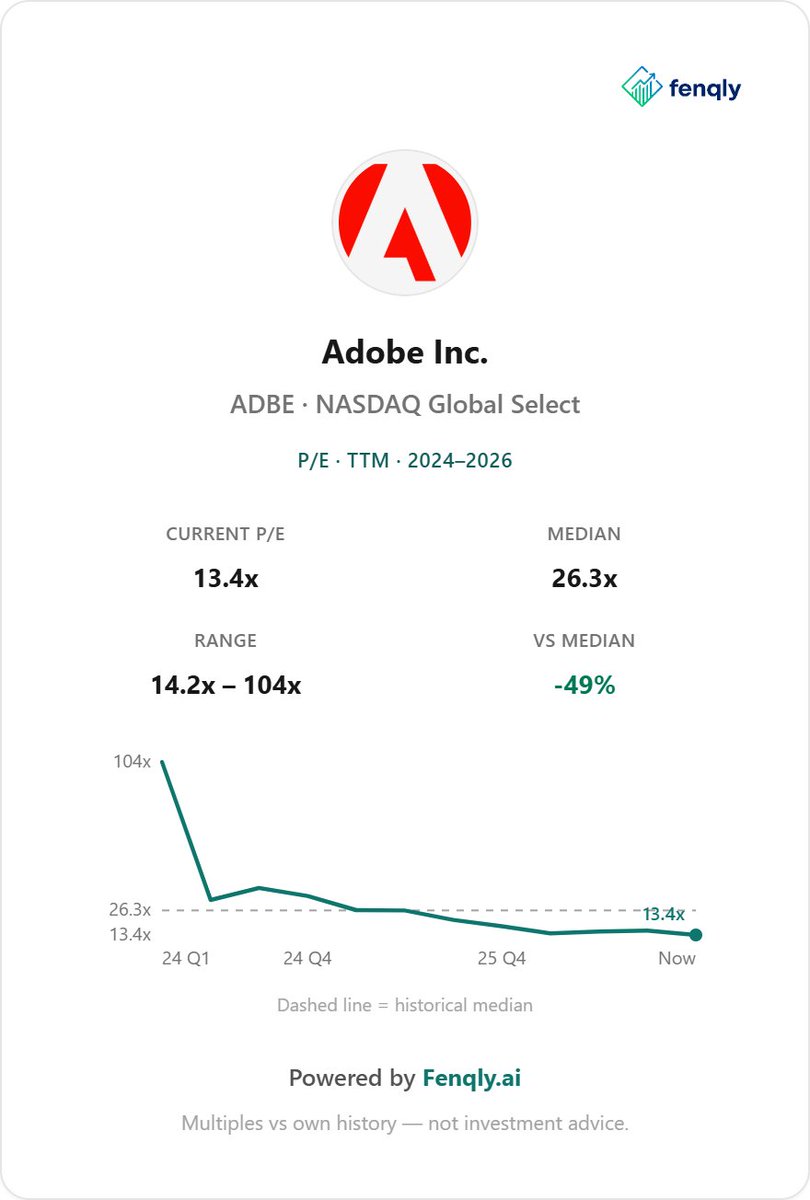
@FindleysFinance the map says they're in. the stock says the market isn't sure. $ADBE is half its own p/e median and still prints about a 12% fcf yield. so are the credits new money, or a feature people already pay for?
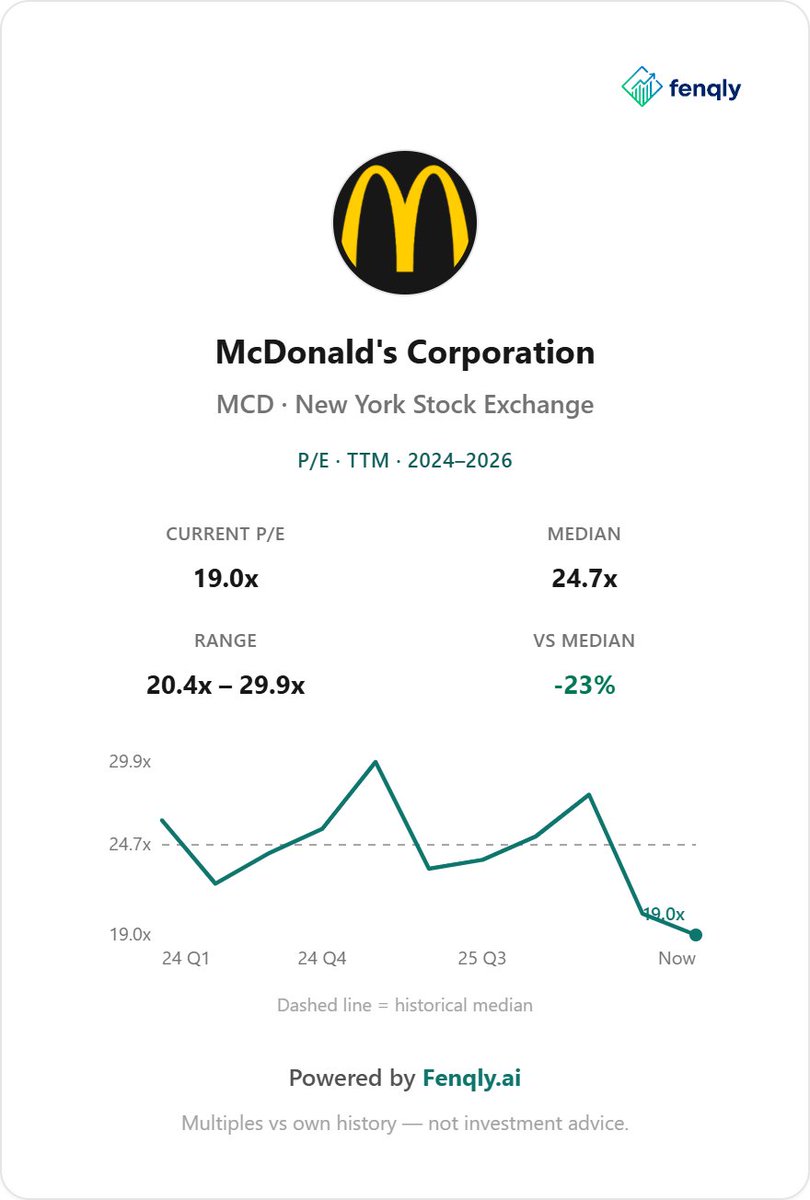
@ariaradnia the tape is flat. the multiple isn't. $MCD slipped under its own p/e range while the cash still prints. so this damn is a derating, not a dead burger.
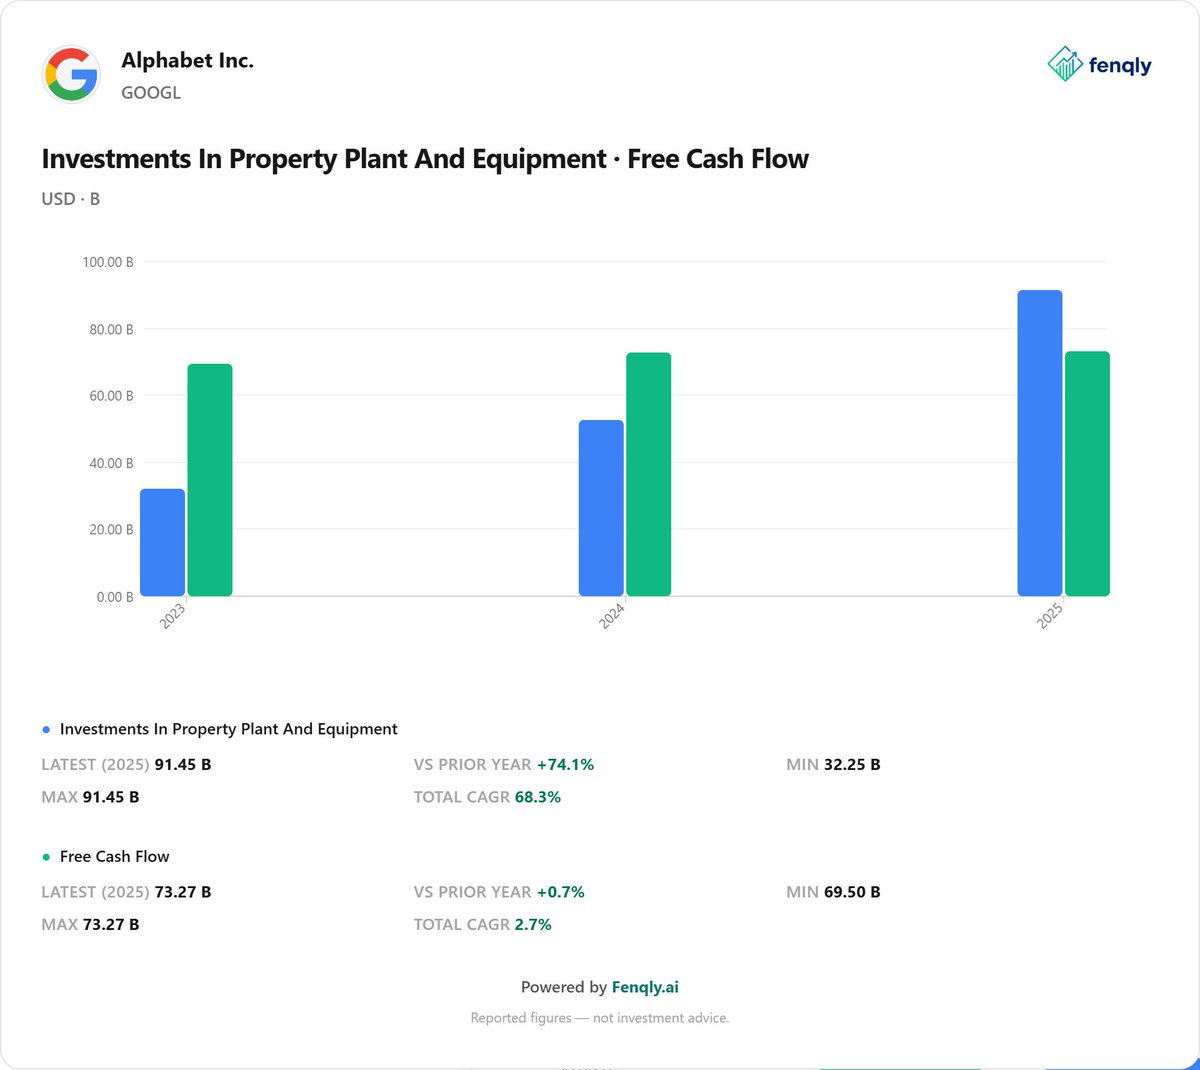
wild stack. the $GOOGL bar is the one though. capex already went vertical and fcf didn't come with it. that's the question under a 5% 10 year. can the cash engine fund the next doubling.
https://t.co/iItwBI1NU1
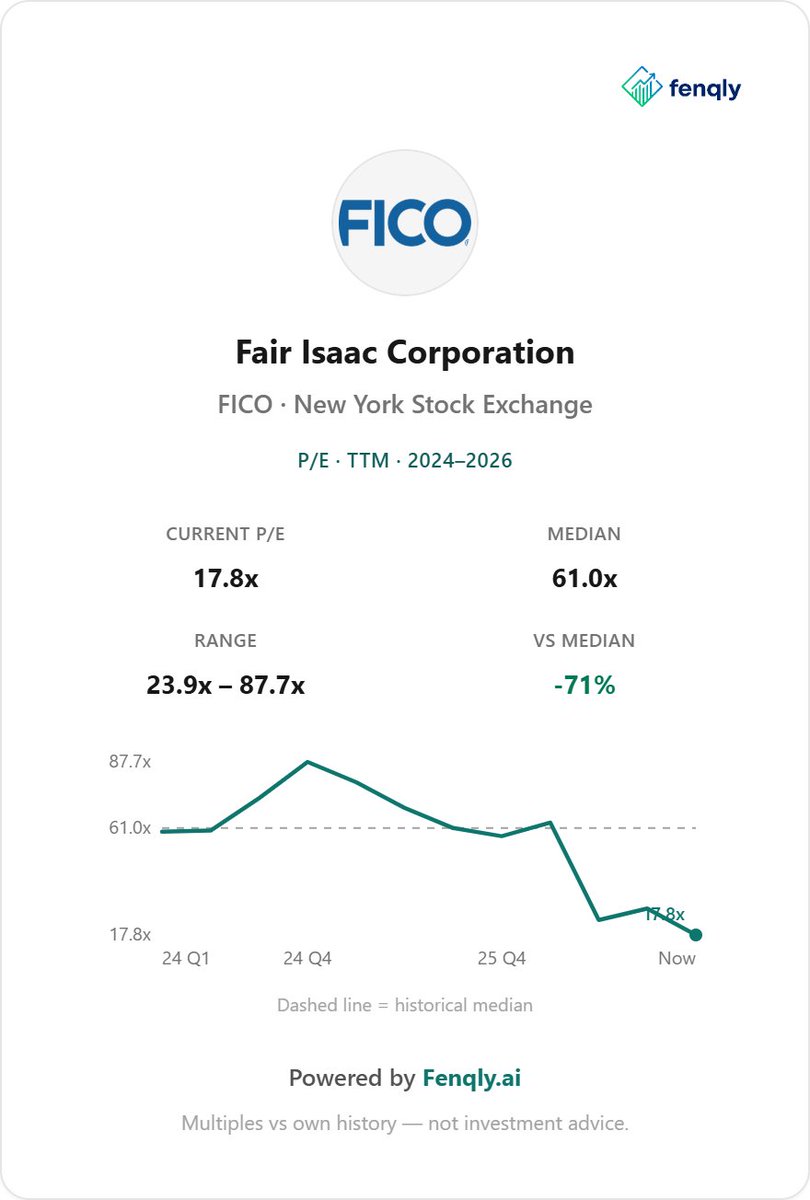
@Mindset4Money_X pretty cheap vs itself, yeah. the p&l didn't break though. last quarter still grew mid 20s with fat margins. so the 13x is you underwriting whether lenders still have to pull fico now that vantagescore sits on the same grid.
https://t.co/iItwBI1NU1
Buying PayPal’s moat at 9x Free Cash Flow is not a standard acquisition, it is pure highway robbery.
While everyone is drooling over the $340B Meta just added on AI hype, the real beauty here is the sheer asymmetry of the trade. The market has spent years treating PayPal like a melting ice cube, completely ignoring that it remains a cash generating machine with a double sided network effect that would take decades and tens of billions to build from scratch.
From a capital allocation standpoint, Zuck pulling this off would be a textbook move. He would be trading a high valuation currency like Meta stock riding the Muse euphoria for a boring, highly profitable asset at a ridiculously depressed price. Pure value arbitrage.
The obvious question is why buy the cow for $60B when Stripe and card networks will sell you the milk for a tiny fee.
Usually, massive tech mergers are value destroyers powered by executive hubris. But here, the math changes everything. At $75 a share, the margin of safety is so wide that the downside is virtually backstopped by the raw cash flow PayPal pumps out every single year.
If AI agents are actually going to execute the entire commerce loop from start to finish, Meta cannot rely on rented infrastructure. They need to own the checkout layer, the fraud engine, and established consumer trust.
Getting that scale of infrastructure at a single digit cash flow multiple to close the loop on AI commerce is a steal. I would do this deal tomorrow.
$META is ripping into connect and you still didn't pay a 2021 multiple.
the 40% from the lows was the business catching up. this week's fight isn't p/e. it's whether muse is a product or an app store spike.
https://t.co/iItwBI1g4t
@Mindset4Money_X yeah even after today. $META ran 40% and you still didn't pay a 2021 multiple. the 40% was the business catching up. connect this week is the real argument, whether muse is a product or an app store spike.
https://t.co/iItwBI1g4t
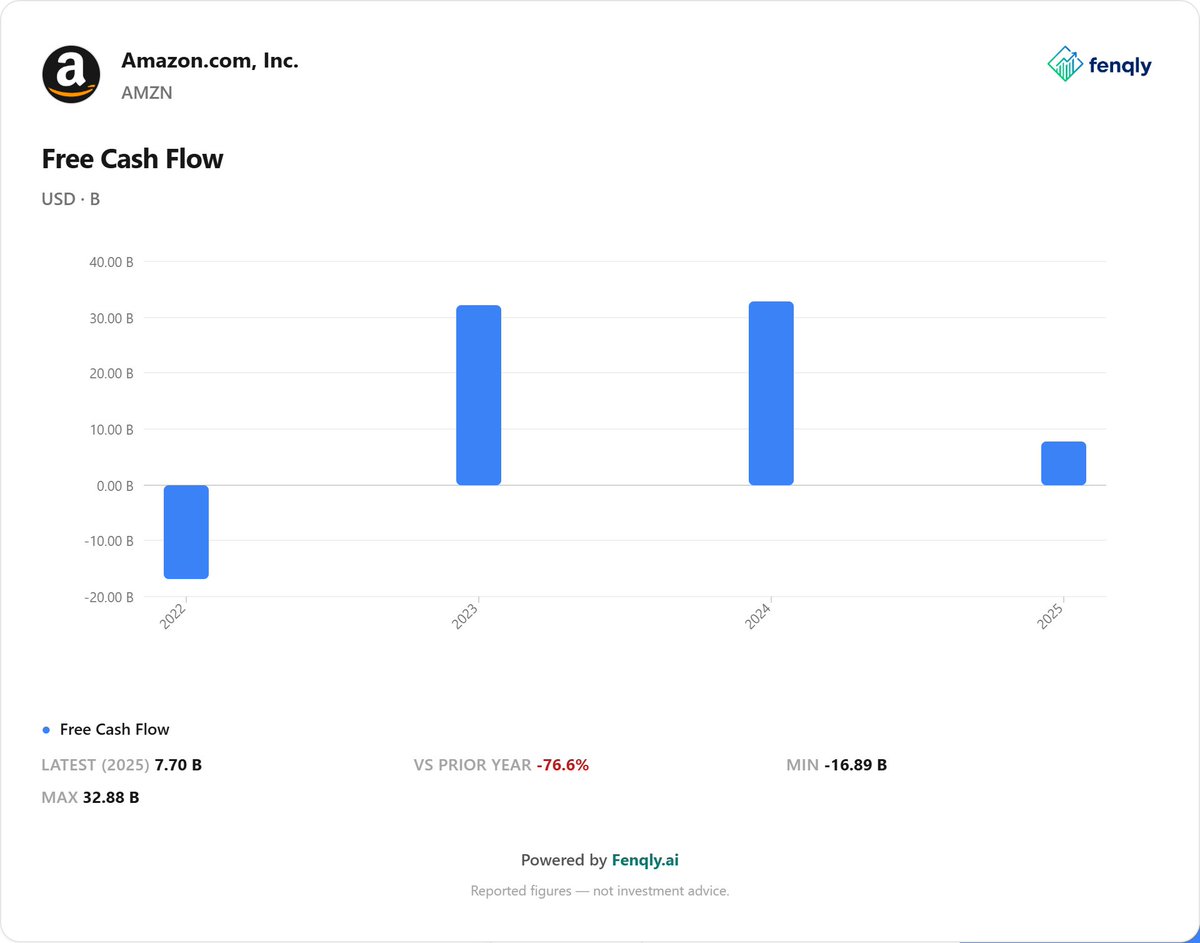
@FinanceJack44 $AMZN earned the 20%, no argument. the interesting bit is they can stay on this list and still not throw off cash. ocf is huge and capex ate it. so sales compounding is the easy part. the spend is the actual debate.
https://t.co/iItwBI1g4t
@FindleysFinance the 10% ocf isn't the hard part, they've been compounding around that. wild bit is your 12x exit is already above where it trades. fenqly has p/ocf under 9. so the 46% is just "please stop treating adobe like dying software"
https://t.co/iItwBI1g4t
Beating 37/40 is the easy consistency. $V and $MA if you want the operating kind.
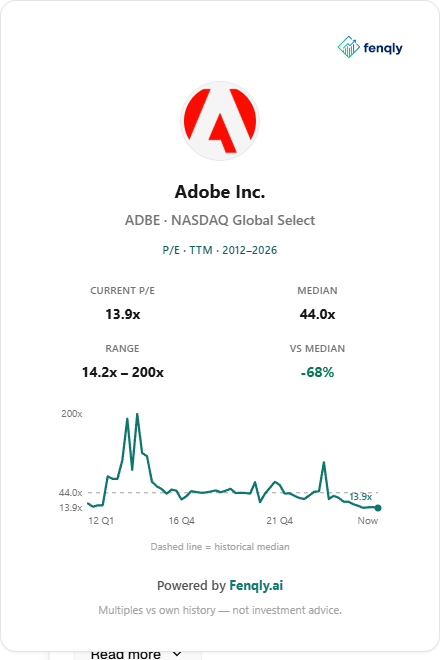
On $ADBE the interesting part is the multiple. 14x earnings vs a 44x historical median. FCF yield is ~11%. Down 26% YTD. The market isn’t arguing about beats. It’s arguing about whether slower ARR deserves this rerating.
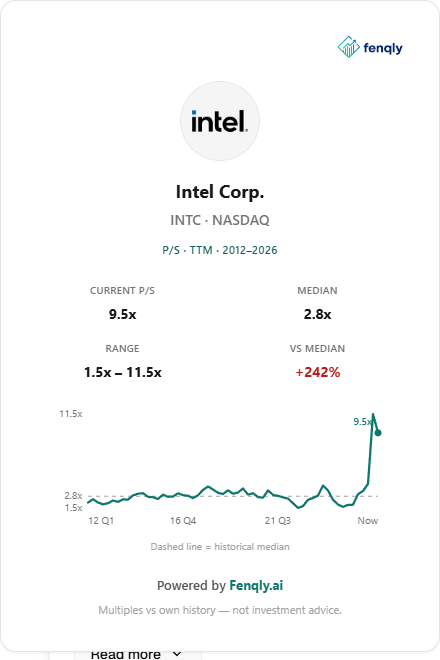
Intel is up ~180% this year.
P/S is 9.5x vs a 2.8x historical median. That’s +242% vs its own history.
It still lost $11B over the last twelve months. Revenue is below 2022.
The stock is pricing a new company. The filings still look like the old one.
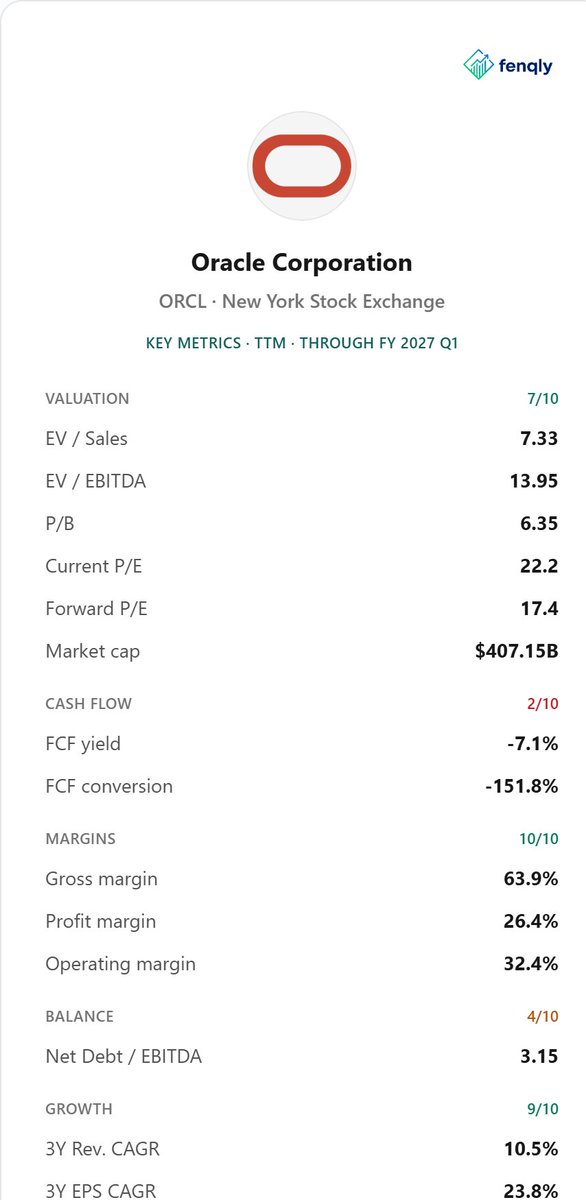
oracle's getting cut up again and they're doing another layoff round.
headcount is already 141k vs 162k last year. ttm: ocf $47b, capex $76b, fcf -$29b. net debt $120b (3.2x ebitda).
$664b backlog. the bill showed up. $ORCL
https://t.co/iItwBI1g4t
The intraday market is completely overthinking this rotation. It is way too much of a coincidence that the sudden push for an AI pause aligns exactly with the tech race against China and very real physical bottlenecks in data center capacity. Companies are piling on debt, issuing bonds, and diluting capital at an unsustainable rate just to keep up. This entire deescalation narrative feels like a calculated bluff to slow China down with red tape while giving the US tech sector the perfect excuse to quietly throttle back its massive CapEx spending. $GOOG $META $MSFT
As usual, the intraday market is completely overthinking the rotation. It is way too much of a coincidence that this sudden push for an AI pause aligns exactly with the tech race against China and very real physical bottlenecks in data center capacity. Companies are piling on debt, issuing bonds, and diluting capital at an entirely unsustainable rate just to keep up. Honestly, this whole deescalation narrative feels like a calculated bluff and a convenient way to slow China down with red tape and regulations while giving the US tech sector the perfect excuse to quietly throttle back its massive CapEx spending.
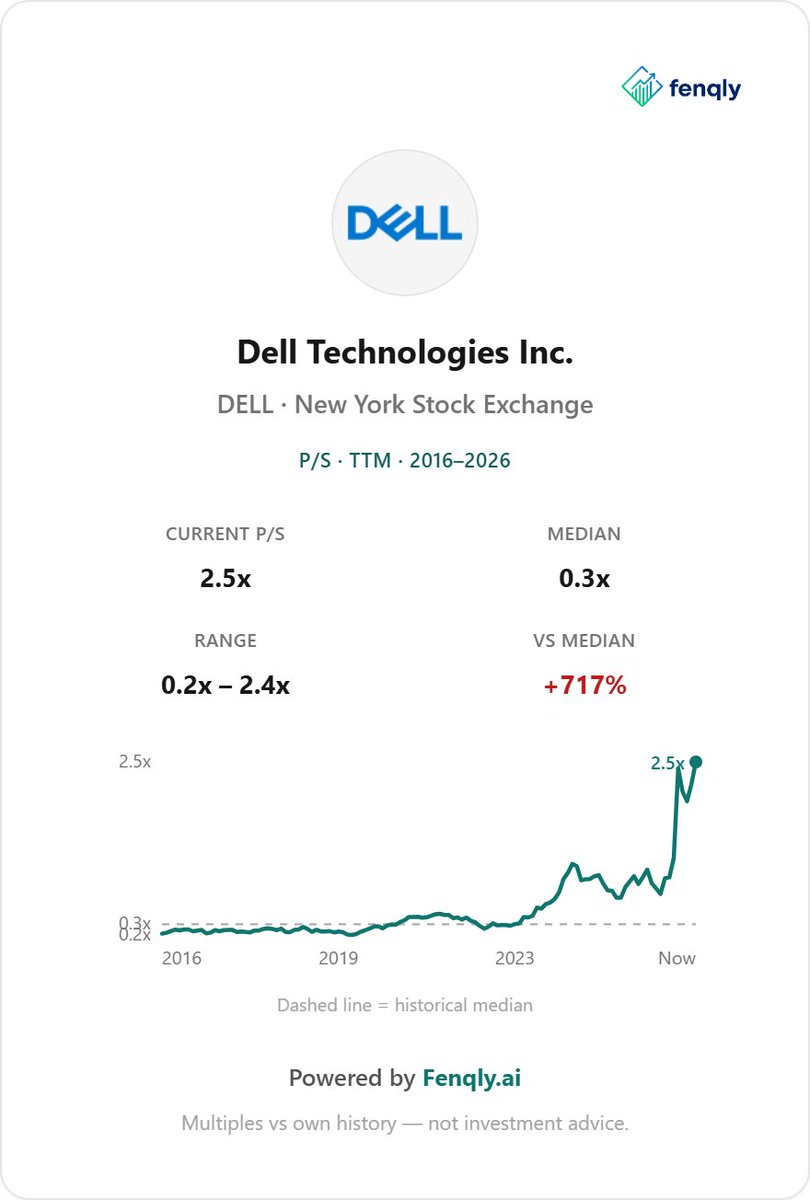
$61b of ai server orders. $47b of sales. one $DELL quarter.
friday +12% to $567. 2.5x sales vs 0.3x own median. $95b backlog.
orders or the multiple. which one are you buying?
https://t.co/iItwBI1g4t
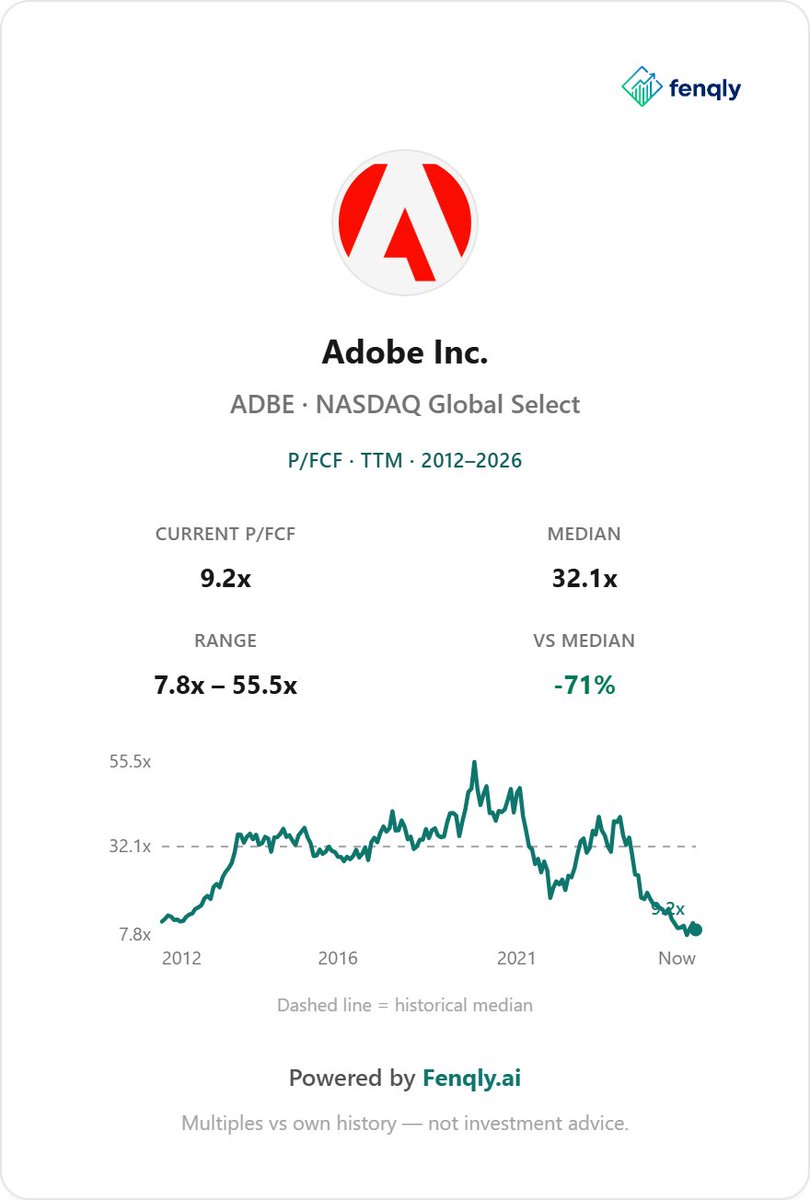
a $100b software company is 9x fcf.
$ADBE. 11% yield. $2.2b of buybacks last quarter. 3.9x sales vs 9.8x own median.
395m shares left. they used to have 481m.
name a software name you'd rather own.
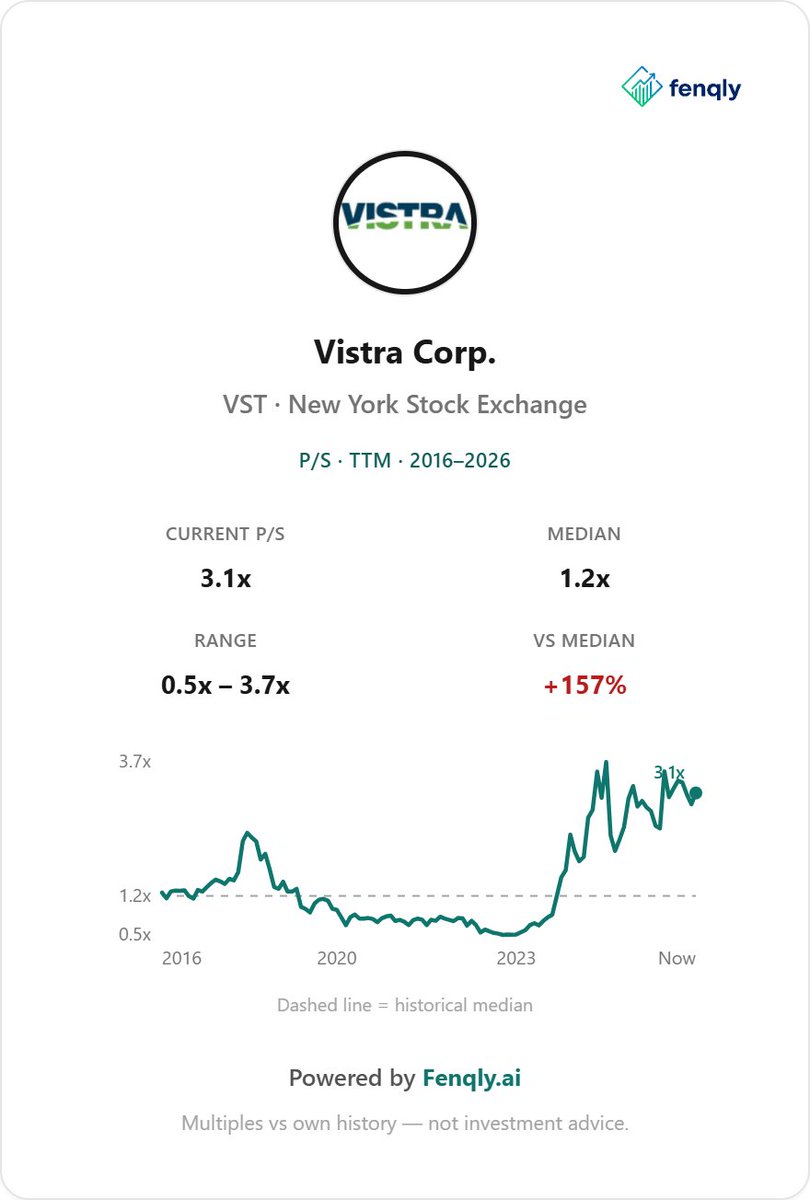
@MsVeilMoney down 30% from ath. $VST is still 3.1x sales vs 1.2x own median.
that's 2.5x its own history. 36x fcf. 2.8% yield. 0.9% roic.
cheaper than pelosi. not cheaper than itself.
https://t.co/iItwBI1g4t