One of my take-aways is: central bank independence is not only about legislative de jure power but also public and political attitude towards inflation affect the de facto power of central banks to effectively tame inflation - particularly at an early stage.
It is often said that only few have experienced high inflation in their professional lives. True! But luckily we can read about it. Here are two reflections by Arthur Burns in 1979 (https://t.co/i7JWCVbwCg) and Paul Volcker in 1990 (https://t.co/LGaPmi8uLR).
Eleven years later Paul Volcker talks about: The Triumph of Central Banks? Interestingly he emphasizes the shifting tide in public and political opinion such that "central banks began to have a stronger platform for effective action".
@bodhi_75 Or when it comes to recession signals (which was the original post): for sure dampening effect on real economy from current real rates level but pricing does not reflect boom-bust cycle which would go hand in hand with Fed slashing rates into accommodative terrain again.
For #EUR curves this is indeed the case as real #yield curves still have a positive slope, which last week's #ECB meeting has narrowed quite a bit though. For #USD curves, however, also real yield #curves are heavily #inverted. And, surprise, the ILS curve is actually quite flat.
@bodhi_75 I guess it tells us (1) inflation pricing is rather optimistic (1YF1Y ILS is at 2.4%) and that (2) the Fed's current stance is above r-star (in your lingo 😄). Put differently: pricing is seen as sufficiently restrictive to bring inflation back followed by lower rates thereafter.
@PatrickKrizan@AndreasSteno@pietphc That's a market which was too much looking across the Atlantic (#Fed#pivot) and now being caught on the wrong foot by #ecb pushing the terminal rate discussion/uncertainty wide open when net supply won't be of help. Agree that's a toxic mix which needs to be managed with care.
"The Governing Council decided to raise interest rates today, and expects to raise them SIGNIFICANTLY further, because inflation remains FAR TOO HIGH and is projected to stay above the target for TOO LONG."
50 bp up, as expected, but the wording couldn't be much more hawkish.
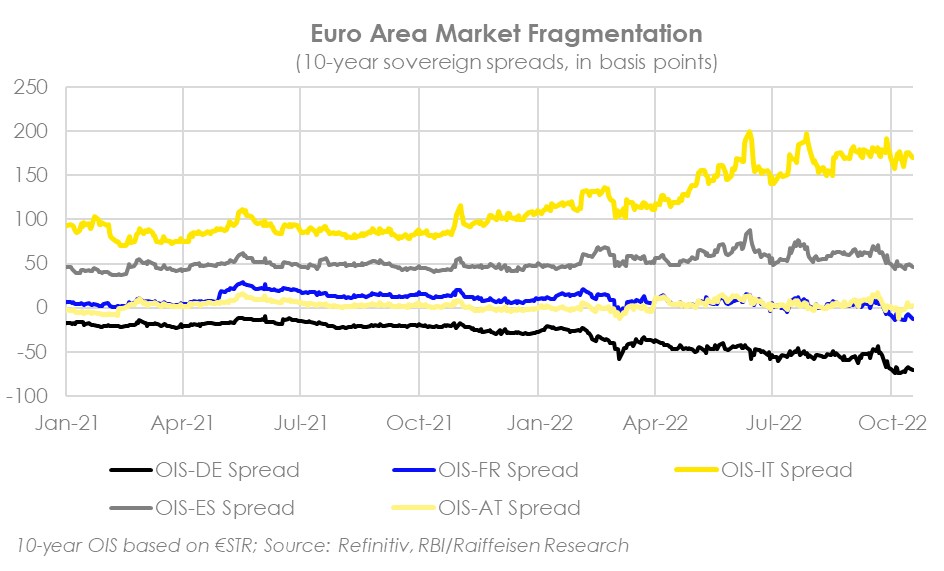
@bodhi_75@S_Bruckbauer@brezinschek 1) Zins-Unsicherheit spürt man wohl vor allem im Swap relativ zum Bund. 2) EZB-Bilanz-Unsicherheit: stärkere Differenzierung entlang der Ratingklassen (IT). 3) Bei ähnlichem Rating ist wohl für AT (vs FR) geringere Liquidität und die CEE(Russland)-Nähe anzuführen. #mytwocents
Nice way to put it 😄
On Burns I recommend reading @delong's 'Americas Peacetime Inflation' (https://t.co/adtM69khf9). Nixon -> Burns: "I know there's the myth of the autonomous Fed ... [short laugh]" says it all!
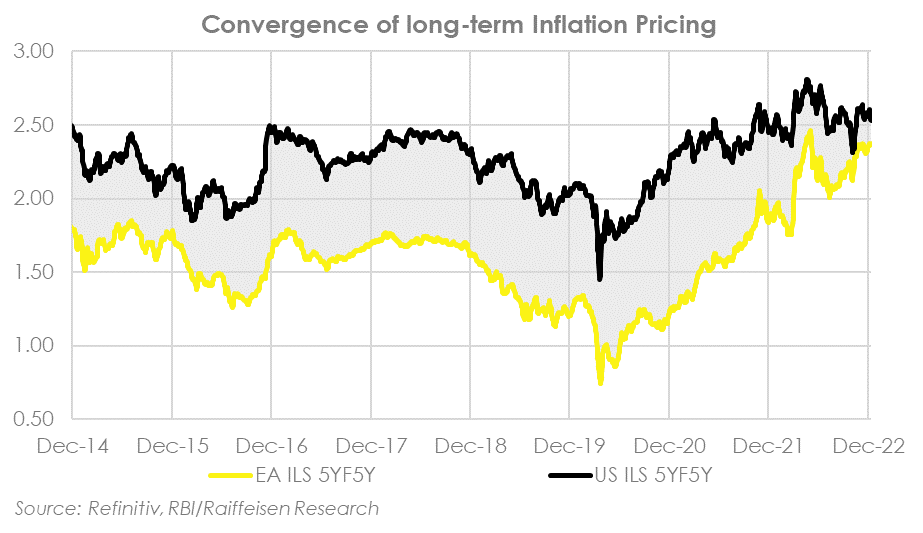
Long-term #inflation pricing almost converged with EA silently moving up. Distinction between US/EA inflation narrative got cracks. #Powell's presser today should be rather comfortable compared to what is waiting for #Largarde tomorrow. Still, better to converge to 2.5 than 3.5%.
Enough is enough! Testing CBs' hawkishness has not been in vogue in Q4. US core inflation easing + key rates in proximity to pricing puts #Fed closer to 'Job Done' than #ECB which has 150bp more 'To Do' and needs to w(t)alk a narrow path on #QT.
(chart idea: @SvendsenAnders)
Enough is enough! Testing CBs' hawkishness has not been in vogue in Q4. US core inflation easing + key rates in proximity to pricing puts #Fed closer to 'Job Done' than #ECB which has 150bp more 'To Do' and needs to w(t)alk a narrow path on #QT.
(chart idea: @SvendsenAnders)
Fears of high #inflation triggering upward trending #expectations has become a main motive for #centralbanks. It's about avoiding the #70s when long-term expectations quadrupled and it took twice as long to bring them back with significantly higher #realrates along the way.
@bodhi_75@S_Bruckbauer@LukasSustala Prinzipiell kann ich dem Thema von Checks-and-Balances zwischen Finanzmarkt und Politik schon etwas abgewinnen (sicher besser mit als ohne), aber man darf sich nicht NUR darauf stützen und muss für den Fall der Übertreibung Flexibilität und Innovationskraft unter Beweis stellen.
@S_Bruckbauer@bodhi_75@LukasSustala Ich denke die Frage angemessener Risikoprämien in der Eurozone ist selbst analytisch keine einfache, hat aber auch eine politische Dimension. Es war wohl letzteres, was die EZB auf der letzten regulären Sitzung dazu veranlasste sich diesem Thema zu wenig zu widmen.
Above consensus expectations but not at all unexpected!?! The #Fed hiked by historic 75 bps today with some short-term pre-alignment after #inflation surprised last Friday, it seems. "Expeditiously to neutral" is the new slogan, with one voice of dissent.
https://t.co/3QrRRyASRF
With the start of #QuantitativeTightening this week the @NYFedResearch has kicked of the discussion on how to think about an #AmpleReserveRegime:
Scarce, Abundant, or Ample?
https://t.co/AL2sQUhJUo
At least for me, this was an insightful read and I borrowed some stylized facts.
@bodhi_75 Interesting point that he traces back global inflation, including that stemming from commodity prices, to spillovers from the US economy overheating.