Great piece by
"Is venture capital an investment management business or a “make-big-numbers-go-bigger” business? Invested capital is a cost. A company that has raised $1B and is valued at $1B has created zero value. Treating capital raised as a proxy for value created is like judging a startup by its burn rate. And treating either as a proxy for venture returns (or the likelihood thereof) is just bad math. Just look at the graveyard of startups overcapitalized at the height of ZIRP. Webvan, WeWork, Bird, Katerra, and Bench created significant value for their users while they lasted — their investors, not so much.
None of this means technology doesn’t create value. It does, and venture capital is a big part of why. But more capital creating more value is a weak causal claim, and more capital creating more returns is weaker still."
https://t.co/SwVIGcHmng
BREAKING: Tech founders worth €100bn tell Europe to get its sh*t together
More than 40 European tech leaders demand urgent reforms during Slush conference
https://t.co/p8Vzglmor3
Exclusive video interview: https://t.co/fQSIQNJw30
One of the biggest questions about modern venture capital:
If late-stage venture is really an "access" game with obvious targets, why should anyone put their cash in a 10-year blind pool fund?
Why pay a GP 2–2.5% if they aren't doing meaningful work on sourcing or selection, when you can find a manager who will do discretionary deals for carry?
At some point, can't the company just run an SPV itself if it truly has sufficient inbound interest? Eliminate all fee drag in return for a lower cost of capital.
Like any vehicle, SPVs have seen some abuse (fools chasing heat), but overall their proliferation is a very positive development for venture capital.
Appreciate a legend like @TimDraper calling this out.
From the time I started @iaventures 17 years ago I’ve been saying the same thing to LPs: talent and opportunity is more widely distributed than you think.
Smaller firms are well-suited to take advantage of this phenomenon because of the impact a single big winner can have on the portfolio, especially with concentrated ownership.
From IA to @gamechangersvc the vision is the same: to enable builders everywhere, whether from the dense pots of traditional founder markets or not, with the boldest visions to have the opportunity to win.
almost all of my VC friends agree that venture investing is too crowded, that the returns are getting competed away
almost all of my founder friends agree that the only reliable sources of funding for risky early ideas are rich people who angel invest as a hobby and accelerators like YC -- many of whom repeatably earn returns vastly greater than venture firms
it'd be one thing if everyone acknowledged this gap and attributed it to, say, the downstream incentives of big funds earning big management fees
but most people who aren't founders genuinely seem surprised to learn that pre-seed capital is scarce
“Ultimately, what we’re doing is mistaking adoption for transformation. And the biggest gains will not be from making existing organizations more productive, but from designing new kinds of organizations that couldn't have existed before.”
@gdibner@edavidpeterson This is a great piece. We had the same thoughts in 2023/24 when we understood where AI is carrying us. 3 years and 3 new companies later, we think we got the handle on it! Back then, we called it venture equity, and I think we are onto something.
Great essay.
"Ultimately, what we’re doing is mistaking adoption for transformation. And the biggest gains will not be from making existing organizations more productive, but from designing new kinds of organizations that couldn't have existed before."
The Israeli business Nvidia bought for $6.9 billion now generates $21 billion a quarter.
Nvidia's networking division, built around its 2019 acquisition of Mellanox, generated more than three times the purchase price in a single quarter.
https://t.co/NDuV8OZtCP
Further evidence that this is 2008, not 1999
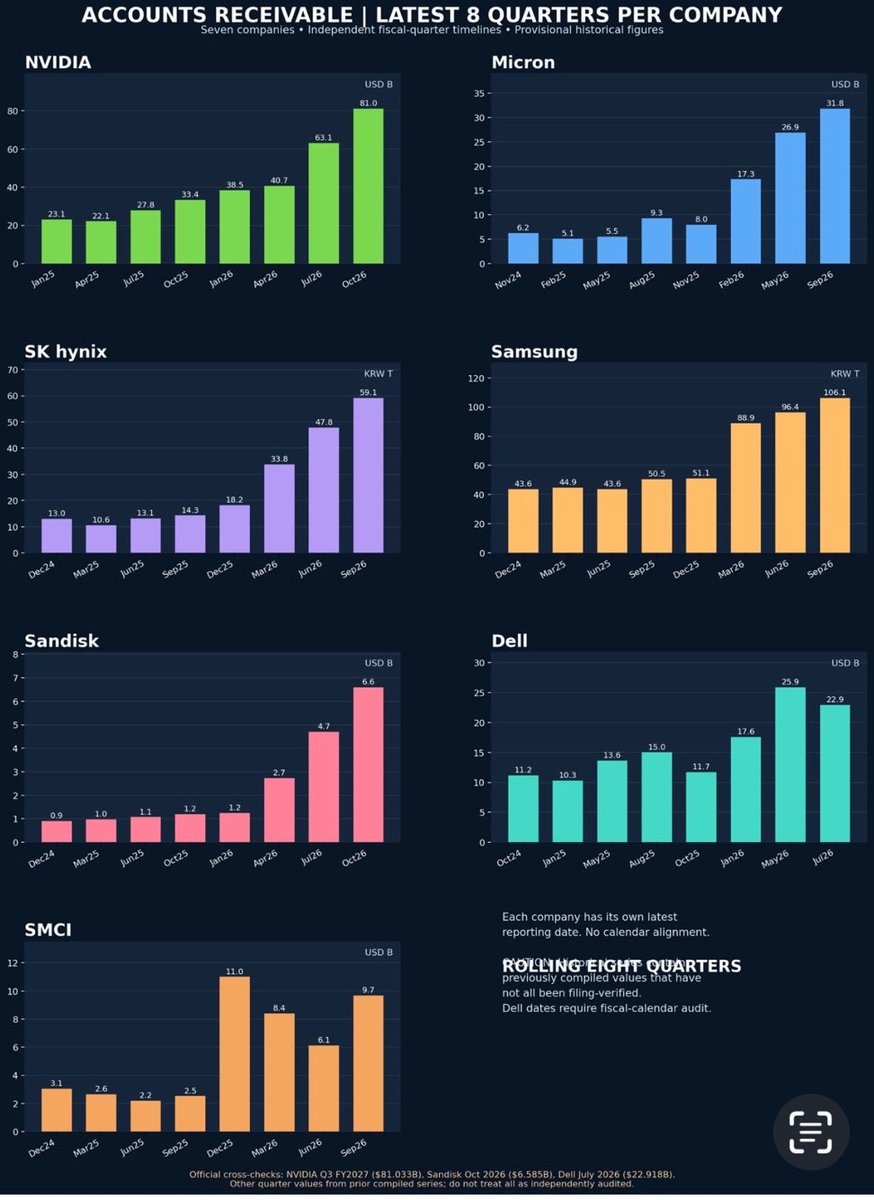
Seeing AR balances rise this much, this fast is unprecedented. That reflects hundreds of of billions of revenue that has not been paid, largely to customers that have been propped up by generous financing terms and ample credit/venture markets. This becomes the proxy for leverage from the base of the pyramid and now even the most profitable players in the value chain (semis) need to start tightening their payment terms or risk running out of cash.
Now that capital spigot is shutting down - across nvidia, credit markets and eventually in VC. As that happens, you see massive mark downs on debt/AR (already happening) and every player in the value chain goes into capital preservation mode. Capital throughput draws to a halt and growth doesn’t just slow…top line falls off a cliff. This is why semis are so cyclical, because their earnings look particularly strong in periods where demand outstrips supply, but they tend to overdevelop / overextend at the tail end of those cycles, and utilization / pricing / profitably fall dramatically when customers can no longer afford more chips and you can no longer afford to extend them more credit.
I have historically underrated the importance of capital markets in cycles and it’s increasingly clear that the money supply of the AI trade is seeing a lot of pressure. If I learned one thing in 2008, it’s that changes of liquidity happen much faster and much more dramatically than changes to the economy. The market collapse in 2008 was so incredibly fast that it’s truly hard to comprehend for those that didn’t experience it. Today’s market has far more leverage on longer duration with less transactability on a global scale (likely no government bailout), meaning if we see a liquidity crunch, it could come very hard and fast.
Hopeful this doesn’t happen, but these AR balances are looking more and more like mortgage delinquency rates back in 2008.
i've had convos recently with a few of my founders who are in process with "tier 1" funds for their rounds (post ~2nd meeting) and are getting cold feet about proceeding because of reasons like: "the terms of the (potential) deal are bad", "we don't like the partners/not a good fit for us)" etc. i've given all of them the same pointers:
> you don't have an offer yet (and esp with a tier 1, there is a very big gap between the 2nd meeting and the offer, your most likely outcome at this stage is still that they pass) so don't waste your time hypothesizing. always better to get the offer and then say no (so heads down, and bring them over the line)
> a singular term sheet begets more term sheets (if you run a good process). a first TS is a seminal moment in your raise, you're not obligated to take it, and it will make your life way easier in getting more offers (as VCs now have external time pressure to act). if you haven't gotten a term sheet yet, just focus on getting (a decent) one from whoever (if it's from a tier 1, even better).
> to double down on the last point, we're in a hyper-consensus era where *almost* every other VC wants to co-invest or do a deal a "tier 1" wants to do (and they are willing to pay a lot for it, look no further than the cuck tranche). even if you don't like the deal a given tier 1 might offer you, merely having it on the table will give you so much leverage with other VCs that you will likely get an offer from someone else you do actually like. the power pendulum fully swings to you here, which is the position you strive to be in whenever you're fundraising
@guilleflorvs@shelgesson is one of the wisest and kindest VCs I know. And his litmus test ("would I work for this person?") is one I've applied myself. It's a very good one.
Absolutely fantastic piece by my partner @edavidpeterson. I'm biased, but I think it's a must read.
"The search for the AI-native firm"
https://t.co/CYE4pEC0JU