Buyer short of your seller's number, or a seller who won't budge? A structured installment sale can help your seller net more and help your deal close. Needs a gain, usually $300,000+, set up before closing.
Comment DEAL with the address and I'll send a one-page look at the numbers.
Education, not tax advice.
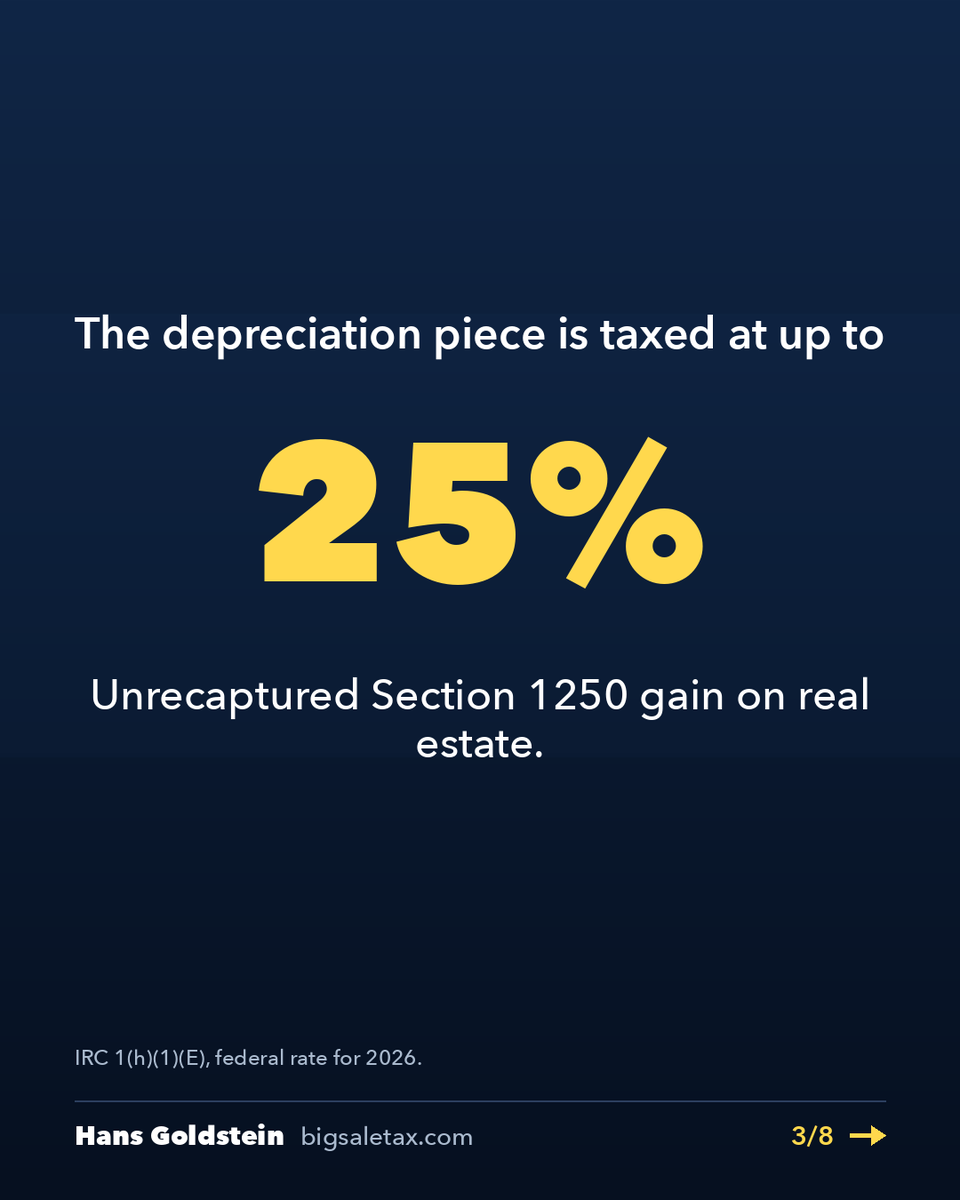
@JakeLatimer26 Exactly. Worth noting 453(i) only pulls ordinary recapture forward; unrecaptured 1250 gain (25% max) still follows the payments, taken first.
Cost segregation is a real benefit with a bill attached at the far end.
The study pulls deductions forward. Good. Worth doing.
At sale, those same components come back as ordinary income.
That piece is taxed in the sale year. It cannot be spread over an installment note.
The study did not remove the liability. It moved it and changed its character.
Does your cost seg provider model the recapture at exit, or stop at the deduction?
Reply LOSSES and I'll send the depreciation and losses worksheet guide. Full breakdown in the reply.
Education only, not tax advice.
@cpapracadvisor Tax Pro Account is worth setting up before filing season. Clients can authorize 2848 and 8821 requests online instead of you faxing them to CAF.
@srarock Monthly reports are also where you catch basis problems early. Shareholder basis and at-risk limits are far easier to fix in October than at the K-1 stage.
@Watsonuscpajp A below-market sale to a child is part gift, so a 709 may be due. The child's basis is the greater of price paid or the parents' adjusted basis.
@JohnAcostaRE Consolidation works best when the closings line up. With several relinquished properties, the 45 and 180 day clocks generally start at the first closing, so a later sale can leave very little runway to land the one replacement.
The 15% capital gains band is only about $600K wide for a married couple. Take a $5M gain in one year and most of it lands above that line at 20%. Spread it with a Structured Installment Sale and every year gets its own 15% band to fill.
@gwiesefarms Fair point on equity outpacing cash flow. One catch: 1031 only defers the gain, and any boot, like cash out or debt relief not replaced, can be taxable. Farm equipment in the deal is also Sec. 1245 ordinary income.
@steveconaway1 Multi-parcel auctions are where this matters most. Is it mostly a cost thing, or do brokers worry that parcel-level soil and tract data invites buyers to cherry-pick?
The same $100,000 capital loss carryforward saved $23,800 against one cash year and $9,165 against ten $100,000 payments (model run, 2026 law).
Spread too thin, it cancels gain that would have been taxed at 0%. It is also lost at death, so plan when it gets used.
Reply LOSSES and I'll send the Form 8582 worksheet guide.
Education, not tax advice.
@Unapologetic_Q Borrowing isn't a sale, agreed, but the loan is secured by the stock. A sharp drawdown can bring a collateral call, and a forced sale realizes the gain on the lender's timeline instead of his.
The most expensive dollar in America is the one that pushes your income past $250K. It doesn't just tax that dollar more; it adds 3.8% NIIT to your entire investment gain. Fifteen percent quietly becomes 18.8%.
@RiverstoneLand Creek frontage plus a pond on 45 acres near Giddings is a nice combo. Are buyers there mostly weekend-place folks from Houston and Austin, or still local ag?
On an installment note, the expensive dollars come first.
Reply LOSSES and I'll send the Form 8582 worksheet guide. Full breakdown in the reply.
Education, not tax advice.