Mark Zuckerberg’s core philosophy explained.
Wang argues that Zuckerberg’s approach to risk and failure removes the hesitation that slows most companies down.
> Failure doesn’t matter. What matters is when you win - and how big you win.
> In a world that’s constantly changing, the biggest risk is not taking any.
Both ideas make inaction feel more dangerous than a wrong move.
My conversation with @alexandr_wang, chief AI officer of Meta.
0:00 The vision behind Muse
1:32 Discovering the potential of personal AI agents
3:34 Three years of therapy in one AI session
5:46 Building Muse in 7 months
9:16 Why Meta bet on personal AI
16:51 Mark Zuckerberg's obsession with improving products
20:15 How Meta knew Muse was ready to launch
23:32 Why great products need a single point of view
25:56 Making Meta cool again with memes
34:38 Building trust with AI agents
38:43 The future of human ambition
45:22 The call from Mark Zuckerberg that changed everything
52:13 Leaving Scale AI for Meta
55:19 Rebuilding Meta's AI lab from scratch
58:13 From founder to coach
1:05:55 The future billionaires at Alexandr's 19th birthday party
1:08:04 Diamond mining vs. building skyscrapers
1:09:21 Why Alexandr has more than 200 direct reports
Includes paid partnerships.
Mark Zuckerberg and Alexander Wang on deploying capital for AI spend:
Alexander: "you have to make very large investments or make very big decisions about how you're going to invest or develop the technology, you know, what decisions you're going to make long before there's proof points around."
Mark: "We have these conversations where it's like at the end of last year, we're like, alright, we are quite excited about the progress. We haven't seen the models yet. We're gonna write this check for like, I don't know, like $100 billion or $200 billion like, Alex, are you sure this is gonna work?"
Alexander: "Although it's like the joke, every time we talk about, we hope it's all gonna work and be good."
Spend or get left behind - the spending race in AI
Via @cheekypint on Youtube
$MSFT $META $GOOGL $META $AMZN
Mark: We're gonna write this check for like, I don't know, like $100 billion or $200 billion like, Alex, are you sure this is gonna work?
Lmfao, what even
Mark's trust on Alex's judgement is indeed top tier
introducing muse wonder
our new frontier model. state-of-the-art at personal agents and professional agents.
our largest and most capable model yet—rivals the big bois
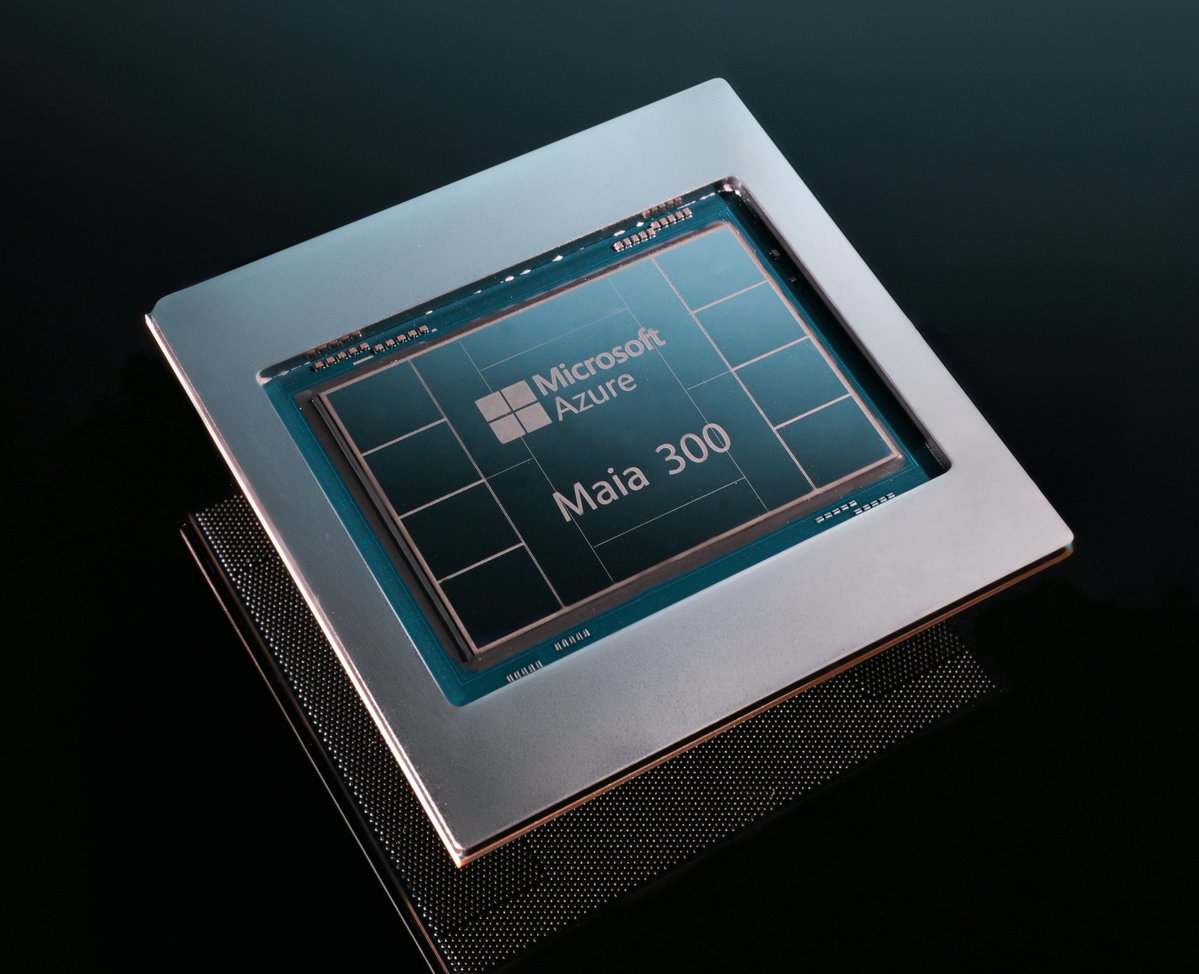
Today we are announcing our biggest bet yet on our own silicon.
Starting next calendar year, we will scale our Maia family to multi-gigawatt deployments, making it the primary inference system for our own product and services.
And we’re introducing Maia 300, which delivers 40% more tokens per watt compared to leading GPU-based systems.
We are already deploying Maia 200 across the US, Europe, and Australia, delivering up to 1.7x more tokens per watt across experiences in Teams and Copilot.
Our goal is to build on the full-stack efficiency gains we’ve already seen, while continuing to bring the latest innovations from across the ecosystem into our fleet.
August was my last month at @huddle01com.
For nearly six years I was the only product designer there, working on everything from fundraising pitch decks to mobile apps, dashboards, websites and the brand. What a blessing it was.
Thank you to @ranjan3118, @Susmit_Lavania, and a team that was generous, smart and fun to build with.
Now contracting with two companies, with room for one more contract project. If you're building something, I'd love to hear about it.
p.s. My design work has its own home now. Small tools, design resources, and the odd, chaotic stuff, all at @pixelyokai.
Peter Thiel on why extreme views lead to laziness.
Thiel argues that extreme optimism and extreme pessimism produce the same result: laziness.
> Extreme pessimists believe nothing can be done, so effort feels pointless.
> Extreme optimists assume the future will arrive on its own, so nothing needs to be done.
Both mindsets remove the incentive to act.
For founders and anyone trying to build something: belief in a better future is useful only when it still requires effort.
Technical moats are mostly over at this point. If you’re building something that is meant to be durable, the only moats now are:
• Proprietary data
• Network effects
• A physical component
Inference is the second way to raise a massive round right now. After the labs, you can still justify massive rounds by pointing at data centers and compute, which means more inference companies keep getting funded even as the underlying product stays extremely easy to switch away from. On the flip side, many neolabs are also renting out their own compute, adding yet another source of supply into the same market.
Companies that tried to verticalize around batch workloads and post-training are now pivoting back to "pure inference" and joining the same undercutting cycle. The result is a permanent reverse auction: providers undercut each other over and over: half off Fireworks, half off Baseten, 10% cheaper GLM or Kimi—and every new entrant or neolab offering capacity just accelerates the cheaper pricing
At the same time, app companies have so much choice right now that they can bake off and compete prices down extremely hard. They move millions of run-rate spend overnight whenever a meaningfully cheaper option appears, because the technical switching cost is essentially "one line of code".
That combination: easy capital, extra compute from neolabs, low stickiness, and continuous price pressure makes inference one of the less defensible layers in the stack even as it continues to attract large valuations.
However, if you are a smart team of infra people, it is the easiest way to raise 100M seed after a neolab
Researchers: neolab <> engineers: inference
Assorted things I've been mulling over regarding agents in the economy:
• Companies are in some sense the original superintelligence. It's often the case that they can use their amortized cognitive surplus to advance their interests against those of certain consumers: relative to the optimization capacity of companies, consumers can be inattentive, underinformed, irrational, etc. (Think, say, of some of the classic insurance upsells at the end of a booking process, which is typically priced substantially above what a regular policy would cost.) Herbert Simon introduced the idea of bounded rationality, and firms often end up benefiting from it. Thanks to personal agents, we will probably get somewhat more rational in how we engage with companies.
• How exactly will outcomes change? Well, certain kinds of price discrimination will work less well (how do coupons work if every agent hunts fastidiously for them?), and certain kinds of customer cross-subsidy will change (today, people who forget to cancel subscriptions subsidize those who don't). Taken across the economy as a whole, I'm not sure what the incidence of all of this will be.
• In corporate strategy, people have long debated the relative importance of distribution and product quality. Perhaps you've made something better, but does anyone know about it? Won't people just continue to buy the ACME Corp Mousetraps? Personal agents will, I think, act as a kind of structural subsidy for product quality. How would markets look different if individuals always spent at least 10 hours researching their purchases? On the margin, focusing on making a product better is, I think, going to become a more effective strategy for companies. This is good!
• It true, a corollary is that information about product quality will become more important and impactful. Today, most people have very limited ability to aggregate and integrate such data, but agents will have insatiable thirst for such signals. (It's often said that data is becoming more valuable because it helps in the training of models. That's obviously true, but I think there's a secondary way in which it's more valuable simply as a complement to cheaper intelligence.)
• A big question is whether agents will increase superstar effects (rational agents all settle on the same product) or increase dispersion (because everyone has slightly different tastes and preferences, which agents are good at eliciting, finally overcoming the artificial clustering we've been subjected to).
• Many internet companies have monetized demand routing, which is in turn often predicated on short attention spans. "I'll click on the first thing I see." This has led to some amount of inefficiency, as companies try to propitiate capricious ranking algorithms and incur various placement fees. It's not all deadweight loss (willingness to pay is itself a kind of signal, which is valuable to buyers), but it's not great. How will the nature and value of this routing change in a world of personal agents? I don't know the answer, but I think that the effects might be pretty big.
• Much of what I'm writing hinges on the assumption that personal agents will be on the consumer's side. I suspect that that will be the winning strategy, but whether it's true, and what it means to be true, involves a lot of other questions.
Taken as a whole, the market is a massively parallelized, decentralized, and highly imperfect value attribution machine, and, taking stock of all of the effects, it seems to me that the quality point may well be the biggest: that agents will change the nature of the backpropagation such that the rewards for better products increase. Maybe this is too optimistic, but I suspect (and hope) that companies that make things that they're proud of will feel that the universe is a little more partisan in their favor.