Summarizing my year by writing about my favorite reads this year.
Top 5 books I read in 2020 that everybody can read
#book#readingcommunity#bestreads#Top5 https://t.co/n6uLavdElw
The older I get, the more I realize that showing up is the key to life.
It sounds so simple, but it's surprisingly rare. Because it's easy to do when you're getting patted on the back for it. It's easy when the rewards feel certain. It's easy when the progress is clear.
But most people stop when it's none of those things. Few have the courage to keep showing up through the valley.
So, if you want to win, just show up. Show up when it’s hard. Show up when no one’s watching. Show up when you don't feel like it. Show up when the rewards are uncertain.
Show up.
Never bet against the person who just keeps showing up.
$UBER $DASH $DHER
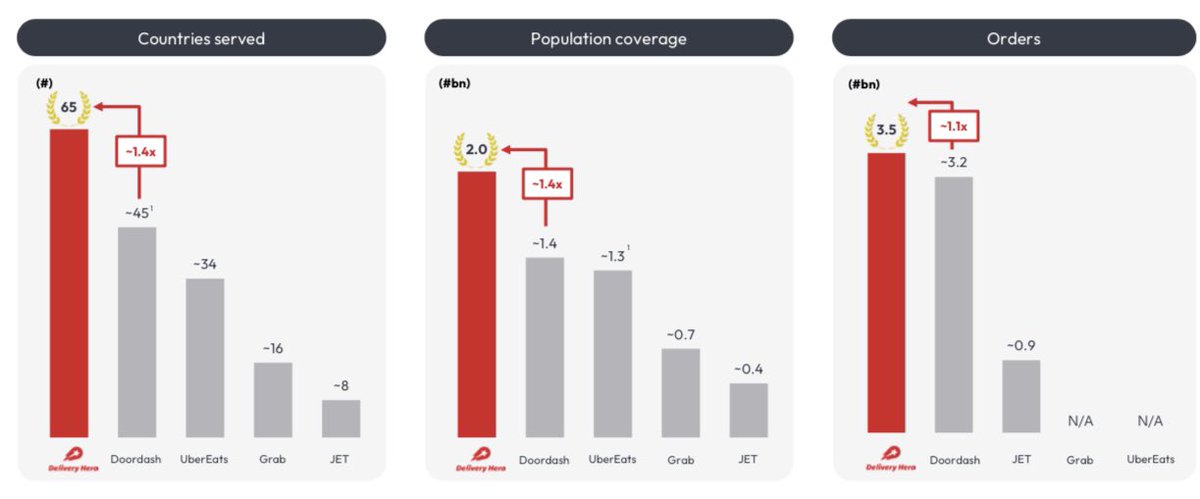
Uber has bid €33/share for Delivery Hero, already owns ~20% plus ~5% via options, and reports say it's weighing a raise. Now @t_xu is circling, reportedly interested in the Middle East business.
What you see is not what you get. In 2025, DHER ex-SBC margin was 1.4% vs UBER 1.6%, DASH 1.7%. Advertising revenue as % of GMV is 3% vs 1% DASH, 2% UBER.
Run the logistics at breakeven and DHER is the most profitable global food delivery business in the world. And the screen understates the real trajectory: before and after the 2026 investment year, group ex-Asia incremental margin is ~6-10% vs ~2% trailing, MENA & LatAm have been printing amazing numbers, Europe is inflecting. Asia's growth drag is reversing as the Coupang fight and FX roll off. EBITDA set to grow many multiples faster than GMV for a long time.
Bolt it onto DoorDash and they jump from $130B to $195B GMV. Bolt it onto Uber and they go from $110B to $175B - from #1 outside the US to bigger than DASH. Uber cross-sells DHER's 10M daily orders into rideshare, DoorDash cuts out cost.
If @dkhos pulls off this acquisition, he cements Uber's legacy as the defining global food delivery platform.
My fair value is €66 - double it up.
Sum-of-the-parts 👇
TALABAT
• 2027E: 13B GMV / 5.03B rev / 1.32B GP / 600M EBITDA / 450M FCF
• 650M net cash. Dominance unlike anything food delivery has seen
• Consensus is depressed while Meituan runs out of cash to expand.
→ 2x rev / 16.7x EBITDA is cheap = $10B
BAEMIN
• #1 in Korea, $20B GMV, $400M op profit in 2025
• Been grinding against $CPNG Eats, but returning to growth in 2026
→ $5.4B offer on the table from Naver and Uber (called it 😉)
PEDIDOSYA
• 80% market share. #1 in LatAm (ex-Brazil), >3x bigger than #2 on average
• ~$130M EBITDA in 2026 on ~$1.3B revenue, growing rev >20% and likely EBITDA >40% for years
• Destroyed Rappi and Uber Eats in many markets
• iFood is the closest comp. Prosus bought the rest of it at ~$6B (~5.5x revenue) in late 2022 while unprofitable, in a bear market. Grab trades at 4x sales and isn't a better company.
→ Should be 30x EBITDA = ~$4B. 3x revenue is very fair
HUNGERSTATION
• #1 in Saudi (premium market), accelerating, >20% growth
• ~$90M EBITDA run-rate, ~$4B GMV
• Jahez is struggling badly and still trades at 12x EBITDA / 0.35x GMV
→ Worth ~$2B
EUROPE — Glovo / Foodora / eFood / Foody
• $12.3B GMV. #1 on 97% of that
• DoorDash paid $3.9B for $ROO, which had $7.9B GMV, slower growth, and much lower average market share
• Expected to break even in 2026. Early, but the growth and incremental margins - especially at Glovo - point to an exceptional business. Glovo's been held back by fines for running a gig model in Spain and Italy
→ At a draconian 0.25x GMV = $3B
YEMEKSEPETI
• #1 in Turkey. ~$2.5–3.5B GMV, slightly loss-making
• Uber paid ~$900M for #2 Trendyol Go
→ Probably worth ~$1B
FOODPANDA
• Southeast Asia. ~$2.5–3B GMV. Slightly loss-making but inflecting, growing double digits
• Just sold Taiwan to Grab at 0.33x GMV
→ 0.18x for conservatism ~$500M
ADD IT UP
Talabat $10B + Baemin $5.4B + PedidosYa $4B + HungerStation $2B + Europe $3B + Yemeksepeti $1B + Foodpanda $0.5B
= $25.9B − $1.9B net debt = $24B implied
= €66/share
That's a 0.39x blended EV/GMV across DHER's portfolio. This is not aggressive:
• Taiwan: unprofitable, part of their worst brand just sold for 0.33x
• Uber paid 0.35x for cash-burning #2 Trendyol
• Deliveroo, a clear #2/#3 in all its markets, sold for 0.5x GMV and 16x aEBITDA
• Just Eat Takeaway was getting killed and recently sold for 18x aEBITDA - we're comping Talabat, perhaps the best food delivery business ever, below that
• DoorDash paid >2x GMV for Wolt in 2022. Glovo is larger, has grown at roughly the same pace since, and hit profitability sooner (before EU fines knocked it back)
Whoever wins DHER wins global delivery
If you’re about to become an Engineering Manager, here’s the mindset shift:
Your value isn’t the code you write anymore.
It’s the clarity you provide, the alignment you drive, and the growth you enable.
@whistler_ad@Sidharthjain84 Bank ki market cap transactional hoti hai, based on balance sheets/profits
Zomato / any tech company is percieved market cap more like valuation and not profits