

Top Tweets for #INDIASHELTER

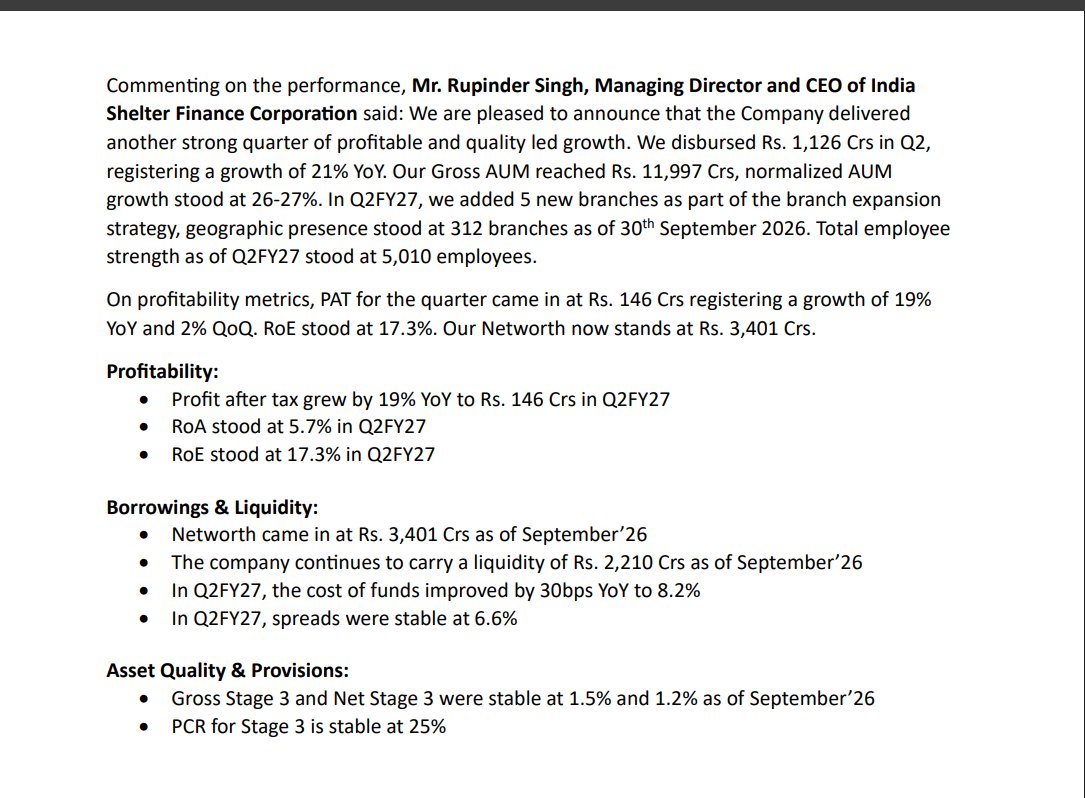
India Shelter Finance Corporation — Q2FY27 Results 🔔
#Q2Results #Q2FY27 #IndiaShelter
✓ Gross AUM ₹11,997 Cr (+23% YoY & +6% QoQ)
**Normalized AUM Growth 26–27% YoY
✓ Disbursements ₹1,126 Cr (+21% YoY & +8% QoQ)
✓ Interest Income ₹369.9 Cr (+24% YoY & +4% QoQ)
✓ Net Gain on Direct Assignments ₹39.8 Cr (+15% YoY & +10% QoQ)
✓ Non-Interest Income ₹40.7 Cr (+16% YoY & +4% QoQ)
✓ Total Income ₹450.5 Cr (+22% YoY & +4% QoQ)
✓ Net Total Income ₹322.3 Cr (+24% YoY & +3% QoQ)
✓ PPOP ₹204.9 Cr (+22% YoY & +3% QoQ)
✓ PBT ₹188.6 Cr (+19% YoY & +2% QoQ)
✓ PAT ₹145.6 Cr (+19% YoY & +2% QoQ)
✓ Basic EPS ₹13.4 vs ₹11.3
✓ Spread 6.6% vs 6.4% YoY & 6.6% QoQ
✓ ROA 5.7% vs 5.8% YoY vs 5.8% QoQ
✓ ROE 17.3% vs 17.0% YoY & 17.5% QoQ
✓ Opex / Gross AUM 4.0% vs 3.9% YoY & 4.0% QoQ
✓ Credit Cost ₹16.3 Cr (+72% YoY & +22% QoQ)
✓ GNPA 1.5% vs 1.2% YoY & 1.5% QoQ
✓ NNPA 1.2% vs 0.9% YoY & 1.2% QoQ
✓ 30+ DPD 5.2% vs 4.6% YoY & 5.2% QoQ
✓ Collection Efficiency 98% vs 99% YoY & 97% QoQ
✓ Added 5 new branches in Q2FY27
✓ Branch network 312 branches as of 30 Sept 2026
✓ Employee strength 5,010
✓ Liquidity ₹2,210 Cr as of September 2026
✓ Cost of funds improved 30 bps YoY to 8.2%


HFCs and SFBs: Valuation & opportunity
Systematix sees meaningful upside across Housing Finance Companies and Small Finance Banks.
✅ Housing Finance:
#Aptus Housing — 73% upside
#Home First Finance — 44%
#IndiaShelter — 39%
#Aavas Financiers — 39%
#Aadhar Housing — 31%
✅ Small Finance Banks:
#Capital SFB — 79% upside
#Equitas SFB — 40%
#Ujjivan SFB — 32%
#AU SFB — 23%
#Jana SFB — 18%
#Investing #Stocks #HFC #SFB

@EquityInsightss
🔥 NBFC & HFC Valuation Summary – Strong Growth Potential! 📈
Most names in the coverage carry Buy ratings with solid upside:
HFCs look very attractive:
🔥 Upside potential #HomeFirst (35%), #Aadhar & #Aptus (30% each), #Indiashelter (26%)
Special highlight on Indiashelter & Aptus 🔥
Both deliver very strong RoEs, 🔥 attractive dividend yields, proven track record, and are growing rapidly.
These are structural long-term plays.
Diversified players like Bajaj Finance (15%) and IIFL (20%) also offer decent headroom.
🔥 My fav #IndiaShelter best in class RoA, RoE, Asset Quality, Proven management track record, Best in grow above 35% with good dividend yield.
Sector outlook remains constructive for long-term investors.


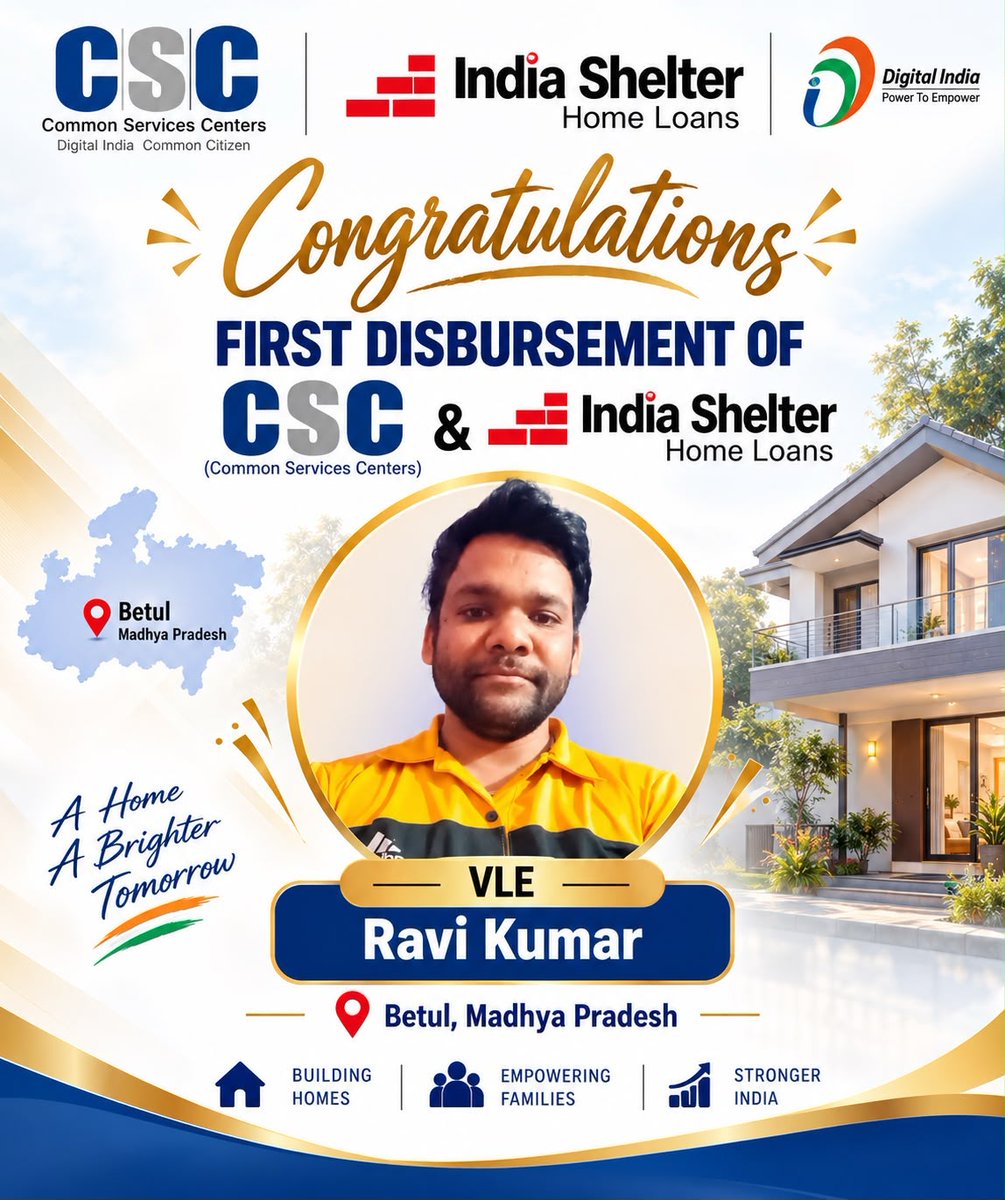
Congratulations!!
India Shelter Home Loans First Disbursement from Madhya Pradesh by VLE Ravi Kumar.
#csc #cscloanbazar #cscfinancialservices #indiashelter
Congratulations💐
India Shelter Home Loans First Disbursement from Dhle Maharashtra by VLE Mr. Bhushan Sonkamlbe.
#csc #cscloanbazar #cscfinancialservices #indiashelter

Affordable Housing Finance — an interesting space to watch 💥
My two fav #Aptus & #IndiaShelter
$Aptus
• Target ₹380 → 48% upside💥
• FY 29 P/E 8.2x
• RoA remains strong at ~7%
• RoE sustains ~20%+
$IndiaShelter
• Target ₹880 → 35% upside 💥
• P/E falls from 14.1x → 7.6x
• RoA remains ~5.4–5.8%
• RoE expands from 17% → 19.3%
What makes the thesis interesting is growth + improving valuation + high return ratios.
If earnings compound as expected, these could be among the more interesting long-term housing finance plays.

#India Shelter Finance – Go against the Noise 🤗
ICICI Securities retains BUY | TP ₹1,125 💥53% upside from CMP ₹670
Q1FY27 was a solid quarter for India Shelter despite two temporary headwinds — seasonality and a change in disbursement recognition policy.
Core operating strength remained intact:
• RoE sustained at ~18% (17.5% reported)
• RoA at 5.8%
• Spreads held steady at 6.6%; incremental spreads touched ~7%
• Higher yields + lower borrowing costs supported margins
Disbursement policy shift created noise:
Company moved from recognising disbursements on hand-over to cheque clearance. As a result:
• Disbursements fell 28% YoY / 38% QoQ to ₹6.41 bn
• On old basis, disbursements would have been ~₹10.46 bn
• AUM growth moderated to 2% QoQ / 24% YoY
Management remains confident of 25–30% AUM growth for full FY27. July disbursements already touched ₹4 bn on the new basis.
Asset quality – seasonal blip, guidance maintained:
• GNPL rose to 1.5% (from 1.2% YoY)
• 30+ DPD increased to 5.2%
• Collection efficiency dipped to 97%
• Credit cost at 50 bps (flat YoY)
Stress is largely concentrated in the micro-loan book (~15-20% of portfolio). Management expects improvement in H2 and has retained full-year credit cost guidance of 40–50 bps.
Other positives:
• Operating leverage improving with better branch productivity and digital sourcing
• Opex-to-assets expected to decline gradually
• Strong capital position and healthy RoE trajectory (guided to stay elevated)
Valuation: ICICI Securities values the stock at 3.2x Mar’27E BVPS, arriving at TP of ₹1,125.
Bottom line: Temporary noise from policy change and seasonality. Underlying franchise quality, margin resilience, and AUM growth visibility remain intact.


HomeFirst Finance Q1FY27 Result & Concall Analysis
->Why HFC aren't looking that great
->Slowdown in growth across all players?
->Can Valuations rerate going ahead?
#homefirst #indiashelter
#IndiaShelter Finance – Highest upside in the NBFC coverage
Buy | CMP ₹669 | TP ₹900 | +35% upside 💥
Key metrics (FY28E):
• RoE: 19.5%
• RoA: 5.8% (one of the highest in the pack)
• P/E: 9.3x | P/BV: 1.7x
• NNPA: ~1.1% (stable asset quality)
Net profit expected to grow from ₹6.3 bn (FY27) → ₹7.8 bn (FY28) → ₹9.6 bn (FY29).
Despite recent underperformance (–18% in 1M, –27% in 12M), the stock offers the #best risk-reward among housing finance names in the table with strong return ratios and reasonable valuations.
#IndiaShelter #NBFC #HousingFinance

#India Shelter Finance – Go against the Noise 🤗
ICICI Securities retains BUY | TP ₹1,125 💥53% upside from CMP ₹670
Q1FY27 was a solid quarter for India Shelter despite two temporary headwinds — seasonality and a change in disbursement recognition policy.
Core operating strength remained intact:
• RoE sustained at ~18% (17.5% reported)
• RoA at 5.8%
• Spreads held steady at 6.6%; incremental spreads touched ~7%
• Higher yields + lower borrowing costs supported margins
Disbursement policy shift created noise:
Company moved from recognising disbursements on hand-over to cheque clearance. As a result:
• Disbursements fell 28% YoY / 38% QoQ to ₹6.41 bn
• On old basis, disbursements would have been ~₹10.46 bn
• AUM growth moderated to 2% QoQ / 24% YoY
Management remains confident of 25–30% AUM growth for full FY27. July disbursements already touched ₹4 bn on the new basis.
Asset quality – seasonal blip, guidance maintained:
• GNPL rose to 1.5% (from 1.2% YoY)
• 30+ DPD increased to 5.2%
• Collection efficiency dipped to 97%
• Credit cost at 50 bps (flat YoY)
Stress is largely concentrated in the micro-loan book (~15-20% of portfolio). Management expects improvement in H2 and has retained full-year credit cost guidance of 40–50 bps.
Other positives:
• Operating leverage improving with better branch productivity and digital sourcing
• Opex-to-assets expected to decline gradually
• Strong capital position and healthy RoE trajectory (guided to stay elevated)
Valuation: ICICI Securities values the stock at 3.2x Mar’27E BVPS, arriving at TP of ₹1,125.
Bottom line: Temporary noise from policy change and seasonality. Underlying franchise quality, margin resilience, and AUM growth visibility remain intact.
Congratulations!
India Shelter Finance Corporation Ltd Home Loan & Loan Against Property is Live now on CSC Loan Bazar Portal.
For any query, write us on [email protected]
#csc #cscloanbazar #indiashelter #cscfinanicalservices

India Shelter Finance Corp Q1FY27 Result & Concall Analysis
->Is it still the best among AffordabLE HFC's?
->Asset Quality Under Pressure
->Long term target of 30,000 CR AUM Intact?
#indiashelter #hfc
@MithunSarkari Holding #IndiaShelter not in a hurry to sell at this valuation. Yes, stock is not going to recover soon due to negative sentiment across HFC.
India Shelter Finance | Q1FY27 Concall Deep Dive
Stock is down by 30% from top
AUM: ₹11,284 Cr (+24% YoY, +2% QoQ)
PAT: ₹143 Cr (+20% YoY, +4% QoQ)
RoE: 17.5% | RoA: 5.8%
Spread: Stable at 6.6%
Portfolio yield: 14.8% | Disbursement yield: 14.9%
Disbursement Accounting Change
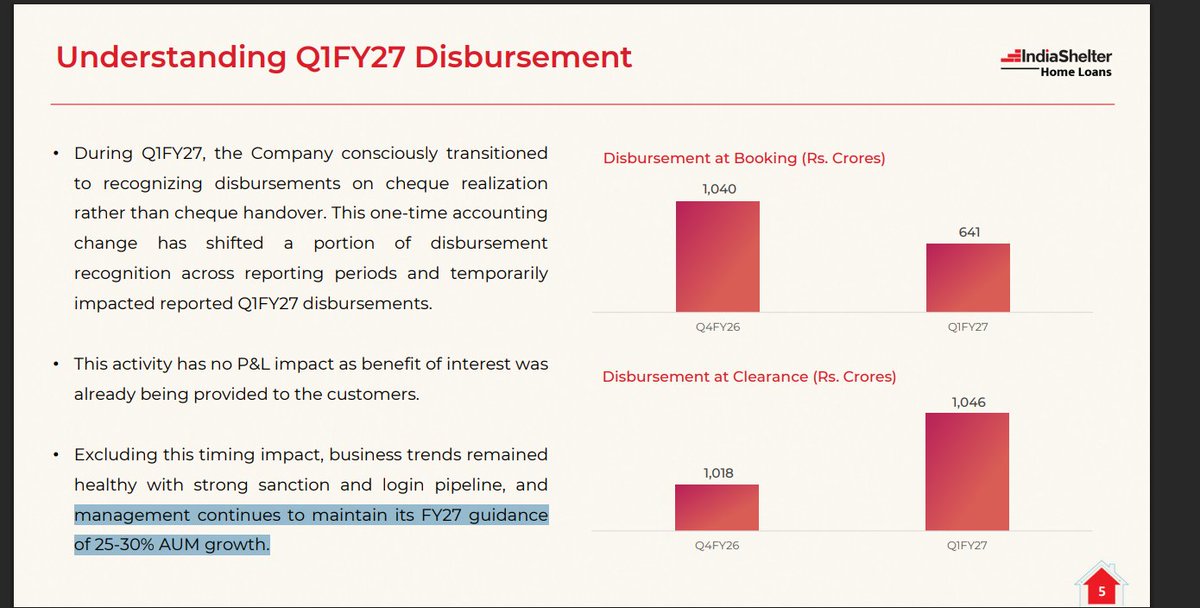
Reported disbursements came in at only ₹641 Cr due to a one-time shift from cheque handover to cheque clearance recognition.
Actual bank clearances were ~₹1,040–1,046 Cr (flat QoQ, +36-37% YoY). No P&L impact. Underlying login & sanction pipeline remains healthy. July run-rate also looking better.
Asset Quality – The Key Watch Area
Gross Stage 3: 1.5% (↑30 bps QoQ)
Net Stage 3: 1.2%
30+ DPD: ~5.2% (highest in recent quarters)
Collection efficiency: ~97% (vs 100% in Q4)
Management attributes the rise to:
Seasonal Q1 weakness
Stress in self-employed & smaller ticket borrowers (book ~85%+ self employed)
Management Outlook
Expects Stage 3 to stabilise around current levels by end of Q2
Recovery expected from Q3 FY27 onwards.
Credit cost guidance maintained at 40–50 bps for the year
Guidance Reiterated for FY27
AUM growth: 25–30%
Branch additions: 40–45
Spreads: >6%
Credit cost: 40–50 bps
Bottom Line - Business momentum is intact beneath the accounting noise. Profitability remains strong. But the sequential deterioration in early delinquencies and collection efficiency needs close monitoring in Q2.
#INDIASHLTR #AffordableHousing #NBFC
India Shelter Finance Corporation Q1FY27
#Q1Results #Q1FY27 #Nifty #Indiashelter
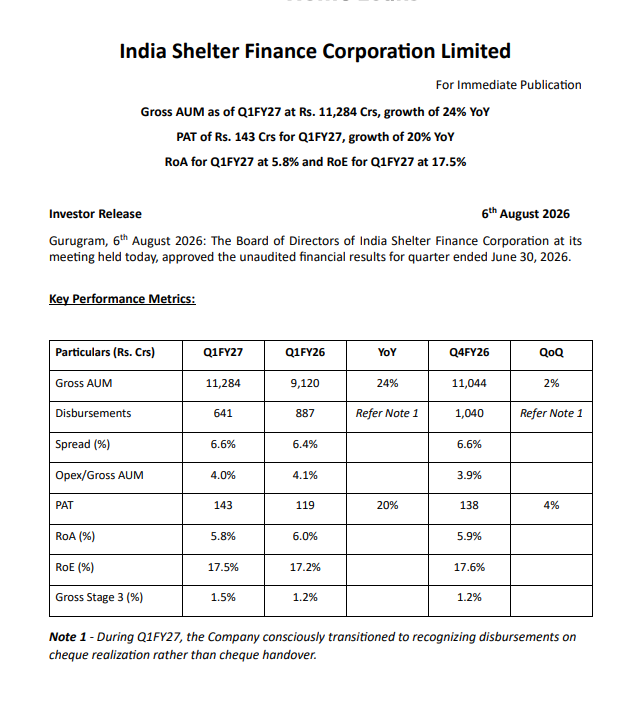
➤ Gross AUM ₹11,284 Cr (+24% YoY & +2% QoQ)
➤ Disbursements ₹641 Cr. During the quarter, the company transitioned to recognizing disbursements on cheque realization instead of cheque handover, temporarily impacting reported disbursements. Disbursement at clearance stood at ₹1,046 Cr for Q1 FY27
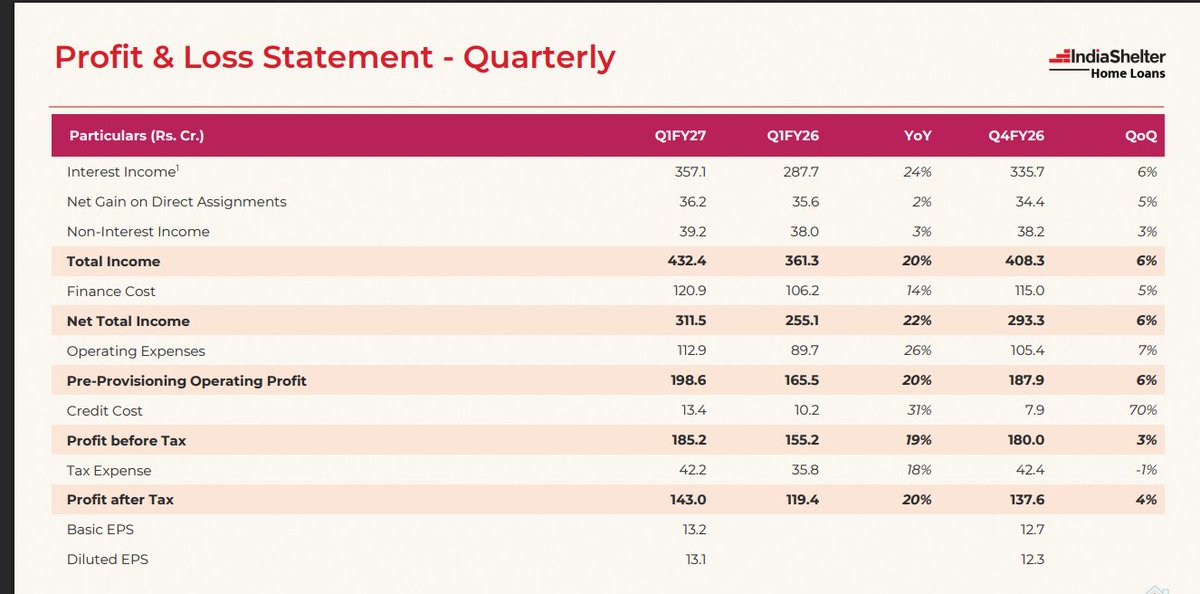
➤ Interest Income ₹357.10 Cr (+24% YoY & +6% QoQ)
➤ Total Income ₹432.40 Cr (+20% YoY & +6% QoQ)
➤ Net Total Income ₹311.50 Cr (+22% YoY & +6% QoQ)
➤ PPOP ₹198.60 Cr (+20% YoY & +6% QoQ)
➤ PBT ₹185.20 Cr (+19% YoY & +3% QoQ)
➤ PAT ₹143.00 Cr (+20% YoY & +4% QoQ)
➤ ROA 5.8% vs 6.0% YoY & 5.9% QoQ
➤ ROE 17.5% vs 17.2% YoY & 17.6% QoQ
➤ Spread 6.6% vs 6.4% YoY & 6.6% QoQ
➤ Credit Cost ₹13.40 Cr (+31% YoY & +70% QoQ)
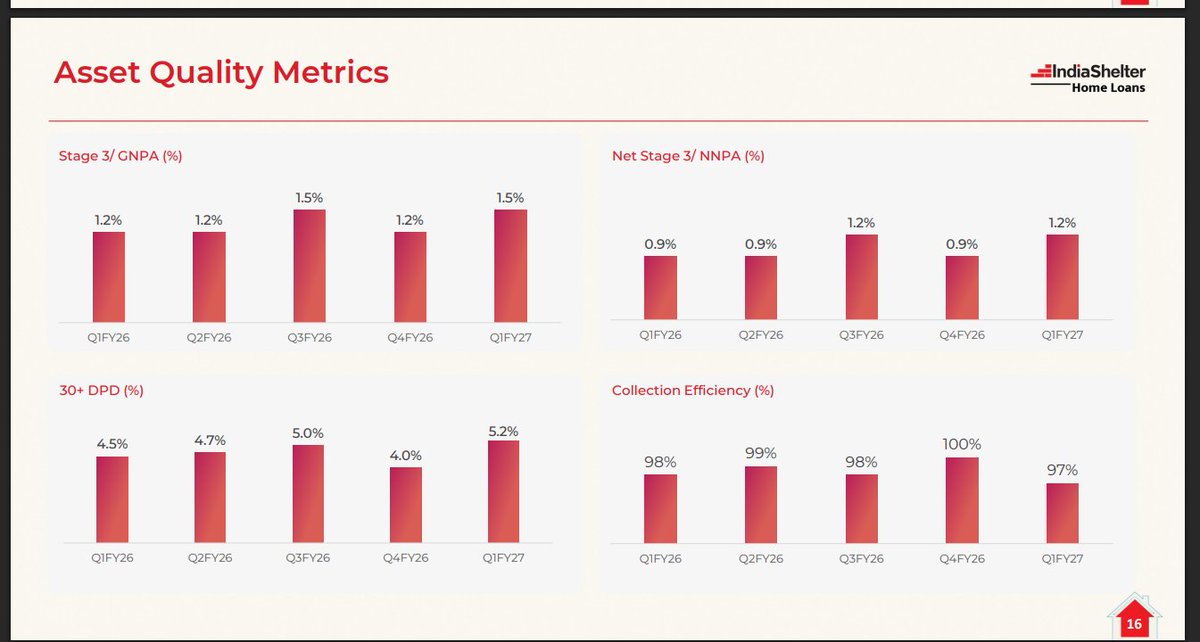
➤ GNPA 1.5% vs 1.2% YoY & 1.2% QoQ
➤ NNPA 1.2% vs 0.9% YoY & 0.9% QoQ
➤ 30+ DPD 5.2% vs 4.5% YoY & 4.0% QoQ
➤ Management continues to maintain its FY27 guidance of 25-30% AUM growth
India Shelter Finance Corporation Limited Q1FY27 Results:-
#Q1Results #Q1FY27 #Stockmarket #Nifty #Indiashelter
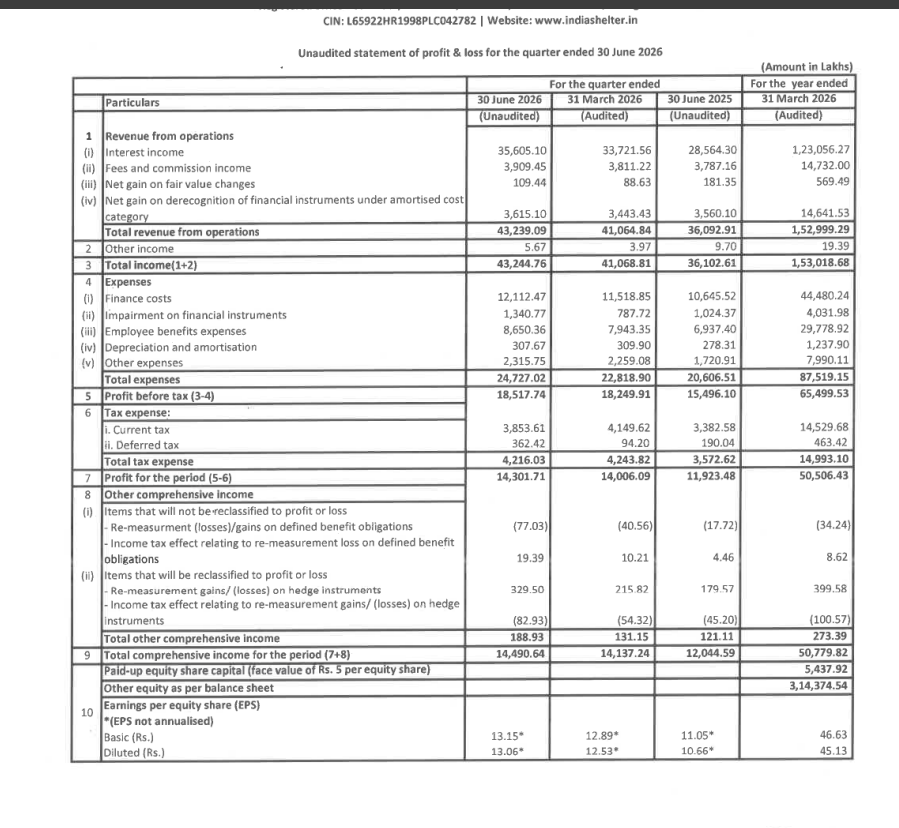
Total Revenue 432.39 Cr vs 360.93 Cr
(+19.80% YoY┃+5.29% QoQ)
PBT 185.18 Cr vs 154.96 Cr
(+19.50% YoY┃+1.47% QoQ)
PAT 143.02 Cr vs 119.23 Cr
(+19.95% YoY┃+2.11% QoQ)
GNPA 1.55% vs 1.24% YoY & 1.25% QoQ
NNPA 1.15% vs 0.95% YoY & 0.93% QoQ


India Shelter Finance Corporation Limited Q1FY27 Results:-
#Q1Results #Q1FY27 #Stockmarket #Nifty #Indiashelter
Total Revenue 432.39 Cr vs 360.93 Cr
(+19.80% YoY┃+5.29% QoQ)
PBT 185.18 Cr vs 154.96 Cr
(+19.50% YoY┃+1.47% QoQ)
PAT 143.02 Cr vs 119.23 Cr
(+19.95% YoY┃+2.11% QoQ)
GNPA 1.55% vs 1.24% YoY & 1.25% QoQ
NNPA 1.15% vs 0.95% YoY & 0.93% QoQ
India Shelter Finance Corporation Limited Q1FY27 Results:-
#Q1Results #Q1FY27 #Stockmarket #Nifty #Indiashelter
Total Revenue 432.39 Cr vs 360.93 Cr
(+19.80% YoY┃+5.29% QoQ)
PBT 185.18 Cr vs 154.96 Cr
(+19.50% YoY┃+1.47% QoQ)
PAT 143.02 Cr vs 119.23 Cr
(+19.95% YoY┃+2.11% QoQ)
GNPA 1.55% vs 1.24% YoY & 1.25% QoQ
NNPA 1.15% vs 0.95% YoY & 0.93% QoQ

1/ Two affordable housing lenders. Same sector, same year.
One grows its loan book faster — AUM +29% vs +24.9% (INR) — and earns more on every rupee lent: RoA 5.9% vs 4.1%. 🏦
Yet the market values the slower, lower-return one more richly. Why? 👇
#IndiaShelter #HomeFirst
->AAVAS Financiers is down 60% from ATH
->Is it a buying Opportunity or Trap?
->How are Current Valuations Looking?
->Are Peers Better?
#aavasfinanciers #aptus #homefirst #indiashelter

If you’re worried about #IndiaShelter or #HomeFirstFinance now, you may be reacting late.
After Q2, I had shared why I didn’t expect outsized returns from here. The thesis was simple: growth would moderate as competition intensified and the broader banking system adjusted.
We’re starting to see that play out. Guidance has been trimmed and growth expectations are being recalibrated.
The mistake many make is analyzing housing finance or other sub-segments of banking in isolation. Always know that capital moves across the entire banking ecosystem. So, when pricing shifts in one segment, it’ll most likely ripple through others.
However, that doesn’t make these poor businesses. They remain well-collateralised, and asset quality fears are likely overstated over a full cycle.
I’m not worried about asset quality, my broader concern is whether they can return to their earlier high growth rates in a crowded market. That’s where my original view stands: valuation caps upside when growth normalises.
That said, markets are dynamic. If prices correct meaningfully even from these levels, risk-reward can again change.
Successful investing is unique in the sense that it is less about being right once and more about tracking how capital flows and adjusting accordingly.
I hope the earlier post had helped many of you :)
#IndiaShelterFinance
#HomeFirstFinance
If you’re new to housing finance, you might think their Q2 numbers were ‘blockbuster’, ‘solid’, or ‘add any adjective of your choice’.
After all, ~30% growth isn’t easy to achieve.
But if you’ve been following me, you know why housing finance companies won’t deliver outsized returns from here.
The space is crowded with PSU banks, private banks, NBFCs, SFBs, even PE-backed wealth managers chasing the same borrower.
That kind of competition crushes lending yields.Balance transfers are now routine.
And unlike diversified NBFCs, HFCs don’t have multiple yield levers to fall back on.
Yes, valuations have cooled a bit, but most are still around 3x P/B, leaving little room for major rerating. Sure, they can still compound 15–20% annually if execution stays solid.
But the real opportunity lies in spotting undervalued names where fundamentals are turning — bottom-up, not sector-wide.
I could be wrong, of course. Markets in bull phases have a way of humbling everyone :)

India Shelter Finance
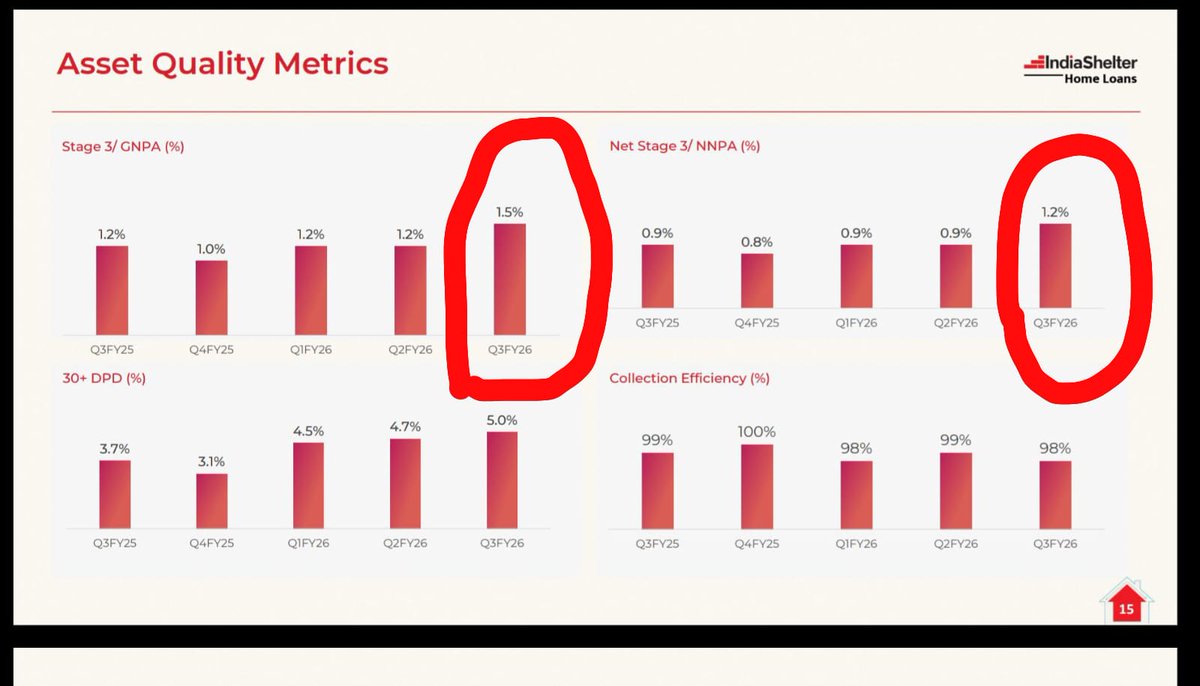
GNPA and NNPA increase 🚨
🏆 Follow🔖 @subrata_minu
#IndiaShelter
#Investor #Niftycrash #OptionsTreding #Investing #Breaking #Nifty #BreakingNews
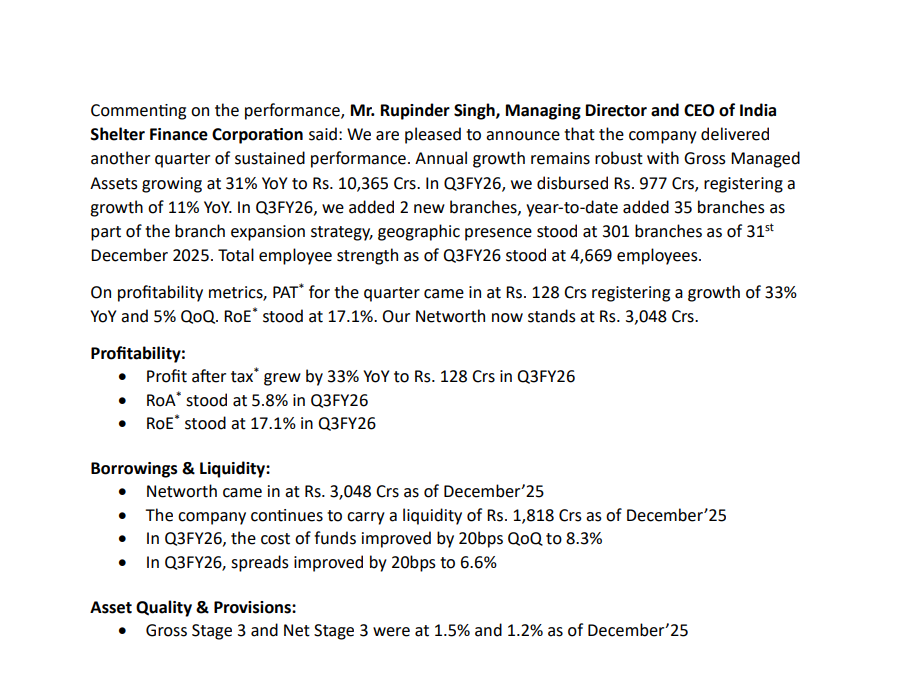
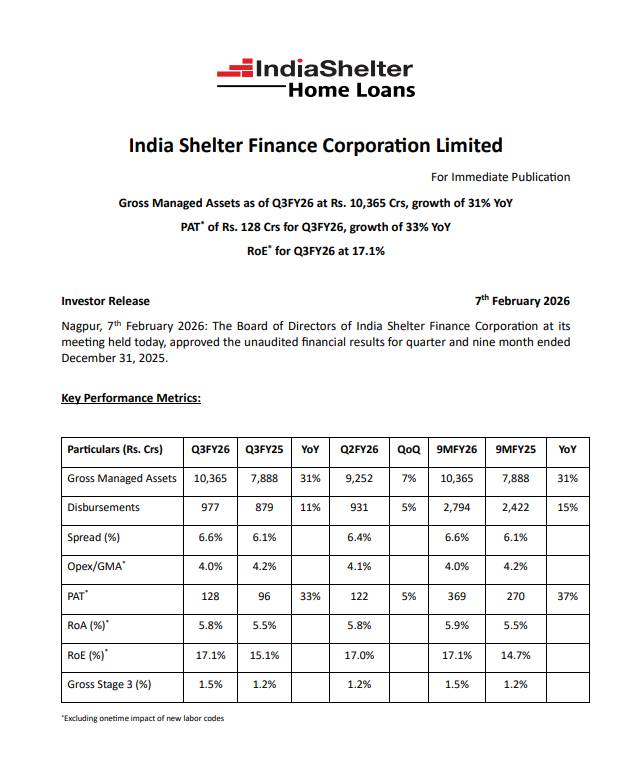
India Shelter Finance Corporation Q3 FY26 :-
#Q3Results #Q3FY26 #Stockmarket #Nifty #indiashelter
➤ Gross Managed Assets (GMA) ₹10,365 Cr (+31% YoY & +7% QoQ)
➤ Disbursements ₹977 Cr (+11% YoY & +5% QoQ)
➤ Interest Income (+28% YoY)
➤ Total Income (+28% YoY)
➤ Net Total Income (+30% YoY)
➤ Pre-Provisioning Operating Profit (+30% YoY)
➤ Credit Cost (+43% YoY)
➤ PAT ₹128 Cr (+33% YoY & +5% QoQ)(*Excluding onetime impact of new labor codes)
➤ Spread 6.6% vs 6.1% YoY & 6.4% QoQ
➤ Cost of funds improved by 20bps QoQ to 8.3%
➤ Opex / GMA 4.0% (improving trend)
➤ GNPA 1.5% vs 1.2% YoY & 1.2% QoQ (Trending upwards)
➤ NNPA 1.2% vs 0.9% YoY & 0.9% QoQ (Trending upwards)
➤ 30+ DPD 5.0% vs 3.7% YoY & 4.7% QoQ
➤ Collection Efficiency 98% vs 99% YoY & 99% QoQ


India Shelter Finance Corporation Limited Q3 FY26 Results:-
Consolidated
PAT 124.07 Cr vs 96.14 Cr
(+29.05% YoY┃+1.66% QoQ)
GNPA 1.54% vs 1.25% QoQ
NNPA 1.16% vs 0.94% QoQ
#Q3Results #Q3FY26 #Stockmarket #Nifty #indiashelter

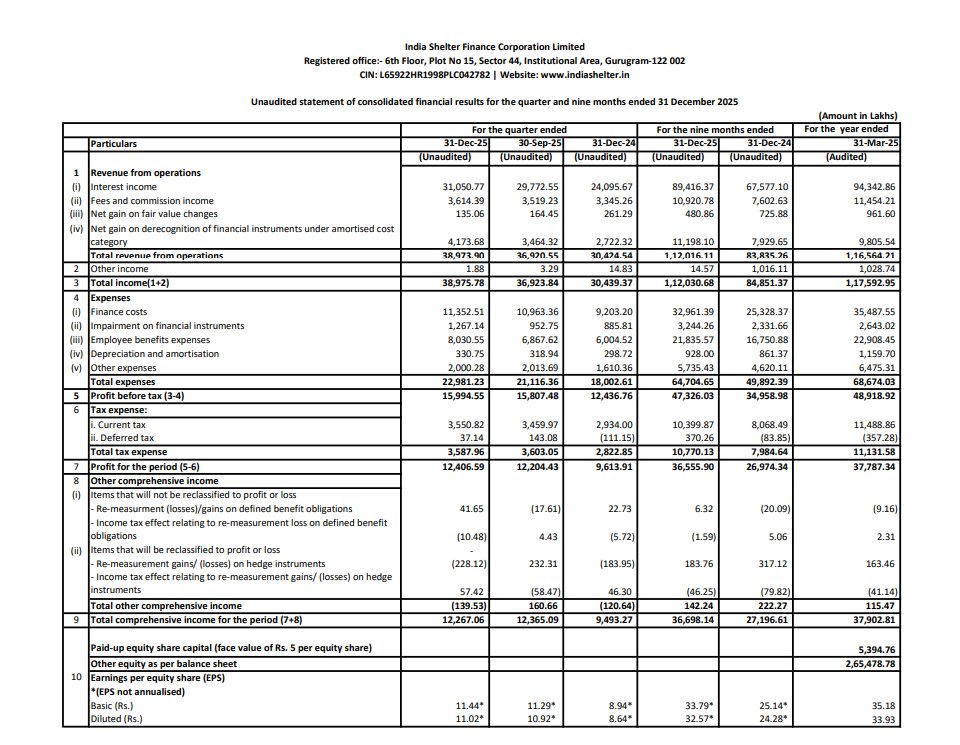
India Shelter Finance Corporation Limited Q3 FY26 Results:-
Consolidated
PAT 124.07 Cr vs 96.14 Cr
(+29.05% YoY┃+1.66% QoQ)
GNPA 1.54% vs 1.25% QoQ
NNPA 1.16% vs 0.94% QoQ
#Q3Results #Q3FY26 #Stockmarket #Nifty #indiashelter

India Shelter leading housing finance company: -
=> Business Analysis
=> Q2FY26 Number
=> Company Valuation
=> Management Guidance
#StockMarketIndia #StockToWatch #Indiashelter #Finance
Last Seen Hashtags on Sotwe
பெம்டாம்
Seen from India
minichattt
Seen from France
MGAI()* -minichat has:videos
Seen from Canada
AyeshaKhan
Seen from United States
mgai video**************
Seen from Argentina
unexpected
Seen from United States
mgai(*)*************filter:videos
Seen from United States
VietHub
Seen from United States
浴巾蒙头
Seen from Japan
สาวใหญ่โคราช
Seen from Thailand
Trends for you
Most Popular Users

Elon Musk 
@elonmusk
240.5M followers

Barack Obama
@barackobama
118.7M followers

Cristiano Ronaldo
@cristiano
114.4M followers

Donald J. Trump
@realdonaldtrump
111.8M followers

Narendra Modi
@narendramodi
107M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.2M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.4M followers

Kim Kardashian
@kimkardashian
70.8M followers

YouTube
@youtube
68.7M followers

Neymar Jr
@neymarjr
66.4M followers

Bill Gates
@billgates
65.2M followers

Selena Gomez
@selenagomez
63M followers

The Ellen Show
@theellenshow
62.1M followers

CNN
@cnn
61.7M followers

X
@x
60.6M followers