

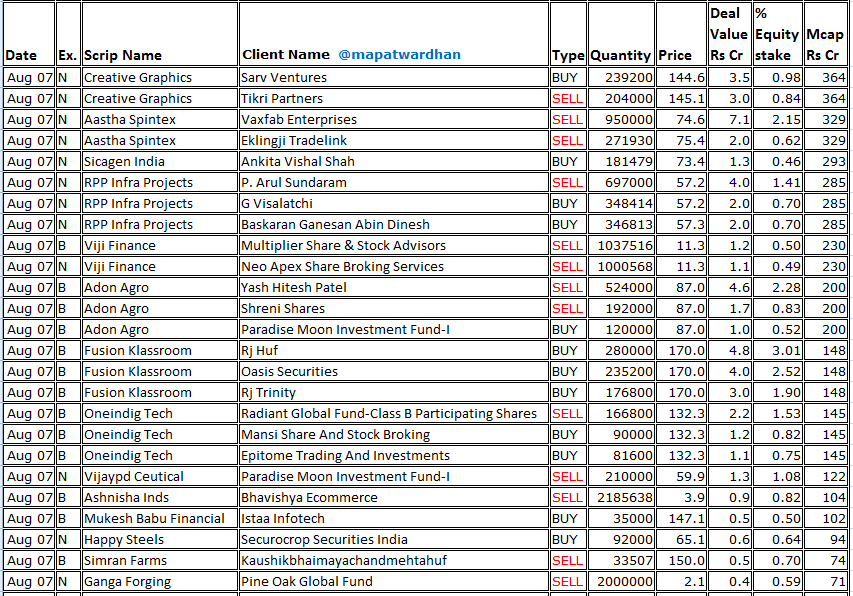
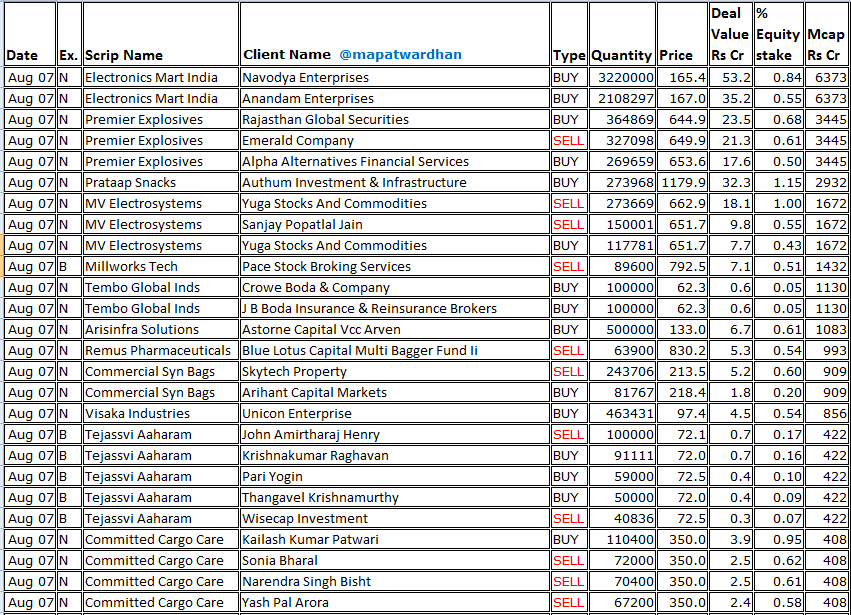
Top Tweets for #Temboglobal

10 . Tembo Global Industries Ltd 🔖
🚀Change In Promoters Holding ~ 2.66 %🚀
◉ Mar 2026~37.74%🔥
◉ Jun 2026 ~39.04% 💥
#temboglobal
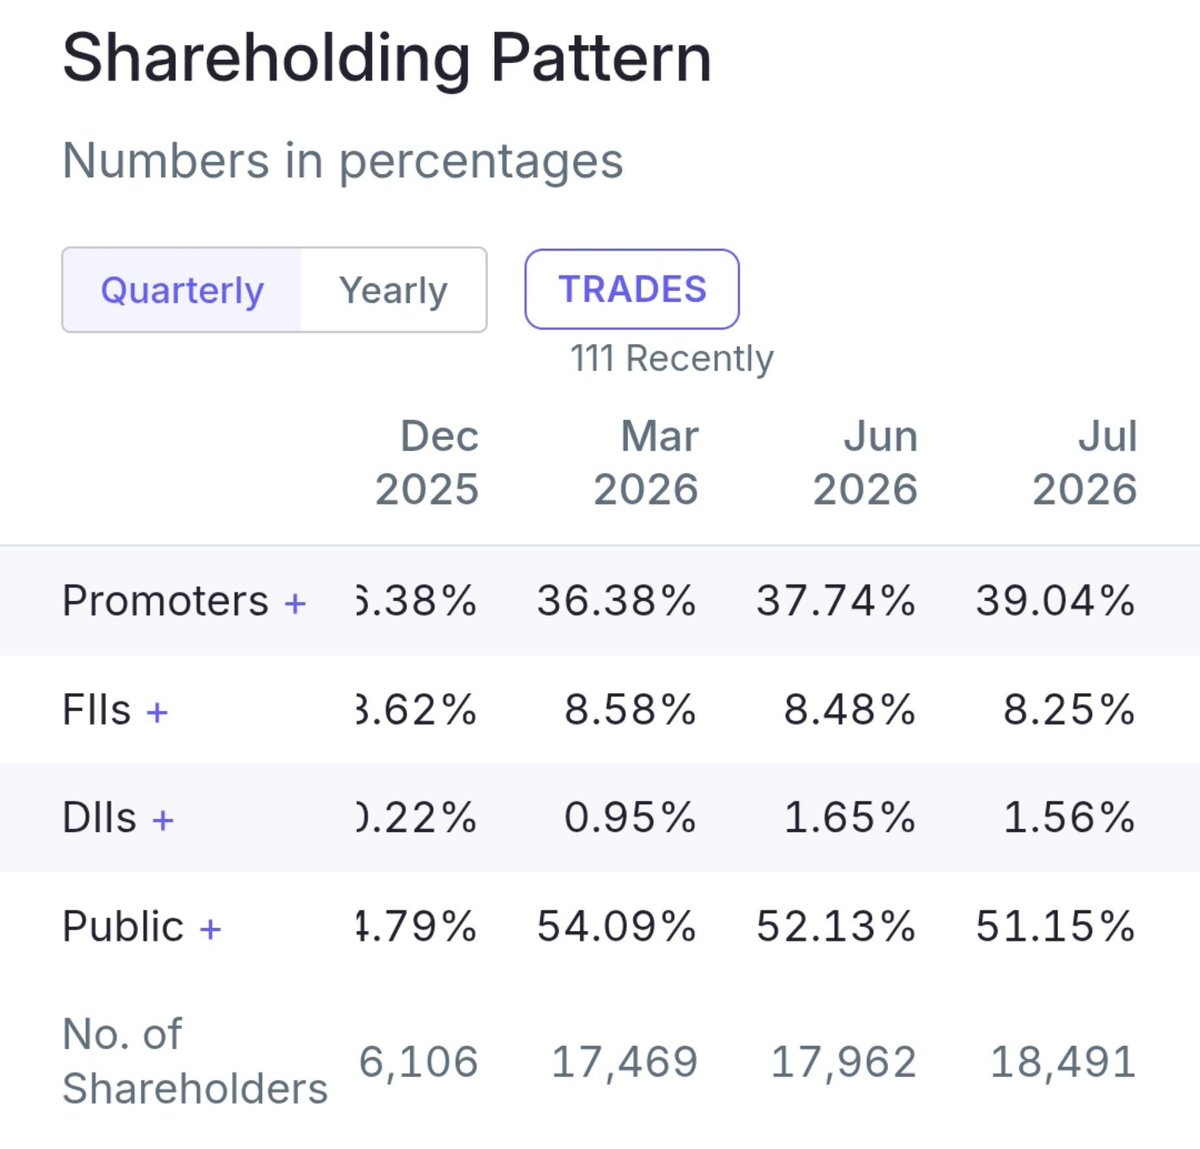
4 . Tembo Global Industries Ltd 🔖
🚀Change In Promoters Holding ~2.66 %🚀
◉ Mar 2026~ 37.74%🔥
◉ Jun 2026 ~39.04% 💥
#temboglobal
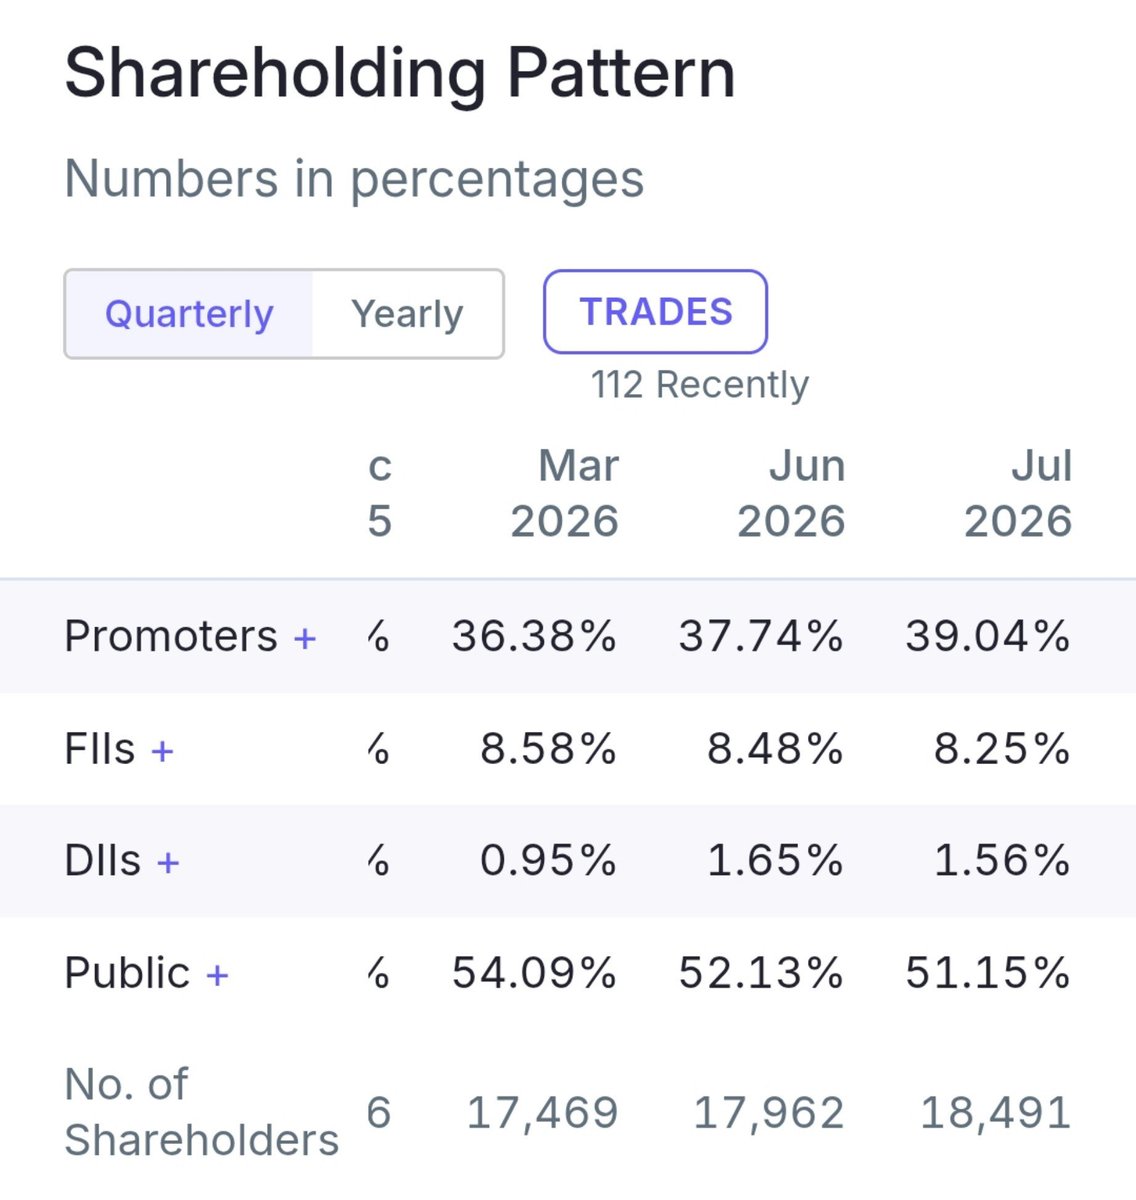
6 . Tembo Global Industries Ltd 🔖
#temboglobal
🚀Change In Promoter Holding ~2.66 %
🔸Mar 2026~37.74%🔥
🔸Jun 2026 ~39.04 %💥

#JustIn | #TemboGlobal signs MoU with #Belgium’s Lachaussee SA to establish advanced ammunition pdn line in India
Project valued at €50 m to produce 100 million rounds of ammunition annually

9 . Tembo Global Industries Ltd 🔖
#temboglobal
🚀Change In Promoter Holding ~2.66%
🔸Mar 2026~ 37.74% 🔥
🔸Jun 2026 ~ 39.04 %💥

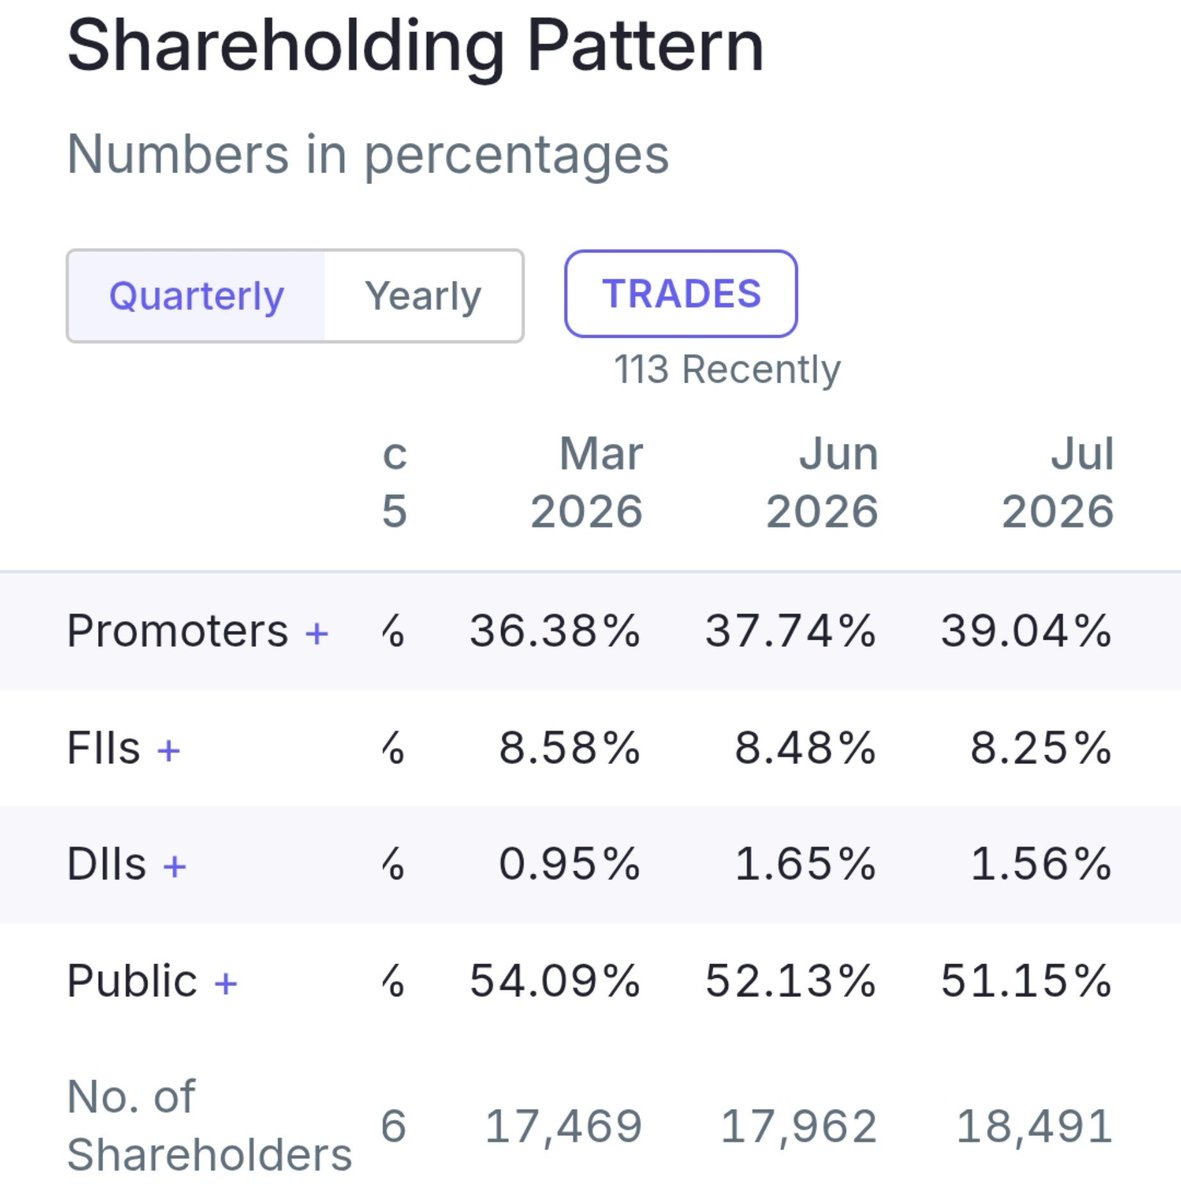
6 . Tembo Global Industries Ltd 🔖
#temboglobal
🚀Change In Promoter Holding ~2.66%
🔸Mar 2026~37.74% % 🔥
🔸Jun 2026 ~ 39.04 %💥


#TemboGlobal: Very Good Q1 Numbers
Revenue Up 22% and PAT Up 55% YoY. EBITDA Margin 16.3% v/s 11.35%
Stock trading at P/E 10X

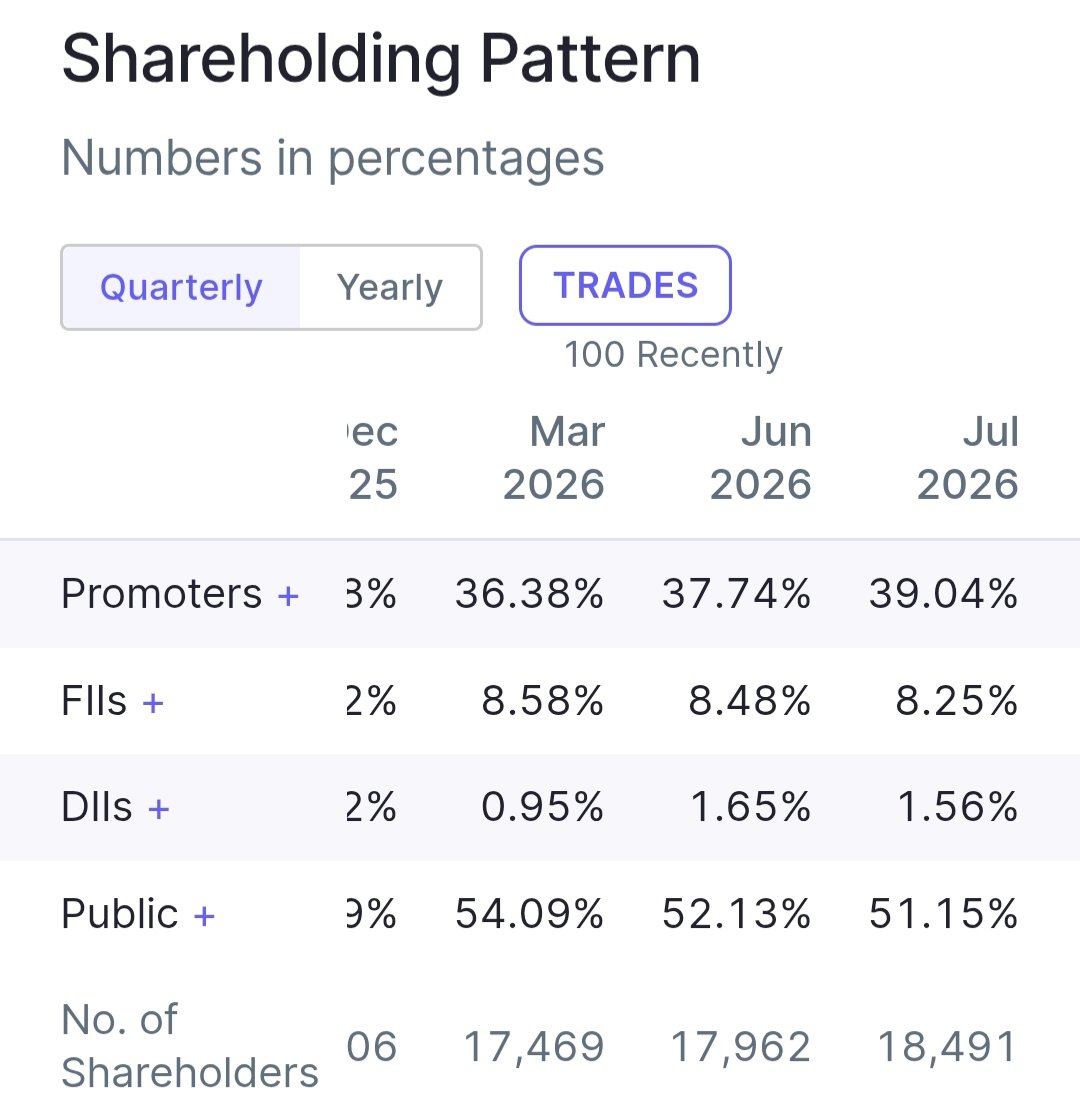
4 . Tembo Global Industries Ltd 🔖
#temboglobal
🚀Change In Promoter Holding ~ 1.28%
Mar 2026~37.74% 🔥
Jun 2026 ~39.04 % 🔥

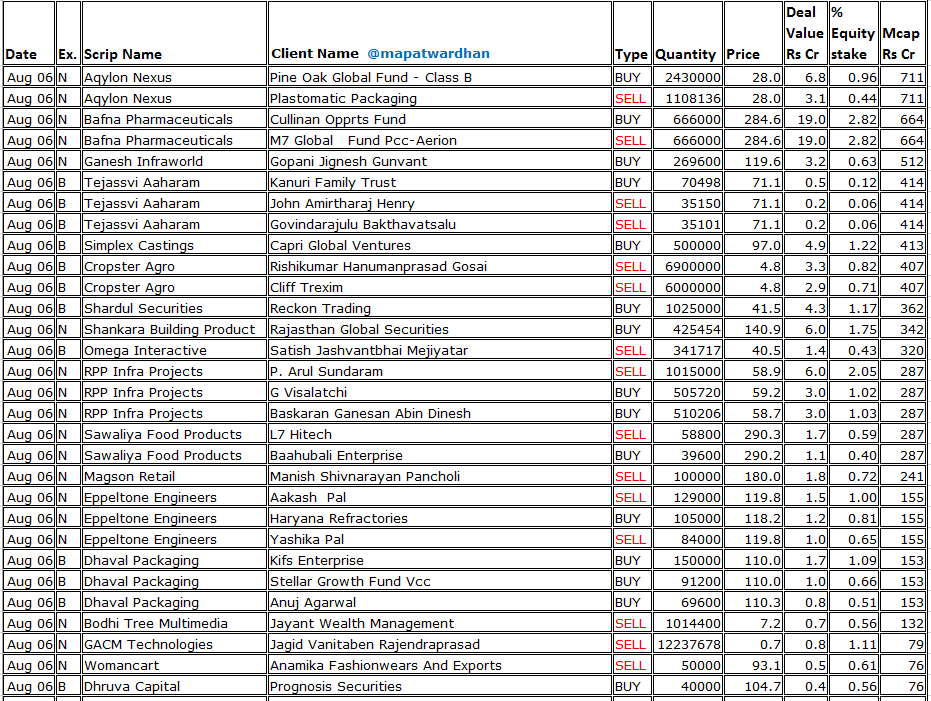
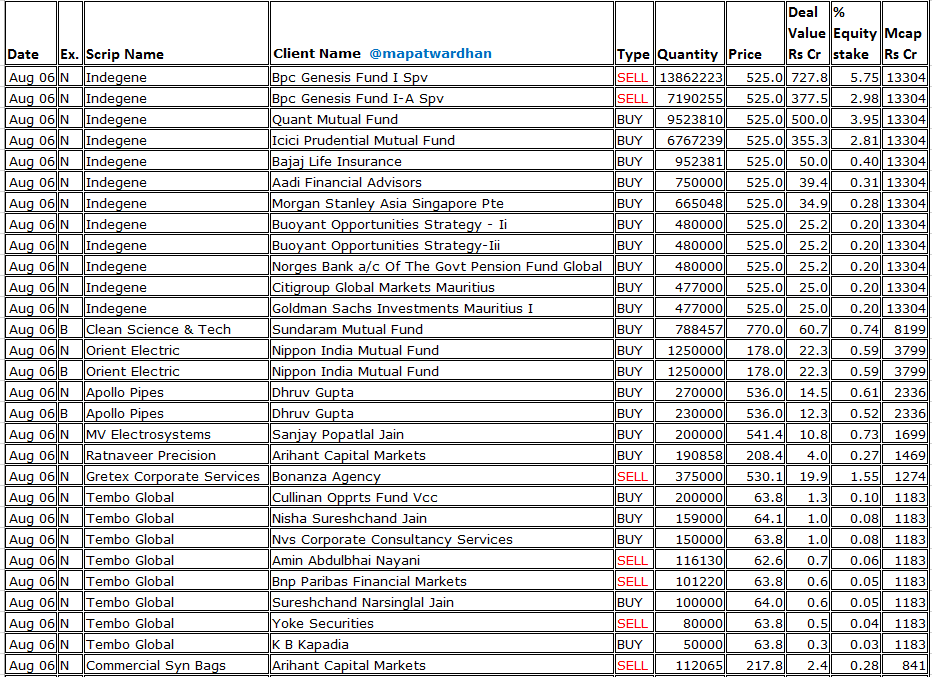
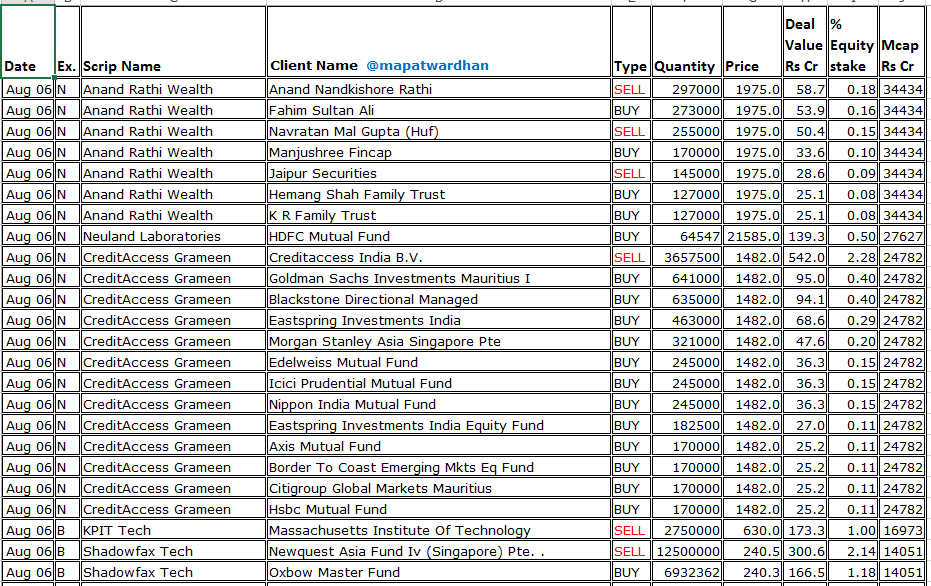

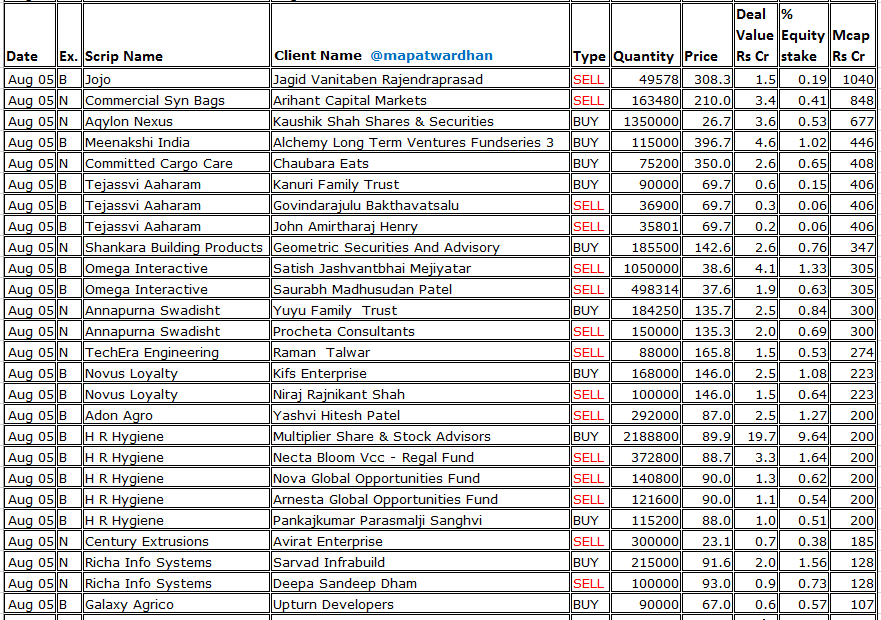
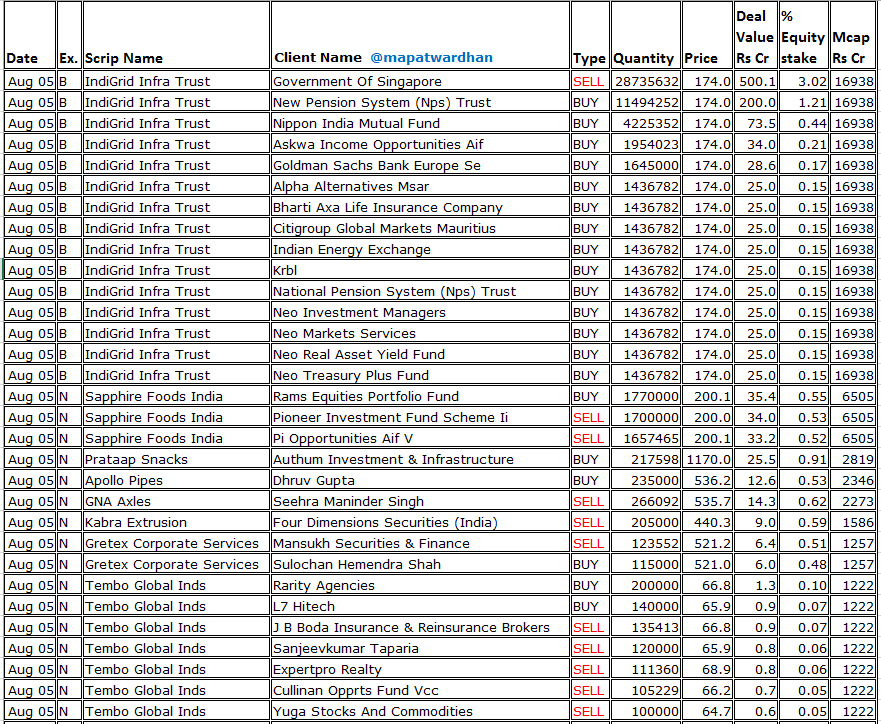
7 . Tembo Global Industries Ltd 🔖
#temboglobal
🔹Market Cap :₹ 1,069 Cr.
🔸P/E : 11.7
🔸5Yrs Sales Growth:60 %🔥
🔸5Yrs Profit Growth: 105%🔥
🔸ROCE ~ 22.8 %💥
🔸ROE ~ 27.5% 💥
🔸OPM ~13 % 🚀
🔸Promoter Holding : 37.74%

4 . Tembo Global Industries Ltd 🔖
💰Revenue Guidance : 47%🚀
📍Company has guided for FY27 revenue of INR 1,600 Cr. Management targeting INR 200+ Cr (a 2x growth) PAT in FY27.
#temboglobal #multibaggerstock #StockTrading


Out of 1000 cr sales , almost 500 cr is part of as other asset items.
Tembo carry Too many red flags 🚩
#temboglobal


#Tembo #TemboGlobal #TemboGlobalIndustries
Tembo Global Industries Q4 & FY26 Earnings Call Highlights
👉 FY27 & Future Outlook
▫️ FY27 revenue guidance: ~₹1,600 crore (30–40%+ YoY growth), driven primarily by continued scaling in the Engineering Solutions & EPC segment.
💠 PAT margins targeted at 10–12% at the group level, supported by higher contribution from margin-accretive engineering, EPC, and upcoming defence & solar streams.
💠 EBITDA margins expected to hold in the current range (~13%+) with further upside from operational efficiencies, better project mix, and defence ramp-up.
▫️ Solar power vertical:
💠All 28 sites expected to be fully operational by end-Q2 FY27
💠Commercial operations from Q3 FY27.
💠Project cost ~₹600 crore (₹300 crore already deployed). Will provide stable, diversified revenue from Q3 FY27 onward.
▫️ Defence manufacturing: No revenue in FY26.
💠Commercial production to commence in Q4 FY27.
💠First full year of operations (FY28) targeted at ₹300–400 crore topline with PAT of ₹170–180 crore (including depreciation).
💠Buy-back arrangement with European partner for initial phase.
▫️ Long-term vision (by 2030): Management targeting ₹20,000 crore topline, leveraging engineering/EPC scale-up, full solar contribution, defence indigenisation push and global EPC opportunities.
👉 Current Order Book / Projects and Future Pipeline
▫️ Current order book: ~₹1,548 crore (as on 31 Mar 2026) — entirely from Engineering Solutions & EPC segment.
💠 Provides medium-term revenue visibility.
▫️ Bidding pipeline: >₹2,256 crore (plus additional ₹700+ crore opportunities in port construction and fuel farm systems across civil, MEP & HVAC).
💠 Key win: L1 bidder for prestigious offshore revamp project in Kuwait (~₹300 crore) involving complex fire protection, marine equipment and integrated infrastructure.
▫️ Solar projects: 7–8 of 28 sites nearing commissioning; balance sites in next 3–4 months. Full commissioning targeted by end-Q2 / early-Q3 FY27.
▫️ Defence pipeline:
💠Small arms manufacturing licence secured (31 Dec 2025); ammunition licence (19 Apr 2026).
💠NDA signed with leading defence PSU for indigenous design, development & production.
💠Initial focus on small arms followed by ammunition over next 3 years.
▫️ Capacity expansion (Vasai plant & others):
💠Ramp-up from 18,000 MTA to 1,00,000 MTA already initiated (Jan 2026); full benefits to unfold over 2–3 years.
💠Factories currently running two shifts with daily order inflows.
👉 Other Notable Points
▫️ Segment mix (FY26): Engineering Products 60% | Textiles 40%
💠 Geographical mix: Domestic 88% | Exports 12%
▫️ Balance sheet strength: Debt-to-Equity 0.77:1 | ROCE 18.4% | ROE 20.0%
💠 Planned debt addition in FY27: ₹300–350 crore (primarily for solar, defence capex and working capital).
▫️ Minority interest:
💠Stable at ~10% of pre-minority PAT.
▫️ Engineering & EPC margins:
💠Primary driver of profitability; management highlighted focus on margin-accretive projects and execution excellence.
💠No material disruption from oil & gas prices (not a direct raw material).
▫️ Strategic diversification on track: Solar nearing commissioning, defence licences secured in record time, global EPC credentials strengthened via Kuwait win.


Tembo Global Industries Limited Q4FY26 Results:-
#Q4Results #Q4FY26 #Stockmarket #Nifty #Temboglobal
Revenue 345.96 Cr vs 273.99 Cr
(+26.27% YoY┃+38.00% QoQ)
EBITDA 39.01 Cr vs 28.85 Cr
(+35.24% YoY ┃-9.74% QoQ)
EBITDA Margin 11.28% vs 10.53% YoY & 17.24% QoQ
PBT 38.45 Cr vs 24.05 Cr
(+59.84% YoY┃+8.66% QoQ)
PAT 30.07 Cr vs 15.55 Cr
(+93.35% YoY┃+15.06% QoQ)
PAT After Minority interest 26.91 Cr vs 14.66 Cr
(+83.61% YoY┃+6.28% QoQ)
Other Income 8.37 Cr vs 0.81 Cr YoY & 0.39 Cr QoQ


Companies where there's a 𝟏𝟎𝟎% 𝐣𝐮𝐦𝐩 𝐢𝐧 𝐭𝐡𝐞𝐢𝐫 𝐂𝐖𝐈𝐏
To name some - #RegaalResources #OBSCPerfection #TemboGlobal #GemAromatics #SrmContractors #StallionIndiaFlouro #Solarworld #AlpexSolar #Kpenergy #Styrenix #BaluForge
Are you invested in any or any other names?


#Tembo #TemboGlobal #TemboGlobalIndustries
Tembo Global Industries Q3 FY26 Concall Highlights:
👉FY 2026 & Future Outlook :
▫️No explicit full-year FY26 revenue target was shared, but 9M FY26 already matching FY25's full-year revenues
💠Margins are expected to stabilize / improve slightly due to operational leverage
💠EBITDA margin target around 13-14% and PAT margins 9-10% for the year
💠For FY27: currently expect 35-40% revenue growth from FY26 levels, with PAT margins of 10-12%
👉Order book / projects and pipeline:
▫️Current order book : ~1420cr+ (execution timeline of 12-24 months)
▫️Engineering segment: Infrastructure-linked orders across land, water, marine, and industrial sectors
💠Recent completions include a fuel farm and marine jetty
▫️New Vasai facility: Commercial production commenced in Q3 FY26, scaling capacity from 18,000 MT to ~100,000 MT (phased over 2-3 years), with peak annual revenue potential of INR 700 Cr
💠Includes an in-house R&D center for product innovation and cost competitiveness
▫️Solar business: Land acquired across 24 sites, with the tranches of financing disbursed
💠Total project Capex ~INR 650 Cr, with PPA agreement with Maharashtra government for power sales over 25 years
💠Annual revenue potential ~INR 75-90 Cr post-commercialization (expected FY27), plus INR 110 Cr subsidy from government
💠Payback period ~5 years. Operating margins stable due to natural resource-based generation
▫️Defense manufacturing: Key regulatory milestones completed (land allotment, arms license approvals)
💠Machinery and technology transfer orders placed (~INR 20 Cr paid), with commercial production starting by Q3 FY27 (Sep-Oct 2026)
💠Tech transfer from Austrian firm (machinery + technology) expected by June-July 2026
💠Initial plant potential: INR 300 Cr annual revenue at full capacity (phased in 2-3 years), with FY27 revenue of INR 125-150 Cr (starting in H2 FY27)
💠EBITDA margins ~30-35%
💠Future expansions into second production line and ammunition with total Capex ~INR 1,000 Cr, with in-principle banker commitments
▫️Textiles Segment: Potential separation by FY27 for value unlocking, but positive outlook due to EU deal opening export opportunities; but nothing concrete mentioned as of now
💠Q3 revenue INR 121 Cr, with low but improving EBIT margins
👉Pipeline:
▫️Active discussions with a major corporate group for projects in port construction and fuel farm systems, representing an opportunity across civil, MEP, and HVAC works
💠Targeting an additional INR 700-1,000 Cr in total orders
👉 Others :
▫️Financial Updates: Raised capital via preferential allotment and warrants for liquidity
💠Board-approved merger of Tembo Infra with Tembo Global Industries filed with NSE
💠Working capital stable at 80-90 days, funded mainly by bankers (no major new equity dilution planned; promoters not selling shares)
💠No additional Capex planned beyond current projects (solar INR 650 Cr, defense INR 1,000 Cr, Vasai ongoing)
💠ROCE varies by vertical (not quantified overall)
▫️Other Operations and Strategy:
💠Vasai ramp-up to 90-100% utilization in 2-3 years, focusing on precision engineering products (e.g., pads and channels)
💠New products (ERW pads and channels) to commercialize in FY27, used in EPC and sold to existing clients (domestic margins higher than exports; exports ~13-15% of engineering revenue)
Last Seen Hashtags on Sotwe
Trends for you
Most Popular Users

Elon Musk 
@elonmusk
241.8M followers

Barack Obama
@barackobama
119M followers

Cristiano Ronaldo
@cristiano
114.6M followers

Donald J. Trump
@realdonaldtrump
111.9M followers

Narendra Modi
@narendramodi
107.2M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.4M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90.1M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.5M followers

Kim Kardashian
@kimkardashian
70.9M followers

YouTube
@youtube
68.8M followers

Neymar Jr
@neymarjr
66.5M followers

Bill Gates
@billgates
65.3M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.3M followers

CNN
@cnn
61.8M followers

X
@x
60.7M followers