

Top Tweets for #YASHOINDUSTRIES

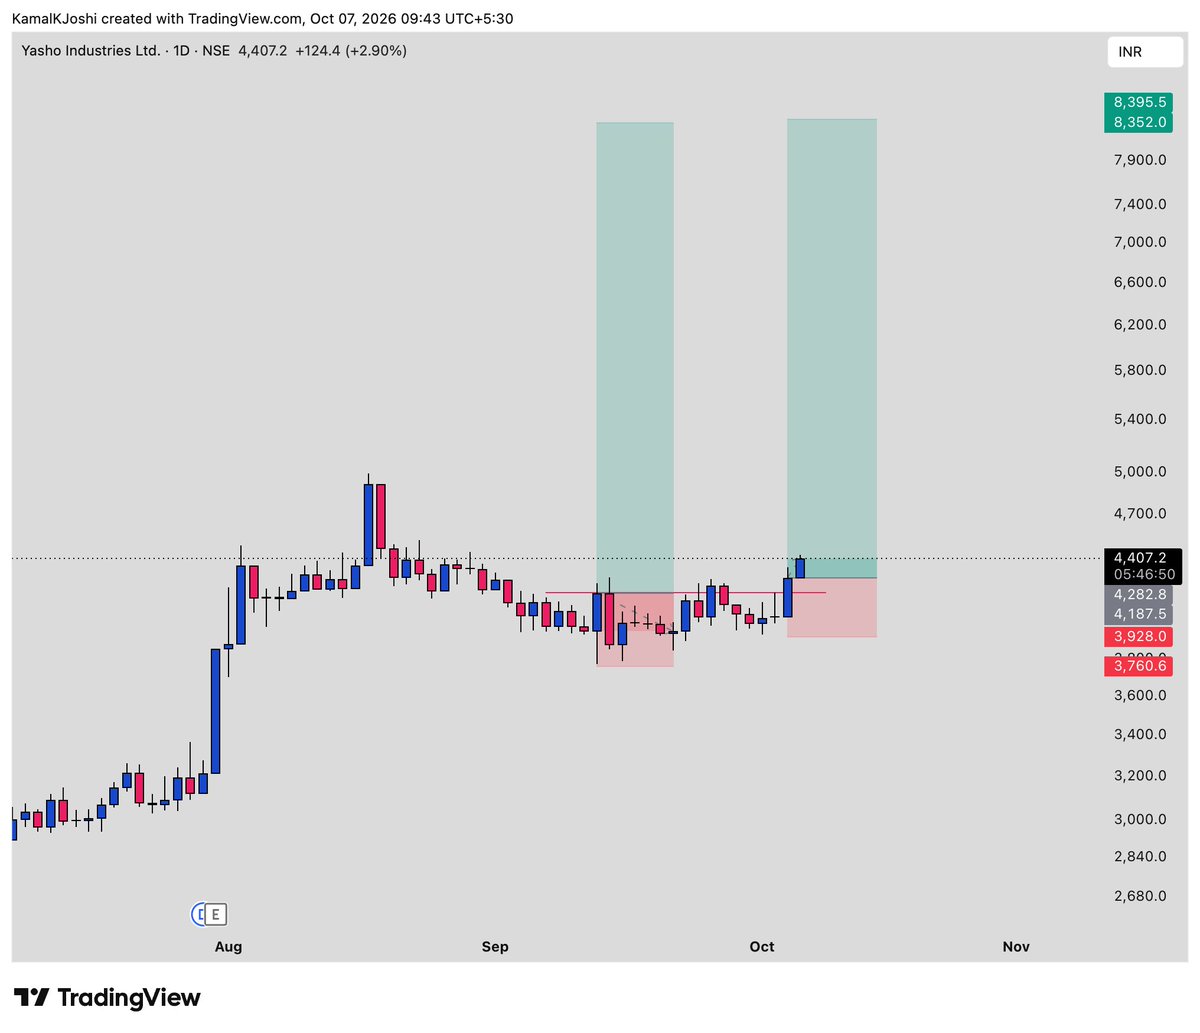
Yasho Industries | Clean daily structure.
Risk clearly defined. Position size controlled.Entered with strict rules —
Who’s tracking this one?
Drop a 🔥 if you’re in.#YashoIndustries #EquityChallenge #TradeUpdate #PriceAction #StockMarket #RiskManagement

#YashoIndustries
Yasho Industries Limited operates a highly specialized B2B specialty chemicals business model, designing and manufacturing custom organic additives divided into two core segments:
- Industrial Chemicals (rubber chemicals, specialized lubricant additives, and high-performance monomers)
[89% of total revenue]
- Consumer Chemicals (food antioxidants and complex aroma chemical compounds).
Exports contribute 69% of total revenue,
Market Attractiveness:
Demand-side: The global chemical market is experiencing robust structural demand tailwinds as multi-billion-dollar global corporations adopt "China+1" sourcing strategies to diversify supply lines. This macro shift moves high-volume, multi-year contracts directly to high-compliance Indian chemical players.
Supply-side: Entry is constrained by heavy regulatory barriers and long customer validation loops, shielding established players from rapid price erosion by low-tier commodity chemical suppliers.
⚙️ Operating Value Drivers & Financial Blueprint
1. Sales Growth
Volume & Capacity Scaling: Volume growth is backed directly by the scale-up of the Pakhajan greenfield site. This facility provides an additional 20,000 MTPA capacity on top of the original 11,000 MTPA Vapi plant (which runs near its peak revenue ceiling of ₹650–₹700 crore).
Management's near-term guidance targets a ~75% overall capacity utilization for FY27, moving toward an optimal 85%–90% benchmark over the next 2–3 years. This step-up in physical production supports management's projected 30%–40% annualized revenue growth rate.
Price, Mix & Order Book Stability: Realized pricing has stabilized, and the product mix has structurally pivoted to the higher-value Industrial segment. This sales trajectory is protected by a sticky order book, with over 50% of the active order book secured under long-term contract frameworks that include raw material index pass-through formulas. Over the next 2–3 years, revenue growth is anchored by a 15-year supply agreement for specialized lubricant additives starting in Q4FY27. This contract is structured to add an incremental ₹150 crore to annual revenue once fully operational.
Financial Impact: These factors support the company's trajectory toward its stated FY28 revenue target of over ₹1,600 crore, a significant step up from the record ₹308 crore quarterly baseline established at the start of FY27.
2. Operating Profit Margin
Operating Leverage: Between FY22 and FY25, heavy capital expenditures weighed down net earnings due to fixed depreciation and interest costs before the assets were fully productive. In FY27, fixed plant operating expenses are being spread across a much larger production volume.
Financial Impact: EBITDA reached ₹74.42 crore, causing the EBITDA margin to expand to 24.2% from 17% in the prior year. Management noted that this ~24% margin threshold is sustainable due to contract structures and volume stability.
3. Reinvestment Rate
Economies of Scale & Future Capex: Reinvestment efficiency is driven by the physical layout of the Pakhajan hub, which has a peak asset revenue-generating potential of ₹800–₹850 crore under its current configuration. Because the core shared utilities are already in place, Yasho can expand its manufacturing lines at a lower marginal cost. This efficiency gave management the confidence to double its planned FY27 capex to ₹250 crore to build two new production buildings (Phase 1 operational by Q1FY28, Phase 2 by Q4FY28).
Working Capital: Execution risk for this new capital deployment is low because ~65% of this upcoming capacity is already pre-booked by global buyers. Capital efficiency is further supported by a compressed working capital cycle, which dropped from 190 days to 143 days, and a reduced Net Debt-to-EBITDA ratio of 1.86x (down from 3.75x)
🚀 The Compound Impact on EPS (With Forward Estimates)
[ REVENUE EXPANSION ]
FY27 Revenue Trend: ~₹1,200Cr
FY28 Target: >₹1,600Cr
EBITDA Margins: ~20%-22% (Spreading Fixed Costs)
==> [ ACCELERATED Inflection in Net Profit Margin ]
FY27 Specifically: The single-quarter performance of ₹29.90 EPS highlights the business's potential during periods of high-margin product mix. Based on management's guidance of ~75% capacity utilization and a conservative full-year stabilized EBITDA margin of 20%–22% (accounting for product mix shifts), estimated full-year FY27 EPS sits in the range of ₹95 to ₹105. This represents an inflection point as asset utilization catches up to the company's fixed cost base.
Next 2–3 Years (FY28–FY30): As the ₹250 crore capex lines come online and the 15-year MNC contract ramps up, asset utilization is projected to reach 85%–90%. Spreading fixed costs across a larger base while maintaining structural EBITDA margins helps drive net profitability. Assuming the company hits its guided revenue target of over ₹1,600 crore by FY28 with stable margins, projected FY28 EPS rises to a range of ₹145 to ₹160
Moat: Yasho's business model is difficult to replicate because of its multi-year global client validation cycles and long-term supply contracts that tie multinational buyers directly to its manufacturing footprint.
[Not investment advice, DYOR]
[EPS modelling based on management guidance and positive execution assumptions]

#YASHOINDUSTRIES
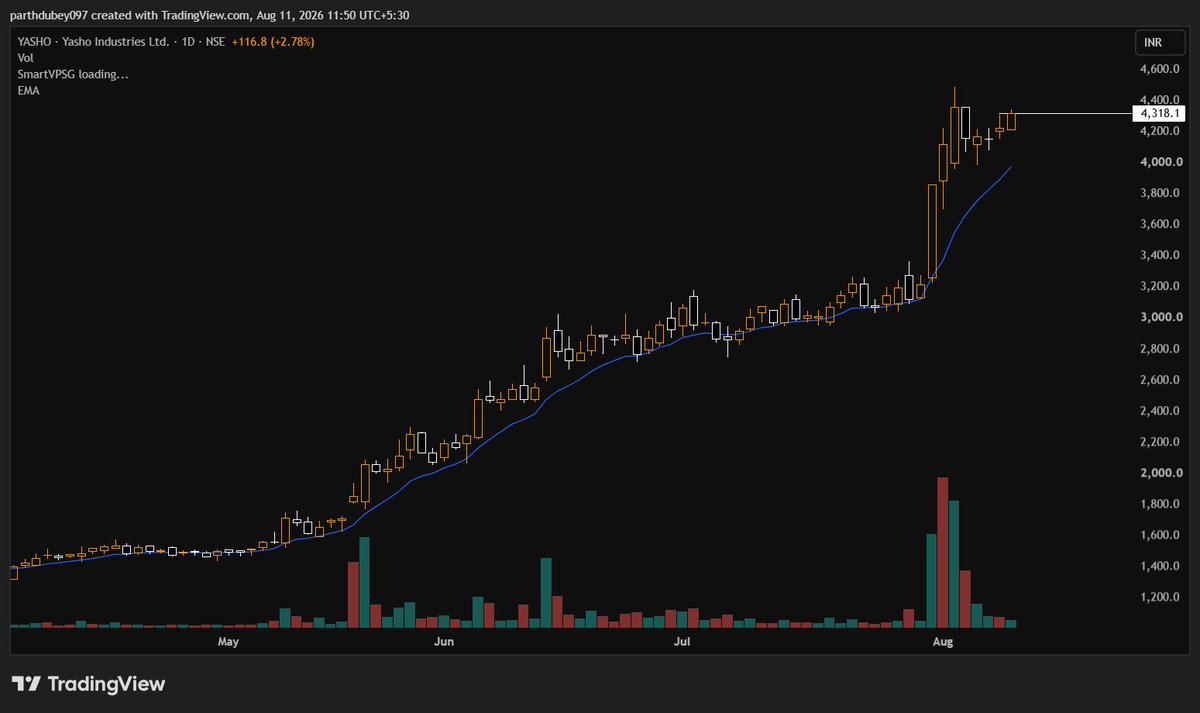
Took Pilot entry in this one at 4338
SL: 2% from entry
Not a Buy/Sell Recommendation

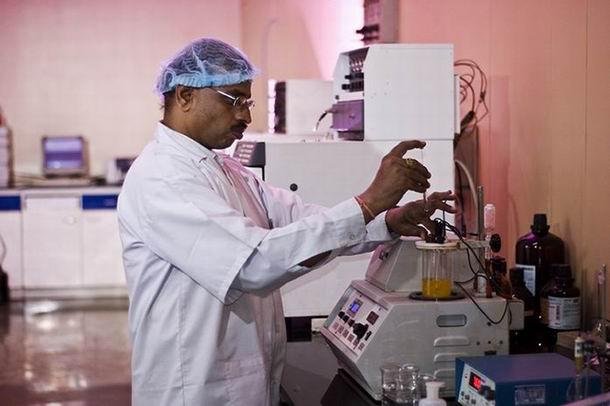
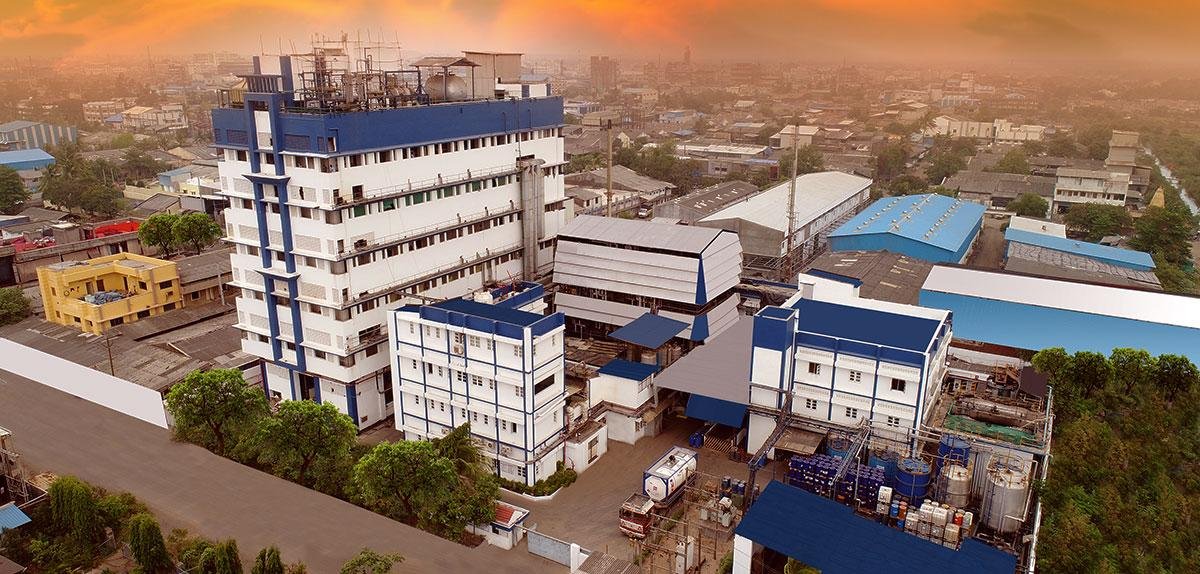
#YashoIndustries is a specialty chemical company that manufactures high-value chemicals used in a wide range of industries, including tyres, lubricants, fragrances & perfumes, food ingredients, plastics, and other industrial applications. Unlike commodity chemical manufacturers, it focuses on niche products where customer relationships, technical expertise, and product quality play a much bigger role.
The company has spent the last few years investing heavily in a large greenfield manufacturing facility. While this temporarily hurt reported profits due to higher interest and depreciation costs, that investment phase is now largely behind it. The focus has shifted from building capacity to utilizing it.
The growth story now revolves around ramping up production from the new plant, improving operating leverage, and expanding supplies to global customers. As plant utilization increases, fixed costs get spread across higher volumes, which has the potential to drive earnings growth much faster than revenue growth. Another encouraging sign is that a leading multinational customer has provided an advance payment to support future capacity, indicating confidence in Yasho's long-term manufacturing capabilities.
For investors, this is an execution-driven story. If management successfully fills the new capacity, continues adding export customers, and keeps improving margins while reducing debt, the next few years could look very different from the recent past. It's a business worth tracking closely as it transitions from a heavy investment phase to a potential earnings expansion phase.

#YashoIndustries Ltd Created a New 52Week High of 4250.00 on #NSE & 4242.95 on #BSE Today
#StockToWatch
#StockInNews
#StockInFocus
#StockMarket
#Nifty #NSE #BSE #Nifty50 #Sensex

15 . Yasho Industries Ltd 🔖
#yashoindustries


#YashoIndustries delivers a blockbuster #Q1 FY27
✅ Revenue: ₹308 Cr (+55% YoY)
✅ EBITDA: ₹73 Cr (+118% YoY)
✅ PAT: ₹36 Cr (+890% YoY)
✅ OPM: 23.8% (vs 16.9% YoY)
One of the strongest quarters in the specialty chemicals space. 👀
#Stocks #SmallCap #StockMarket
The stock still trades at a premium valuation after the rally.
That means the market is already pricing in a lot of future growth.
Watchlist worthy for long-term investors. 🚀
#YashoIndustries #SmallCap #SpecialtyChemicals #StockMarket #Investing

#yasho #yashoindustries #aromachemicals
Craziest returns in the last 3 months, to my surprise very few finfluencers covered it 🫢.
Moved from 1529 to 3858 in just matter of two months.
#study #vismaya #StockInFocus


Yasho Industries Q1 FY27 Results 📊
✅ Revenue: ₹307.74 Cr
📈 +54.9% YoY | +25.0% QoQ
✅ PAT: ₹36.05 Cr
🚀 +889.2% YoY | +194.1% QoQ
A stellar quarter for Yasho Industries, with strong revenue growth and an exceptional jump in profitability.
#YashoIndustries #Q1FY27 #QuarterlyResults #Earnings #StockMarket #IndianStockMarket #ResultsUpdate #Investing #Stocks #MoneyPurse
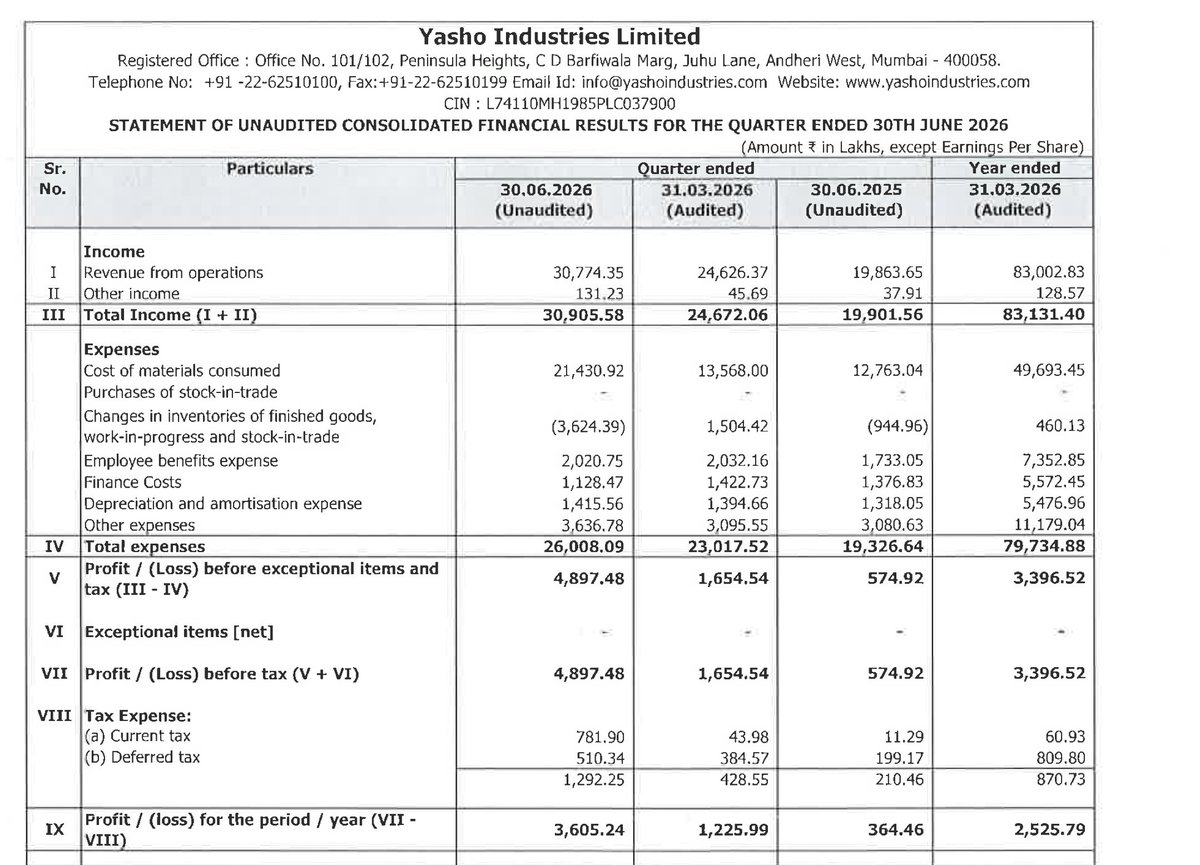

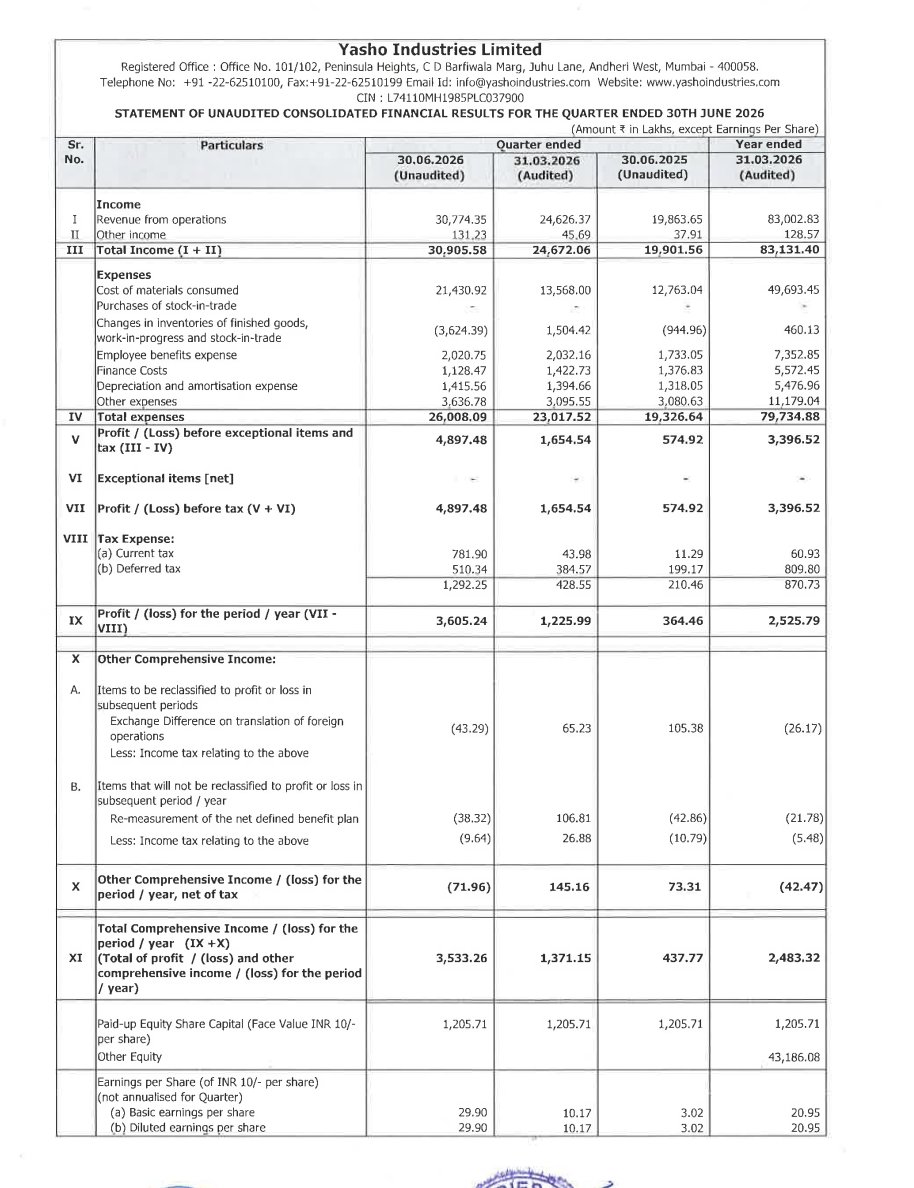
#YashoIndustries Mcap 4657 Cr
Revenue growth: 54.93% YoY
PAT growth: 889.2% YoY
OPM: 23.75% vs 17%
#PrudentIdea by @PrudentParrot
Stock jumped 20% post earnings release 🙏
Disc: No buy/sell recommendation.
#YashoIndustries Mcap 2000 Cr
Exceeded guidance of 800 Cr in FY26.
Opm: 17.2%
151 Cr OCF 🔥
Debt came down slightly.
Should come out of 4.5 years of time correction now.
Disc: No buy/sell reco.

5 . Yasho Industries Ltd 🔖
#yashoindustries
⭐Change In Holding % [ From Mar 2026 to Jun 2026 .]
🚀Change In Promoters Holding ~0.03 %
🚀Change In Dii Holding ~0.24 %
🚀Change In Fii Holding ~0.04 %


#YashoIndustries Mcap 2000 Cr
Exceeded guidance of 800 Cr in FY26.
Opm: 17.2%
151 Cr OCF 🔥
Debt came down slightly.
Should come out of 4.5 years of time correction now.
Disc: No buy/sell reco.

@Manojeet_Das 2. Yasho Industries
https://t.co/wfJeOxIKn6
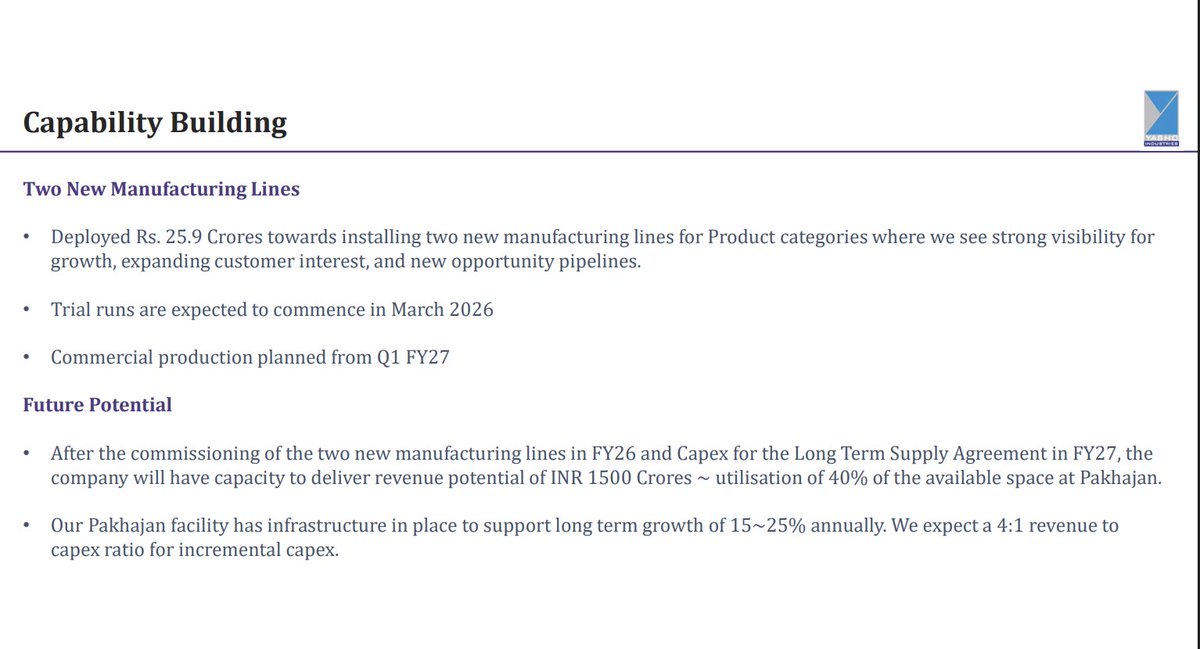
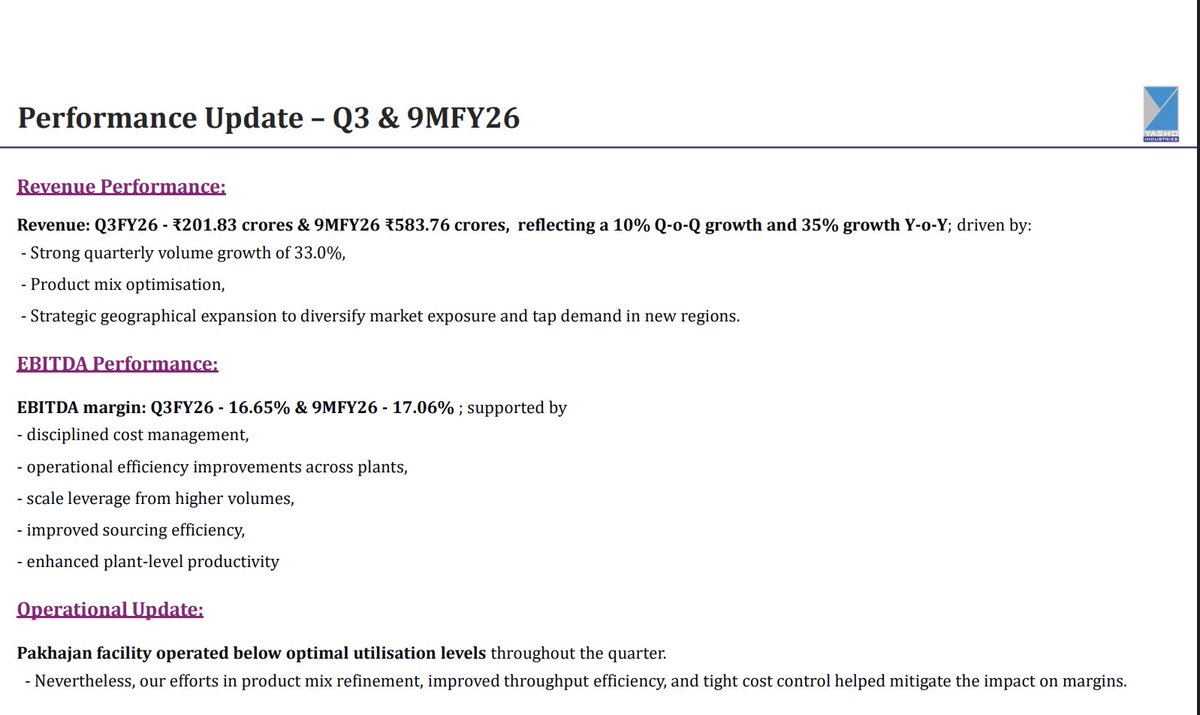
FY26 should end at around Rs. 800 Cr. They have an aspirational target of achieving Rs. 1500 Cr in FY28 with an EBITDA margin of 17%-19%
The NDA signed with a large customer funding the project cost of Rs. 90 Cr is for a new molecule



Yasho Industries Limited Q4FY26 Results:-
#Q4Results #Q4FY26 #Stockmarket #Nifty #YashoIndustries
Revenue 246.26 Cr vs 184.81 Cr
(+33.25% YoY┃+22.02% QoQ)
EBITDA 44.26 Cr vs 35.50 Cr
(+24.69% YoY ┃+32.23% QoQ)
EBITDA Margin 17.97% vs 19.21% YoY & 16.59% QoQ
PBT 16.55 Cr vs 8.03 Cr
(+106.05% YoY┃+192.04% QoQ)
PAT 12.26 Cr vs 5.03 Cr
(+143.72% YoY┃+172.68% QoQ)
Other Income 0.46 Cr vs 0.64 Cr YoY & 0.15 Cr QoQ


📊 YASHO IND Q4 Cr: Rev ~₹11.3K, EBITDA ~₹4.9K.
🚀 Segment Profit: Rubber 36.2%, Specialty 56.2%.
📉 Net Debt ~₹2.0L Cr, Cash ~₹3K Cr.
📈 Order Book bars: Capacity & Export growth strong.
#YashoIndustries #Stocks #SpecialtyChemicals

#YashoIndustries Mcap 1680 Cr
One pager made using Claude.

#YashoIndustries is at $90M in revenue.
Their addressable market? $20 Billion.
Here's the story of a specialty chemical company that's been playing the long game for 30 years and why the runway is just beginning. 🧵

#YashoIndustries is at $90M in revenue.
Their addressable market? $20 Billion.
Here's the story of a specialty chemical company that's been playing the long game for 30 years and why the runway is just beginning. 🧵
Posted November month #PrudentIdea
Read here: https://t.co/wfJeOxIKn6
It takes a lot of time and energy to study a business in detail, draft it, and bring out differentiated insights that others might miss, and we do this every month 😊
Subscribe here: https://t.co/RIqZxDRnMD

Yasho Industries Q3 FY26 Concall: Pakhajan Ramp-up and Specialty Chemical Expansion #yashoindustries #q3fy26 #chemicals #concall
https://t.co/QNZbyXjSEL

TOP ANNOUNCEMENT FOR THE DAY!!
#YashoIndustries: The company has signed a long-term agreement for a period of 15 years with a global MNC for the supply of a lubricant additive worth Rs 150 crore per annum, starting at the end of FY27.
#RPPinfraprojects: The Company has secured a contract of Rs 134.21 crore for EPC KN-II 5A Improvement of Matheran Neral Kalamb road, Raighad, Maharashtra.
#ITILimited: The Company has secured Rs 110 crore empanelment from GIPL for IT infrastructure and cybersecurity projects in Gujarat.
#jaybeelaminations: The Company has secured a contract of Rs 94.86 crore from ABI Energy Solutions for the transmission and distribution line in Haryana.
#indotech: The company has received a Purchase Order of Rs 78.39 Crore for the supply of 9 Nos—125 MVA transformers from Avaada Clean Project Private Limited.
#Univastu: The Company secures work order of Rs 22.89 crore from M/s Super Construction Company, Nagpur for ‘Construction of World Aquatics compliant, Olympic Standard.
#AkashInfra: The Company has secured an order worth Rs 13.73 crore from the Office of the Executive Engineer, Capital Planning Department ,Gandhinagar.
#Agnigreen: The Company has received a work order of Rs 1.04 crore from Jagdamba Enterprises Pvt. Ltd (NEPAL) for Grid Connected Roof Top Solar Power Plant.
Most Popular Users

Elon Musk 
@elonmusk
241.5M followers

Barack Obama
@barackobama
118.8M followers

Cristiano Ronaldo
@cristiano
114.6M followers

Donald J. Trump
@realdonaldtrump
111.8M followers

Narendra Modi
@narendramodi
107.1M followers

Rihanna
@rihanna
98.7M followers

NASA
@nasa
92.3M followers

Justin Bieber
@justinbieber
91.8M followers

KATY PERRY
@katyperry
90M followers

Taylor Swift
@taylorswift13
84M followers

Lady Gaga
@ladygaga
75.5M followers

Virat Kohli
@imvkohli
73.5M followers

Kim Kardashian
@kimkardashian
70.9M followers

YouTube
@youtube
68.8M followers

Neymar Jr
@neymarjr
66.5M followers

Bill Gates
@billgates
65.3M followers

Selena Gomez
@selenagomez
63.1M followers

The Ellen Show
@theellenshow
62.2M followers

CNN
@cnn
61.7M followers

X
@x
60.7M followers