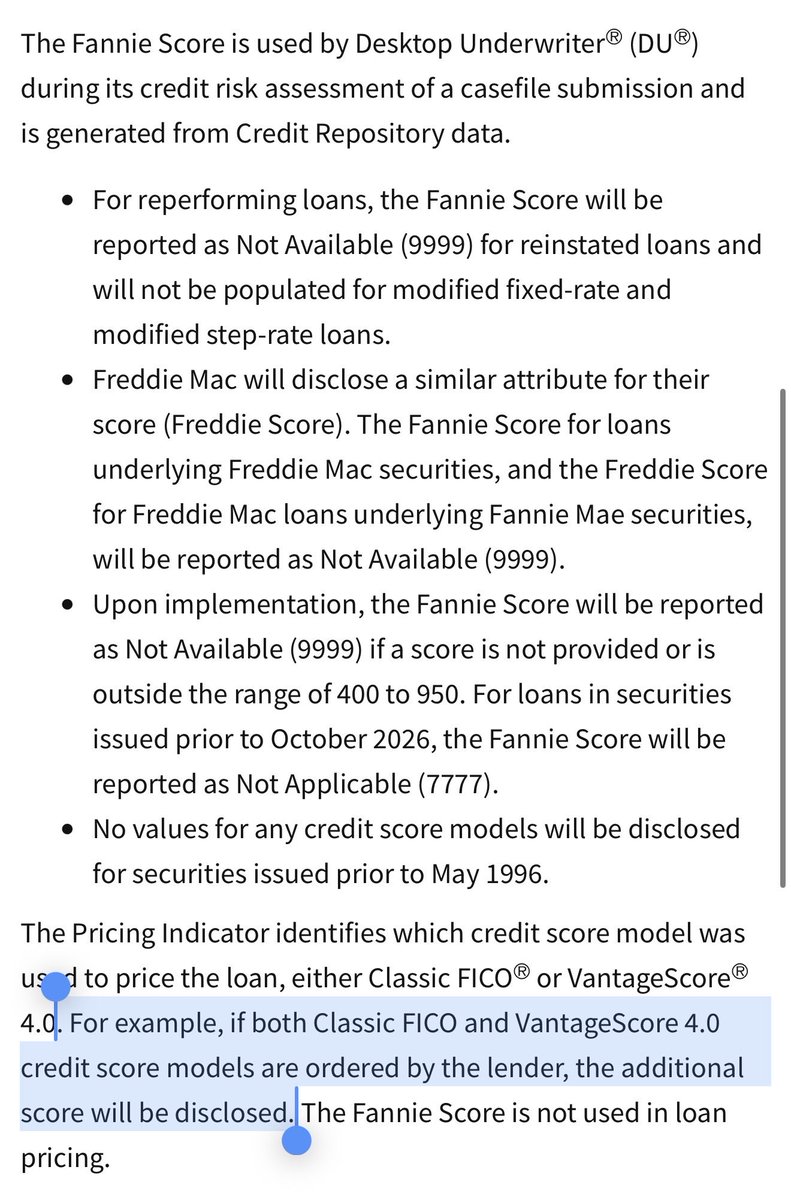
This is effectively duel scoring. Congrats lenders, you can underwrite loans with Vantage and not face a secondary market penalty. The catch is that you just have to pull the FICO scores in the tri-merge report. $FICO
@HomeLoanBill That’s rough since Vantage is suppose to act like an option that could hopefully improve LLPA fees for borrowers. Needs to be substantial though since all else equally, Vantage loans get 25-30bps lower GOS.
@Iamheartthrob@pulte This MBS security only shows what the lender decided to send the GSE, not what score they paid for (they’re pulling both). The biggest losers of lender’s choice are the GSEs who get lower insurance premiums. The biggest winners are the 720 FICO borrowers that have a 800 Vantage.
@1gregsher@onlinemoney8@pulte@VantageScore Thanks for your input Greg. I wonder if the MBA will eventually be okay with a duel scoring mandate, but only two bureaus. Btw, keep up with the great podcasts.
@ValleyForgeCap Areas where Vantage Score could be penalized relative to $FICO resulting in higher rates for mortgage borrowers:
1. MBS investors concerned about prepayment risk.
2. Banks who hold loan loss reserves.
3. Lenders who hold repurchase reserves.
4. Private mortgage insurance.
@1gregsher@pulte@VantageScore Greg, this is exactly what’s happening. Lenders can criticize FICO pricing, but their prepayment data and common risk language is worth a lot of money to Wall Street.
@cloneinvestor This does not appear to be the case. It makes sense that a fair LLPA grid for Vantage would demand higher scores since the distribution of scores for Vantage tend to be hire. Per Milliman:
@cloneinvestor First let me just say there’s no one to one mapping. The FICO - 20 is a *reasonable* mapping. The reason I said this is a sigh of relief is because the FHFA could have, for whatever reason, made the LLPA grid such that more home buyers getting a lower LLPA fee with Vantage.
@DeepIceValue It’s up because the Vanatge Score LLPA grid dropped and it’s not inherently favorable to Vantage Score. It’s basically treated as Classic FICO - 20. That’s was one way for the FHFA to massively screw FICO and it didn’t happen.
@SubprimeCap That they are. However, only an MBS trader or an aggregator selling the MBS would know. This doesn’t really matter since any hedging team worth their salt would price pricing disparities at the loan level.
@SubprimeCap Idk what you mean by spread compression. There is a spread and it will likely persist for some time… years at least. The spread exists on loans coming from the same lender. As for commingling loans inside MBS, I would guess…
@RobTVDC@dayetweets@pulte Which credit score has 25+ years of prepayment behavior behind it? Only one. The accuracy of the probability of default is not a big concern since agency MBS has basically no credit risk. Prepayment modeling is what everyone cares about. Cheers 🍻