Hot take time:
AI compute should be priced like:
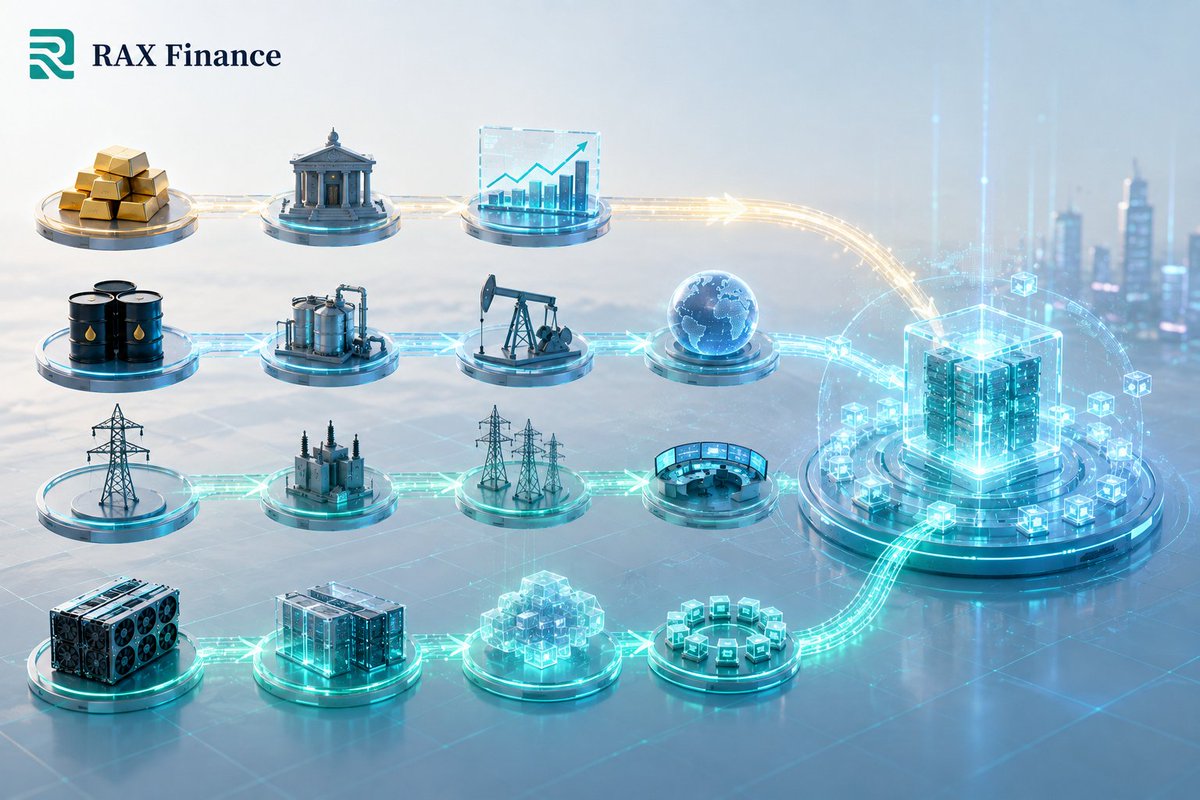
A) Oil — global commodity, single benchmark (WTI/Brent model)
B) Electricity — regional grid, locational pricing (LMP model)
Reply with A or B + your reasoning.
We're clearly Team B (hence building regional indices), but curious what you think.
Especially want to hear from folks who disagree 👀
Friday check-in 👋
What’s caught your attention in AI compute this week?
A new GPU, a data centre trend, or the future of ComputeFi?
We’re curious what the Rax community is following. Drop your thoughts below 👀
Compute is being planned on a multi-year horizon.
Chipmakers are already securing EUV tools for 2029 and 2030.
ASML says customers are asking for more machines every day, even as 2027–2028 capacity expands.
The industry is locking in the manufacturing base for the next wave of AI capacity years in advance.
Via @wallstengine
📊 Open question for the compute market:
By the end of 2027, what % of APAC third-party GPU capacity will be traded on secondary markets rather than remain locked in long-term contracts?
We’re talking about neoclouds and independent operators, excluding hyperscaler self-use. Secondary trading includes unused or residual contracted capacity changing hands.
Our working hypothesis: 15–25%.
Why?
• Multi-year take-or-pay contracts still dominate, with limited early-exit options.
• Secondary trading is emerging, but liquidity, standardisation, and counterparty trust are still developing.
• As market infrastructure matures, more unused capacity could find a second buyer.
What’s your prediction, and why? 👀
Let’s revisit this in 12 months and see who got closest.
Scenario:
You sign a 12-month GPU contract for $2.5/hr.
3 months in:
• Your project pivots and needs a different region
• Your original contract still has 9 months left
• You're locked in, paying $216K for ~13 GPUs you can't use
What would you want?
A) Transfer the contract to someone else
B) Redeem it for other compute (different region/model)
C) Eat the cost — that's business
D) Something else? Tell us below.
💬 Reply with your choice + RAX Finance Waitlist address.
🎁 We’ll reward great answers with 5 Unboxing Opportunities!
🔗 https://t.co/blgzDVUsow
Why regional compute pricing matters: the financing gap no one is talking about
AI infrastructure spend is exploding — but ownership structures differ sharply by region, and that gap is showing up in financing costs.
Exactly.
The bottleneck is connecting power, construction, equipment, and cloud capacity on one timeline.
The suppliers and operators determine whether a site gets built quickly or stays stuck in the queue.
Compute capacity creates most of its value only after it’s online and serving demand.
Why compute pricing lacks regional benchmarks:
Observation 1: Massive regional spreads
Same H100 card, wildly different economics across markets
Not 10-20% differences — we're seeing 2-3x spreads
Driven by: power costs, export controls, demand concentration
Observation 2: No one publishes regional clears
Cloud marketplaces show listing prices (not actual trades)
Real contracts are confidential bilateral deals
Lenders can't price risk without a settlement benchmark
Observation 3: This is exactly where electricity was in the 1990s
Before ISOs started publishing Locational Marginal Prices
Before you could hedge regional basis risk
Before financing could scale
RAX is building the missing layer: regional price discovery for compute.
Not because it's novel (electricity solved this 30 years ago)
But because compute is $180B annual spend with zero pricing infrastructure in Asia/MENA.
That's the gap we're closing.
The compute market is at the stage where:
• Electricity was in the 1990s (before deregulation)
• Oil was in the 1950s (before posted prices → spot markets)
• Carbon credits are today (trading exists, but fragmented)
We're watching commodity infrastructure form in real-time.
What we're building: https://t.co/atMVIN7M2v
$40B, just to buy the chips.
SpaceX is lining up Apollo-led financing for Nvidia capacity: about $10B in bank loans and $30B in investment-grade debt, aimed at Vera Rubin.
It is a compute purchase large enough to be financed like infrastructure.
Power, land, and chips are now the constraint.
The market is underwriting the factory, not the demo.
Via @wallstengine
Three things every commodity market needs:
1. Fungible units
Gold: 1 oz = 1 oz anywhere
Compute: every contract is unique ❌
2. Price transparency
Oil: WTI, Brent published daily
Compute: real deals are confidential ❌
3. Tradeable infrastructure
Electricity: day-ahead markets exist
Compute: can't resell a signed contract ❌
That's the gap we're closing.
More on commodity formation: https://t.co/atMVIN7M2v
To everyone who’s been waiting with us — we hear you. 🤍
We know many of you have been on the Waitlist for a while, and we truly appreciate your patience.
We’re now moving deeper into ComputeFi, with discussions already underway for our first batch of idle compute partnerships.
And yes — your community points still matter. Holding an NFT will not only come with its own benefits, but also boost your community points.
We’re getting closer, and there’s more to share soon!
Thank you for staying with us!
We’re building this with you!
Compute is being contracted like capacity, not bought like hardware.
Oracle is selling Tencent access to ~100,000 advanced chips over 5 years, about $7B, with ~30% paid upfront.
Broadcom is lining up as much as $42B of financing against Anthropic’s multi-year compute commitment.
Nebius is buying inference tech so GPUs spend less time idle.
That is the real market:
power, chips, utilization, and who is willing to prepay for the output.
The scarce layer is still compute.
Compute capacity is shifting east.
East Asia: Semiconductor and data centre expansion
Southeast Asia: Power + connectivity advantages
India: Scale + cost efficiency
MENA: Capital meets ambition
Infrastructure is growing fast.
But pricing transparency? Still catching up.
Building a more transparent and accessible compute market is exactly what @RaxFinance is working toward.
The listed price is not the traded price.
Public marketplaces show H100 at $3.25/hr.
Real year-long contracts clear at $2.10–2.70.
Why the gap?
Bilateral negotiations are confidential.
Nobody publishes what actually traded.
Price discovery needs transparency.
🔗 Join the Waitlist: https://t.co/LuaHr8A0uT
The debate on AI compute has moved.
From "will demand exist?"
To "do the unit economics work?"
GPU pricing, financing costs, utilization.
Contracted power, density, offtake.
A 1GW factory only works if it can be rented, powered, and paid back.
Some names are being marked down on returns.
Others are being marked up for contracted power, density, and long-term offtake.
The market is underwriting compute like real assets now, not like a theme.
Via @wallstengine
BlackRock: AI compute could be tokenized.
Translation:
compute is about to get a market.
The world’s largest asset manager just named the future.
We’re building the unit it needs.
1 cT = 1 GPU-hour.
Fungible. Redeemable. Tradable.
That’s the layer.
A founder's dilemma:
"Signed 12-month GPU contract.
Raised $2M seed.
Built for 3 months.
Funding talks fell through.
Now: 9 months left on contract.
$27K/month burning.
Can't resell. Can't transfer.
Just... stuck."
This isn't rare. This is Tuesday in AI.
🛠️ Builder’s Note #01
An index without a pool is a number nobody can transact on.
A GPU cloud without an index is capacity nobody can price.
@RaxFinance is building all three:
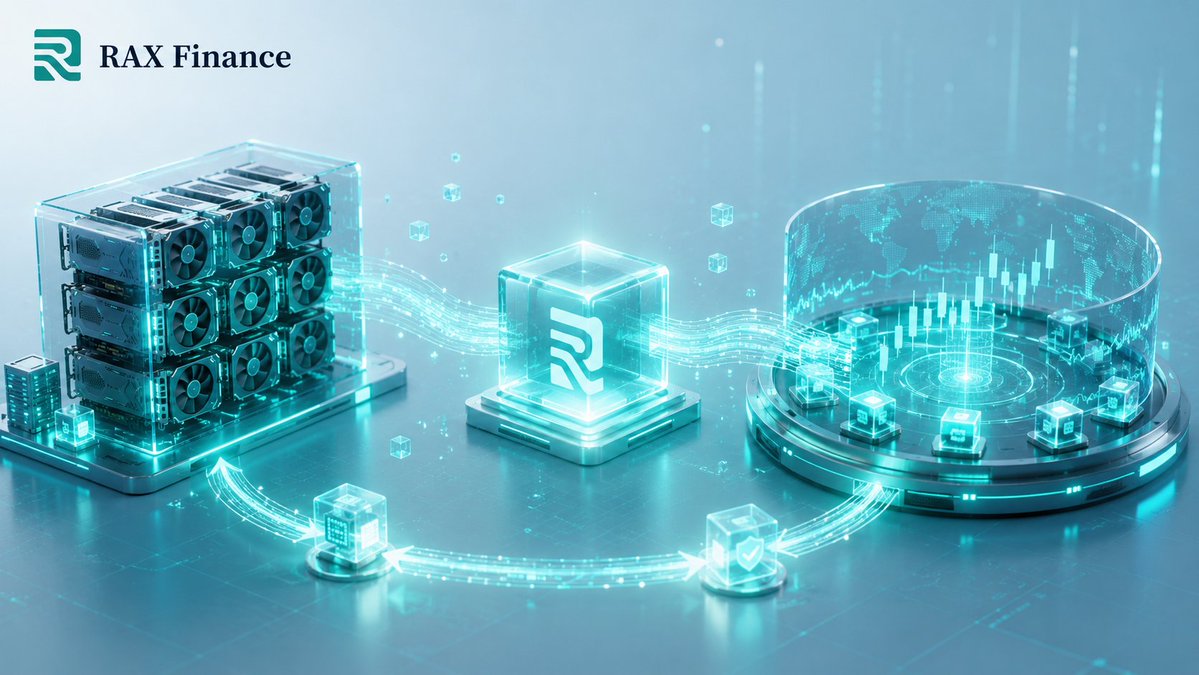
✓ The machines — custodied in partner data centres
✓ The unit — cT, backed 1:1 by those machines
✓ The venue — where cT can actually clear
One place where GPU compute is:
Minted → Priced → Traded → Redeemed
A benchmark, once referenced, becomes a market standard.
🔗 Join the Waitlist:
https://t.co/0sXOt71OLm
💬 Drop your address below.
🎁 Surprise Unboxing Opportunities await.