It’s happening.
r/wallstreetbets is currently plastered with $MSTR gains.
Broader retail is gaining awareness of MicroStrategy as its anticipated NASDAQ 100/QQQ inclusion approaches.
Looks like a buy-side tsunami is brewing.
The former CEO of Sotheby's, Tim Smith. It is is job to know value. He retired and studied Bitcoin and the economy we have just been in.
Please I urge you to understand as Bitcoin goes from $76,000 to $1,000,000 and beyond.
Take 2 minutes to change your family future.
🇯🇵🌎Black Monday 2024
Japan stocks worst day since Black Monday 1987 today on Black Monday 2024
At 15:00 Japan cash close:
🇯🇵NKY -13.5%
🇯🇵TOPIX -12.2%
🇰🇷KOSPI -9.5%
🇦🇺ASX200 -3.7%
🇭🇰Hang Seng -2.37%
🇺🇸NDX Futures -5.6%
🇪🇺SX5E Futures -2.7%
🇯🇵10Y JGB Yield 0.75% (-20bps!)
🇺🇸10Y UST Yield 3.62%
USDJPY -3.2%
MXNJPY -7.25%
AUDJPY -4.36%
CNHJPY -2.45%
BTCJPY -18%
Japan equities breakdown:
🇯🇵TOPIX Index Sectors
Best: Air Transports -6.7%
Worst: Banks -17%, Insurance -17%
Most traded notional volume (other than 1570 NKY225 levered ETF -20% on the day):
•MUFG -18%
•Tokyo Electron -19% (A.I. / semis play)
•Toyota -13%
So no, this isn’t a “tech sell off” (only) - banks, autos, everything down (literally so- very NKY225 stock ↓)
NKY Volatility Index: 30 (usually hovers around 16~19, opened today at 21)
Why do Japan equities matter? Because it was the near unanimous consensus favorite among global allocators, and its massive outperformance vs other DM indices (yes including the “magnificent 🇺🇸”) was almost purely FOREIGN CAPITAL (UK, US, Asia-ex🇯🇵) driven. In other words, it’s capital from your region (wherever you are, DM folks) that’s getting indiscriminate force-sold.
Which means that we may even see repatriation of those flows out of Japan and into U.S./STOXX (not to say 🇺🇸🇪🇺🇬🇧↑, but less bad vs 🇯🇵/Asia).
And last point, if anyone thinks this is all due to a single 🇺🇸jobs print…
A) You’re probably (a fellow) American.
B) This current chapter of the 🇯🇵 equity bloodbath acceleration was pre-Friday🇺🇸jobs data. NKY 8/1: -2.5%, 8/2 (pre-🇺🇸data) -6%, & no single piece of backwards looking 🇺🇸 data is going to shed -13% off a major index with intraday trading halts.
C) I discussed with @leadlagreport earlier today - I would advise to watch my mid-trading day discussion where I address the massive delta between US domestically focused capital vs internationally aware capital - and that means (our) alpha at your (🇺🇸-only watchers’) expense. For example -do you know what Japan NISA is?
If the answer is no, AND yes, you need to know/watch.👇
https://t.co/0rmejbQaMc
https://t.co/xh2pxHLKe1
my jaw dropped after listening to this segment
@fundstrat is the elon musk of equities
his first principles thinking that’s fused with contrarian views and horizontal + vertical depth of analysis is truly unrivaled
here’s his take on S&P earnings going into the end of the decade, and how AI and demographics play into his thesis
just OUTSTANDING.
I was buying Sol at $30 and when it pumped to $173 I sold half of my 172 sol to buy a 2012 Mercedes. The Mercedes ended up being in bad shape and needed a lot of work. Pretty much wasted half of my profit on a piece of garbage.
Norinchukin, which holds 20% of all foreign bonds held by Japanese banks, is starting a firesale to plug its 2.2 trillion yen in unrealized losses because in Japan they don't have a BTFP facility.
The US isn't going to to default on its debt. They're going to make treasuries worthless so everyone will be forced dump them for Dollars
Then they simply print when there's a global Dollar shortage, buy all of the worthless treasuries & take them out of circulation
Great Reset
As Australia and New Zealand Banking Group (ANZ), one the world’s largest global banks with over $1 trillion in total assets under management, demonstrates the use of CCIP for secure cross-chain stablecoin transactions, the role of Chainlink and CCIP as a standard for interbank transactions for stablecoins and tokenized real world assets is becoming a reality: https://t.co/nONl4L0cfK
Acid Capitalist Telling It As It Is
Q: Thoughts on the UK, Gilts...
A: This is a spinning wheel of death
Haven't found time to collect my thoughts
But, briefly...
85% of the UK mortgage market is fixed rate
And 40% of that is gonna reset next 18 months
This is 2007 all over again
This is a brick on a sling...
The teaser is gonna reset the UK into bankruptcy
And inflation...
UK a basket case ?
Yes, to the latter
But UK was most dependant EU nation on gas as the principal feedstock
This energy shock much greater than the 1970s
Yet CPI peaked at 40% of the 1970s level
And the subsidised energy tariffs only started falling last week
No monetary policy could have prevented this CPI
None
With 20/20 vision, quant models suggest that
If BoE had raised rates to 7% this time last year
And hiked further to 9% by now
The CPI print would've been almost identical
Maybe 2 points lower
But you'd still all be bitching
Inflation is a monetary phenomenon
The UK hasn't had an out of control money expansion
This is horrible crowd delusion
This is a weak central bank gunning their reputation
Fending off criticism from the basic lack of understanding in markets
This is what happens when only 5 people in the world properly understand money...
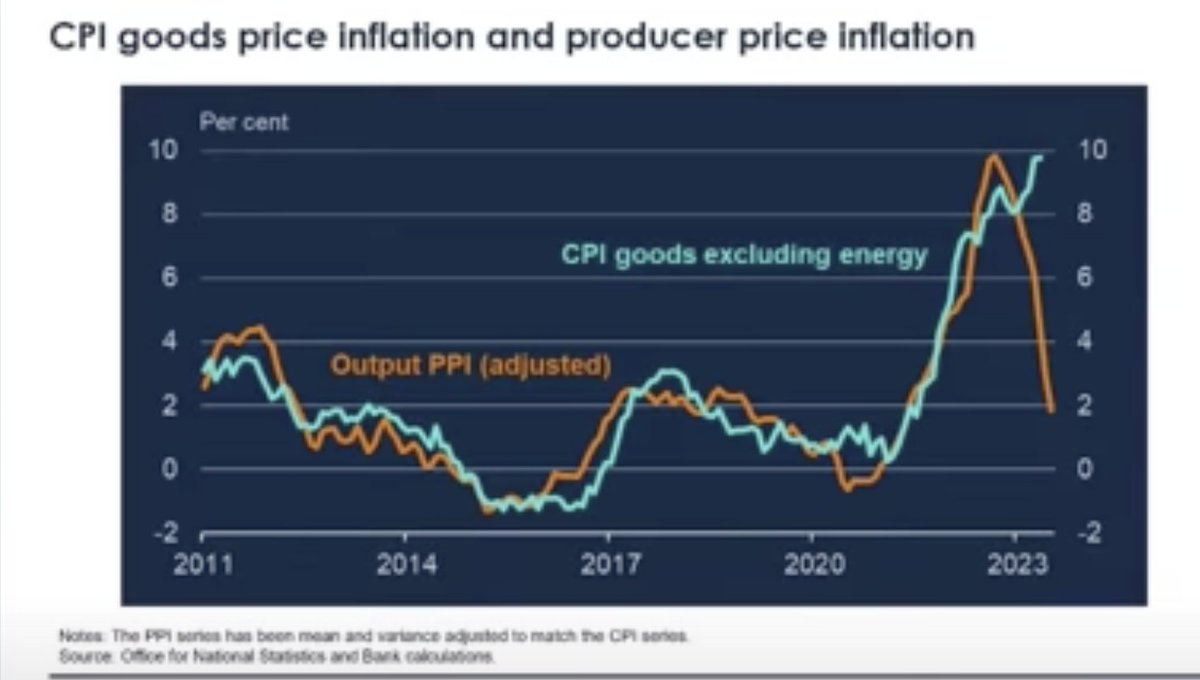
The correlation between PPI and CPI is one of the highest in the macro biz
PPI is collapsing (everywhere)
CPI is going down
Core ?
Leave sticky fingers to The Rolling Stones
The end game is hideous
We're going down hard
But macro veterans know
You only go delta one
And short that yield
On the first rate cut
Instead
Smart money loads up on convexity through 2025 calls
👁️👁️👁️
Honourable mention
Professor Silvana Tenreyro
External Member of the Bank of England’s MPC
Voted against hiking 6x❤️
❤️
❤️
Ray Dalio: In today's environment. The assumed safest assets are the riskiest. The US Government are going to repay you in confetti. Valueless currency. Inflated, watered down fiat notes with diminished purchasing power.
Existential doubt about crypto’s future in 2023 is the prerequisite for the types of multiples that people will gawk at in a few yrs — the specifics of doubt change each bear, but the doubt always emerges.
Something that’s a consensus long by society doesn’t print 10-100x’s.
So, if bank regulators knew there was a systemic problem with the banks, would they tell you ahead of time in plain language?
Probably not.
As context, that clip[1] comes from the FDIC's Systemic Resolution Advisory Committee meeting on Nov 9, 2022[2], which was just four months before banks began to die. That's the committee that deals with winding down banks — and as we know, they've been busy.
Below is the transcript of the video. Note how they justify not informing the public about how FDIC resolves banks. And how they intentionally put information out into "public view", but obfuscate it enough that teams of expensive lawyers are required to decode it.
This is why the body politic veers between passivity and panic — there's seemingly no institutional language for calm and methodical preparation, so every new disaster is denied until it's undeniable.
Here's the transcript.
SPEAKER 1
"…it should be there, it should be accessible, and people need to know, but I don't think you have much hope of reaching a public that doesn't have a professional need to know."
SPEAKER 2
"I completely agree with that. I almost think you'd scare the public. If you put this out, like why are they telling me this? Should I be concerned about my bank?
Like my insurance company doesn't tell me what they're doing with my assets, they just assume they're gonna pay my claim. Right?
It's, I think you've got to think of the unintended consequences of taking a public that has more full faith and confidence in the banking system that maybe people in this room do.
(laughter)
We want them to have full faith and confidence in the banking system, they know the FDIC insurance is there, they know it works, they put their money, and they're gonna get their money out.
So there's a select crowd of people that are on the institutional side. And if they want to understand this, they're gonna find a way to understand this, there's a bunch of law firms representing this room, there's a bunch of people that are charging by the hour, a lot of money to explain this all to them.
And it's, I don't have, I don't have a problem with that. And they all have huge staffs.
But I would be careful about the unintended consequences of starting to blast too much of this out in the general public."
[1]: https://t.co/8PKmKFDBSZ
[2]: Click this link and go to 1:25:20 to find the clip. https://t.co/HpKagrjhT0
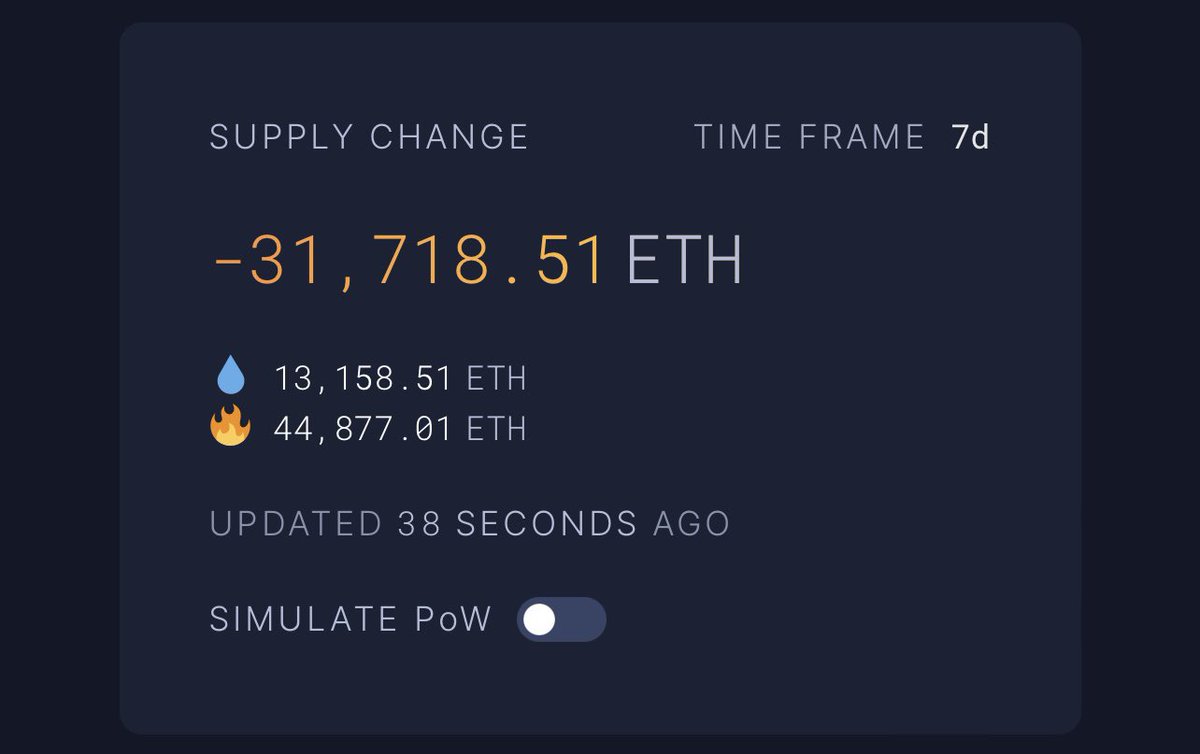
31.7K $ETH has been burned in the past seven days.
To put that in perspective, since the merge (231 days ago), 152K ETH total has been burned.
That’s ~21% of the total burn in ~3% of the total days.
This is the power of meme coins.
PRINT TRILLIONS WHILE HIKING RATES
The Fed now has “high rates” like SF has “low crime rates”. It says it does, but it doesn’t.
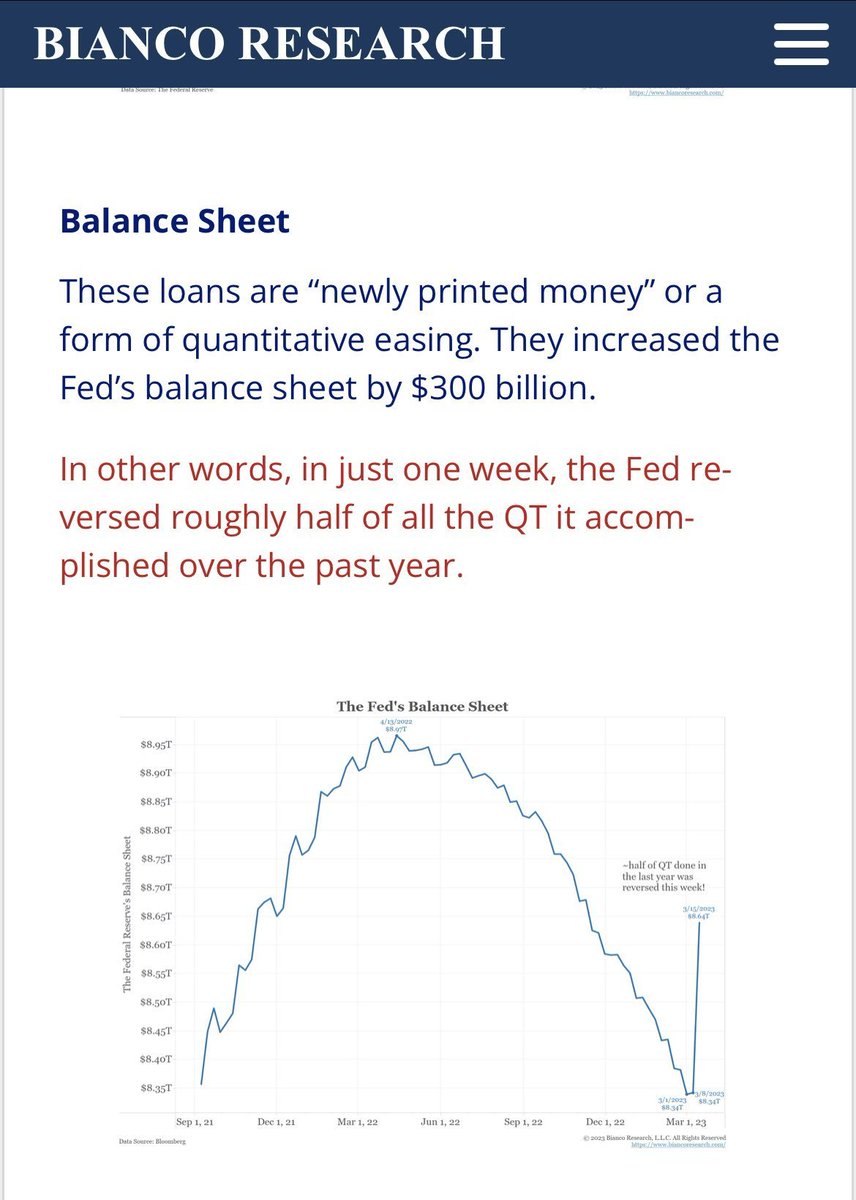
Because you have to be pretty naive to think today’s rate hike means the Fed is still “fighting inflation”. You can see it in the graphs — the printing is already vertical[1,2], and trillions in new money is available for both domestic[3,4] and foreign[5] banks. Yet the Fed continues hiking rates to fool low information voters into thinking the last two weeks were just an isolated series of multi-hundred-billion dollar bank failures, and that their policy is unchanged. Nothing to worry about, the Western banking system is resilient, and it’s normal to have banks die at the rate of five in ten days![10]
Because that’s actually all this state does: it fakes the rates.
Remember when SF claimed officially low crime rates[6] even as criminals robbed stores in broad daylight[7]? Remember when FDA prevented labs from testing so we all underestimated the COVID infection rate[8], till old people in New York started dropping dead? And remember when the Fed claimed the inflation rate wouldn't be a problem[9] before anyone buying groceries found out it was an emergency?
The American state fakes the rates.
And that’s what’s happening with today’s “hike”. After killing five of their own banks[10], catalyzing a series of bank runs[11], and realizing the public now knew they’d made hundreds more banks insolvent[12,13], the Fed rolled out programs over the last two weeks that broke the normal relationship between “hiking rates” and “tightening monetary policy”.
All the losses the Fed rate hikes cause for domestic banks?
They’re printing money to cover it.[14]
All the losses they cause for foreign banks?
Printing money to cover that too.[15]
And the losses they cause for depositors?
Naturally, more printed money![16]
So now the banks don’t publicly die from bank runs. Instead, even as this rate hike keeps pushing bank stocks further into the ground[17], and banks further into insolvency[18], the banks know they can just get more printed money (eg at the discount window[19] for BTFP) to cover their losses. That’s what BTFP, the swap lines, and the effective “FedDIC” policy mean: infinite money.
And this infinite money is no longer abstract. It’s printed dollars that individuals touch directly when they wire their money out of banks they fear may collapse, which is happening everywhere from community banks[20] to Credit Suisse[21]. The money printer is now connected directly to your checking account. And in the digital era, the bank runs are of a historical scale.[22]
Remember also: the BTFP, swap lines, and FedDIC measures are *so enormous* that the Fed is doing them over weekends[23] with all the other central banks[24], and publishing multiple joint statements[25,26] assuring people that the “system is resilient”, even as Moody’s has downgraded the US banking system as a whole[27].
One of the things I hate about this system is that it’s evolved to be opaque, like a snake that’s evolved camouflage. If the Fed came outright and *said* they were digitally devaluing the dollar by printing trillions, that they were monetizing the debt as Dalio predicted[31] and even getting bondholders to abet the devaluation, everyone would flee for the Bitcoin exit. So instead they lie, to themselves and to others, just as Jean-Claude Juncker recommended[32]. As with CDOs[33] in 2008, the point is to fool themselves and to fool you.
But you have to see through the camouflage. They’re printing trillions[34,35] even as they’re hiking rates. Indeed, they’re printing trillions to compensate for the *consequences* of hiking rates. There will of course be other consequences to printing trillions. You can wait to find out, or you can get into Bitcoin now.
5 figures and 35 citations follow. 👇
Ben Bernanke as Fed chairman:
“The impact on the broader economy and financial markets of the problems in the subprime markets seems likely to be contained.” (March 2007)
"We do not expect significant spillovers from the subprime market to the rest of the economy or to the...
And we finalized!
Happy merge all. This is a big moment for the Ethereum ecosystem. Everyone who helped make the merge happen should feel very proud today.