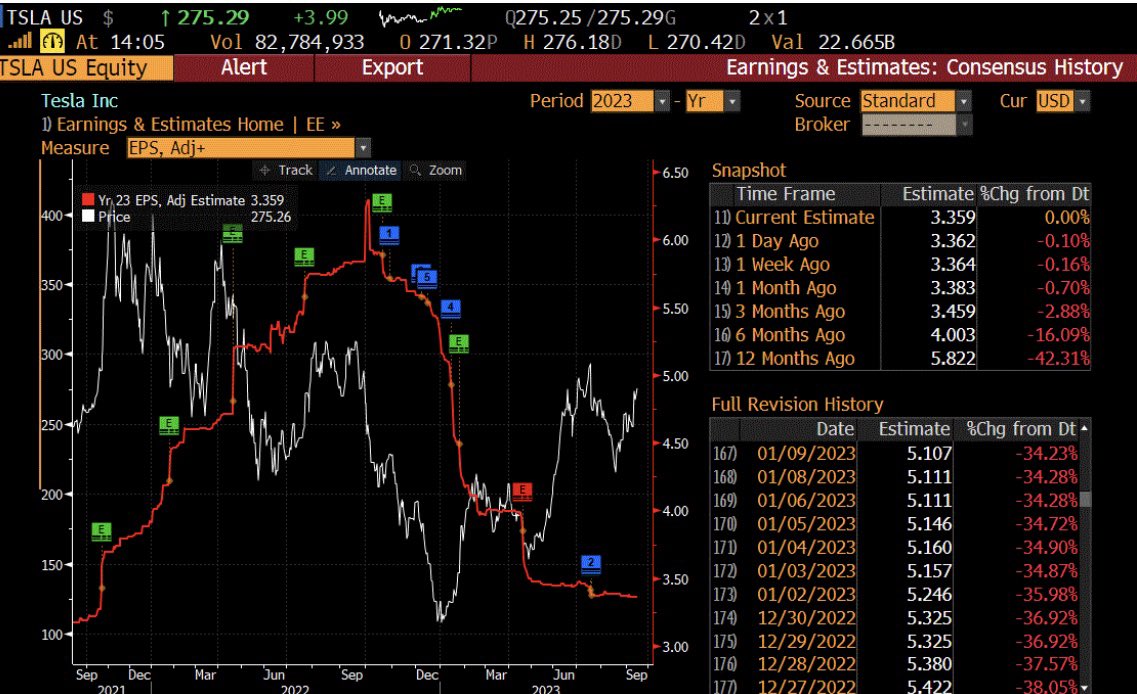
I’ve rarely seen such a disconnect between $TSLA EPS estimates which continue to fall (FY’23 $3.36, -37% YTD; FY’24 $4.79, -27% YTD) vs overwhelming bullishness about FSD/mnfg advantages among the Tesla faithful. How does one reconcile?
The former issue is short term, with traders seeing 3Q volume ests dropping and worries that auto gross margins (ex-RC) still have not bottomed. My 3Q delivs est is 445K vs 462K Street, with the difference largely due to China not having M-3s to deliver or export to Europe over the last few weeks of the qtr. This will reverse in 4Q once M-3 refresh delivs start.