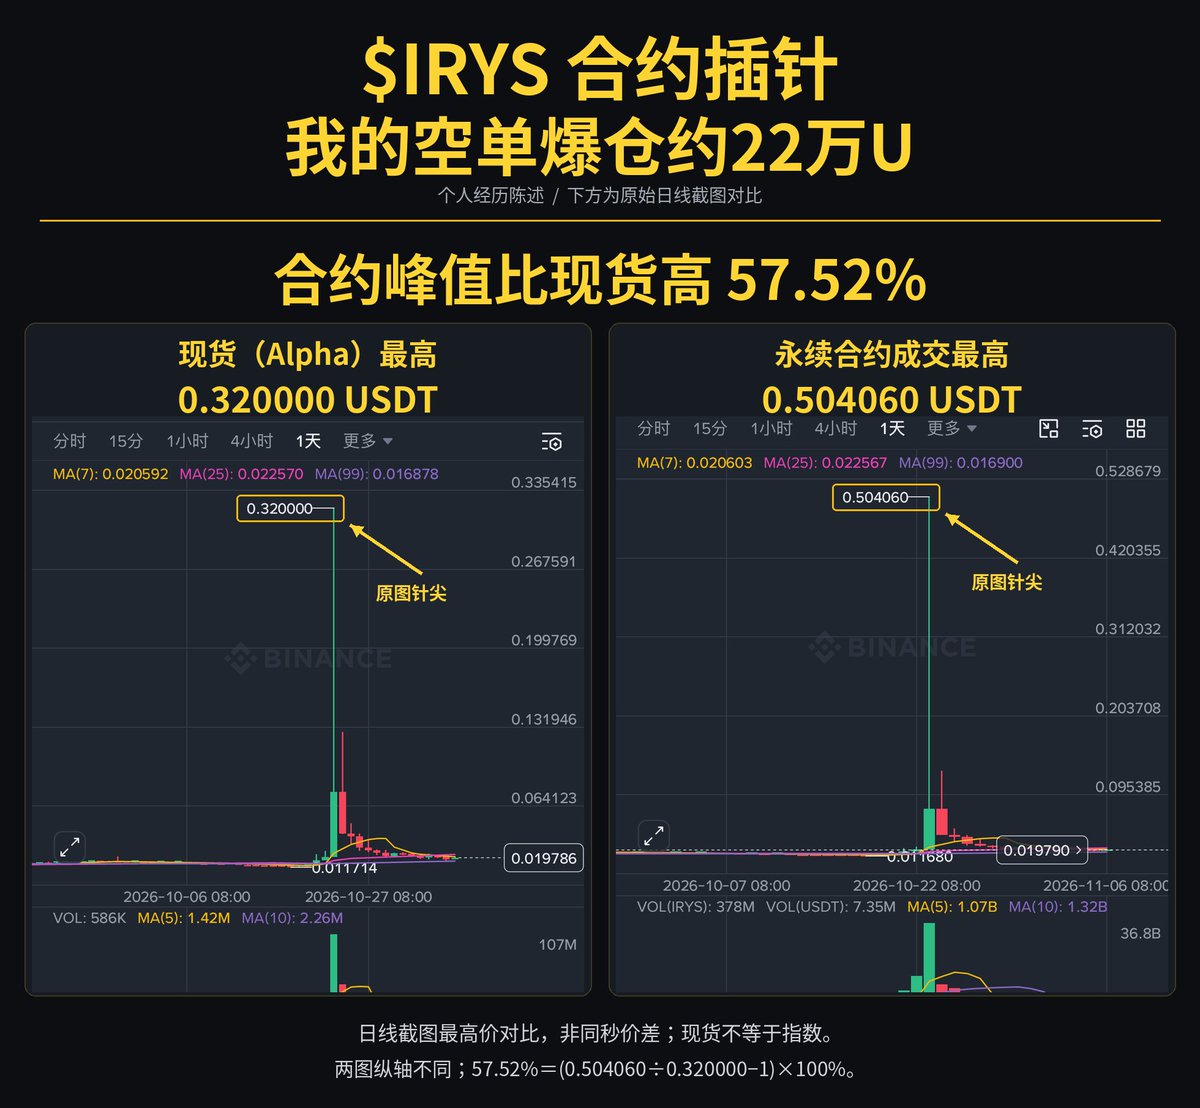
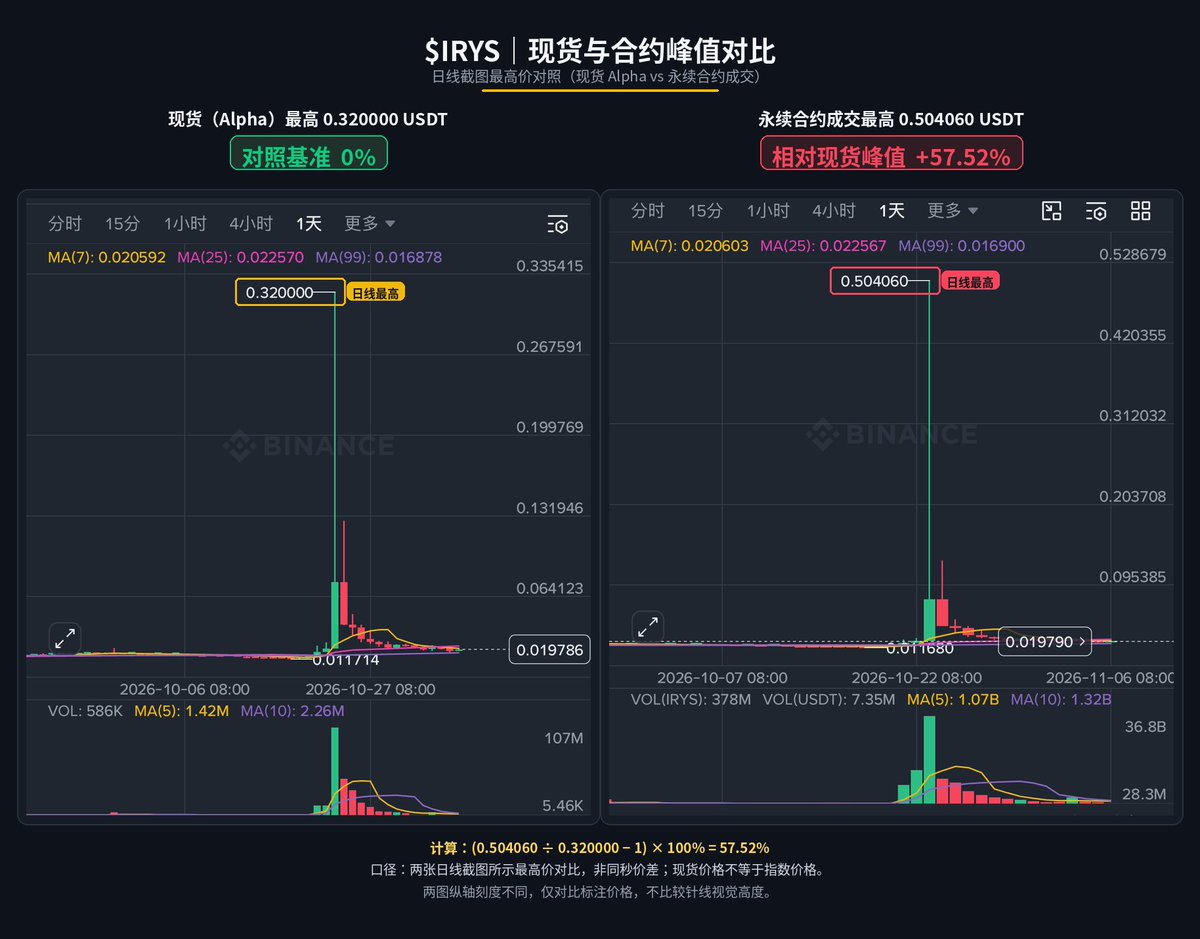
我在币安正常做空 irys:native ,并非套利交易。北京时间2026年10月24日03:23,我的空单被强平。对此,我要求币安正面回应三个问题:
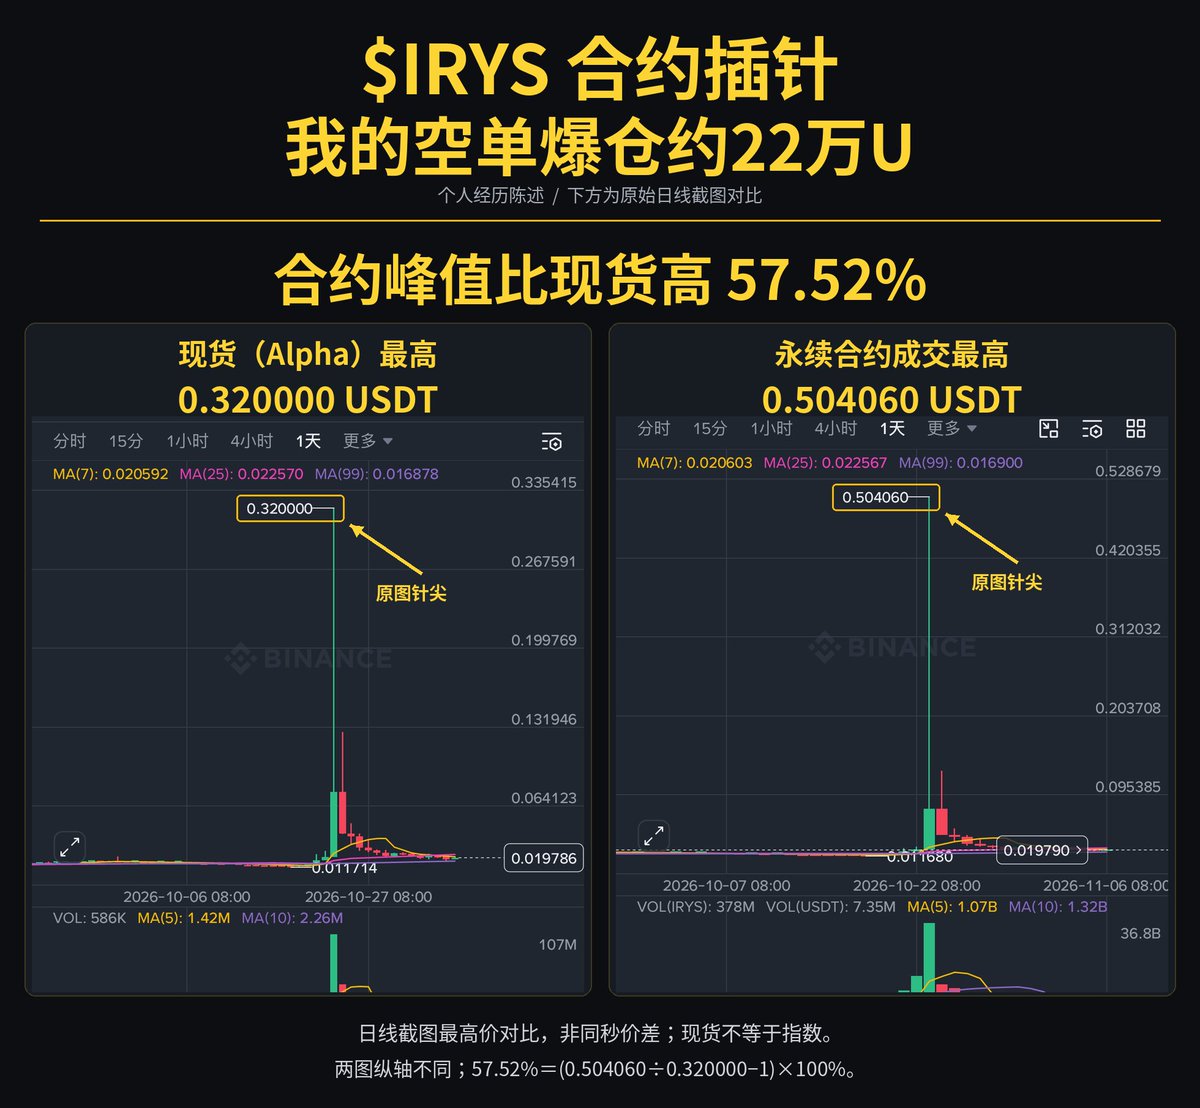
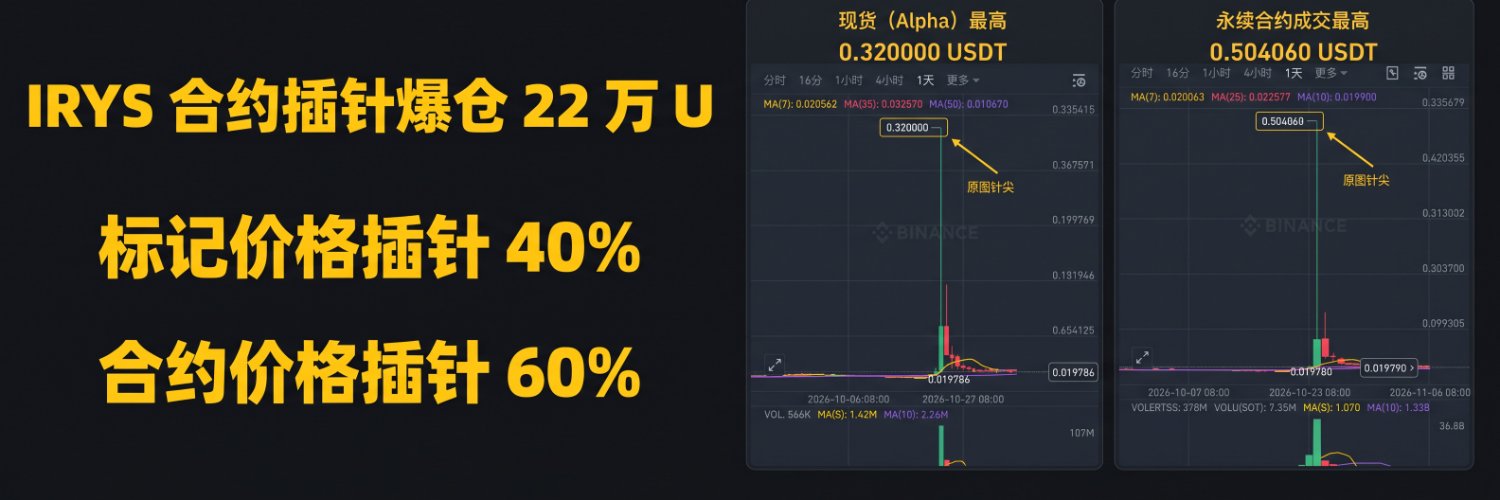
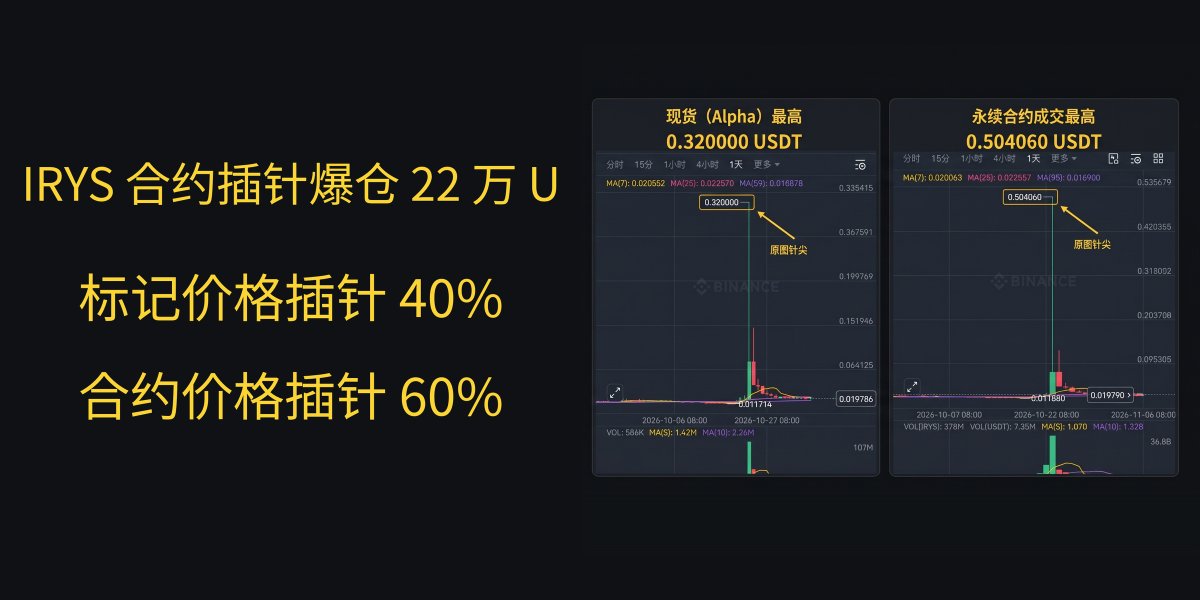
第一,标记价为何严重偏离指数?强平所在分钟,标记价最高值较指数价最高值高约39.38%。这一偏离是否符合规则?当时有哪些限制和保护措施,是否有效执行?
第二,是否存在通过操纵永���合约价格影响标记价的风险?简单说,标记价公式会参考最近30秒永续合约买卖报价与指数价之间的平均价差。如果有人持续推高永续合约的报价,就可能把用于判断爆仓的标记价一起抬高,进而触发更多空头强平;强平买单又可能继续推高合约价格。30秒窗口和现有保护措施,能否阻断这种相互放大的循环?
第三,指数成分与权重是否合理?我们事后核查的行情数据显示,Upbit的IRYS/KRW现货市场24小时成交量最大,却未出现在查询到的指数成分中;Binance Alpha与OKX则各占约28.6%。请说明事发时实际采用的成分和权重,以及如何评估各市场的成交深度、报价稳定性和数据质量。
请币安公开计算记录与保护参数,正式复核此次强平,并给出明确的处理及赔偿方案。对本次 irys:native 亏损或强平有疑问的交易者,欢迎补充脱敏证据,共同要求公开、可核查的答复。
@BinanceHelpDesk @binance @binancezh @heyibinance @_RichardTeng @cz_binance
@colinwu @wublockchain12 @WuBlockchain @DefiSquared @EmberCN @ai_9684xtpa @zachxbt
转发本帖,发布48小时后随机抽8位,每人8.88U红包。每人一次机会,多号参与无效,中奖与观点立场无关。公开开奖,奖金由我个人承担,与申诉结果无关。
I held a directional short position in irys:native on Binance. This was not an arbitrage trade. My position was liquidated at 03:23 on October 24, 2026 (UTC+8). I am asking Binance to address three specific concerns:
First, why did the mark price diverge so substantially from the index price? During the minute of my liquidation, the mark-price high was approximately 39.38% above the index-price high. Was this divergence consistent with the applicable rules? What limits and safeguards were in place, and were they properly enforced?
Second, could manipulation of perpetual-contract prices influence the mark price? In simple terms, one component of the mark-price formula uses the average difference between the perpetual contract’s bid/ask midpoint and the index price over the preceding 30 seconds. If someone persistently pushes perpetual quotes higher, this could also raise the mark price used for liquidation, potentially triggering more short liquidations. The resulting buy orders could then push perpetual prices higher still. Are the 30-second window and existing safeguards sufficient to interrupt this feedback loop?
Third, are the index constituents and weights appropriate? The post-event market data we checked showed that Upbit’s IRYS/KRW spot market had the highest 24-hour trading volume, yet Upbit was absent from the index-constituent list we retrieved. Binance Alpha and OKX each carried approximately 28.6% weight. Please disclose the constituents and weights actually used at the time, and explain how market depth, price-feed stability and data quality were assessed.
I demand that Binance disclose the calculation records and protection parameters, formally review this liquidation, and provide a clear resolution and compensation plan. Traders with questions about their irys:native losses or liquidations are welcome to contribute evidence with personal information redacted. We deserve a transparent, verifiable response.
@BinanceHelpDesk @binance @binancezh @heyibinance @_RichardTeng @cz_binance
@colinwu @wublockchain12 @WuBlockchain @DefiSquared @EmberCN @ai_9684xtpa @zachxbt
Repost this post to enter the giveaway. At 48 hours after publication, 8 winners will be randomly selected to receive 8.88 USDT each. One entry per person; multiple-account entries are ineligible. Your viewpoint does not affect your chances of winning. The draw and results will be made public. I personally fund the prizes, regardless of the outcome of my complaint.
Same here. I was just shorting $IRYS on Binance futures, normal trade. The mark price spiked 40% above index, the trade price wicked 60%, and I got liquidated for $220K. Support called it "normal volatility" and refused any compensation. This isn't one person's problem. Binance needs to explain and review it. https://t.co/zfLF9s7NTJ
我在币安正常做空 irys:native ,并非套利交易。北京时间2026年10月24日03:23,我的空单被强平。对此,我要求币安正面回应三个问题:
第一,标记价为何严重偏离指数?强平所在分钟,标记价最高值较指数价最高值高约39.38%。这一偏离是否符合规则?���时有哪些限制和保护措施,是否有效执行?
第二,是否存在通过操纵永续合约价格影响标记价的风险?简单说,标记价公式会参考最近30秒永续合约买卖报价与指数价之间的平均价差。如果有人持续推高永续合约的报价,就可能把用于判断爆仓的标记价一起抬高,进而触发更多空头强平;强平买单又可能继续推高合约价格。30秒窗口和现有保护措施,能否阻断这种相互放大的循环?
第三,指数成分与权重是否合理?我们事后核查的行情数据显示,Upbit的IRYS/KRW现货市场24小时成交量最大,却未出现在查询到的指数成分中;Binance Alpha与OKX则各占约28.6%。请说明事发时实际采用的成分和权重,以及如何评估各市场的成交深度、报价稳定性和数据质量。
请币安公开计算记录与保护参数,正式复核此次强平,并给出明确的处理及赔偿方案。对本次 irys:native 亏损或强平有疑问的交易者,欢迎补充脱敏证据,共同要求公开、可核查的答复。
@BinanceHelpDesk @binance @binancezh @heyibinance @_RichardTeng @cz_binance
@colinwu @wublockchain12 @WuBlockchain @DefiSquared @EmberCN @ai_9684xtpa @zachxbt
转发本帖,发布48小时后随机抽8位,每人8.88U红包。每人一次机会,多号参与无效,中奖与观点立场无关。公开开奖,奖金由我个人承担,与申诉结果无关。
I held a directional short position in irys:native on Binance. This was not an arbitrage trade. My position was liquidated at 03:23 on October 24, 2026 (UTC+8). I am asking Binance to address three specific concerns:
First, why did the mark price diverge so substantially from the index price? During the minute of my liquidation, the mark-price high was approximately 39.38% above the index-price high. Was this divergence consistent with the applicable rules? What limits and safeguards were in place, and were they properly enforced?
Second, could manipulation of perpetual-contract prices influence the mark price? In simple terms, one component of the mark-price formula uses the average difference between the perpetual contract’s bid/ask midpoint and the index price over the preceding 30 seconds. If someone persistently pushes perpetual quotes higher, this could also raise the mark price used for liquidation, potentially triggering more short liquidations. The resulting buy orders could then push perpetual prices higher still. Are the 30-second window and existing safeguards sufficient to interrupt this feedback loop?
Third, are the index constituents and weights appropriate? The post-event market data we checked showed that Upbit’s IRYS/KRW spot market had the highest 24-hour trading volume, yet Upbit was absent from the index-constituent list we retrieved. Binance Alpha and OKX each carried approximately 28.6% weight. Please disclose the constituents and weights actually used at the time, and explain how market depth, price-feed stability and data quality were assessed.
I demand that Binance disclose the calculation records and protection parameters, formally review this liquidation, and provide a clear resolution and compensation plan. Traders with questions about their irys:native losses or liquidations are welcome to contribute evidence with personal information redacted. We deserve a transparent, verifiable response.
@BinanceHelpDesk @binance @binancezh @heyibinance @_RichardTeng @cz_binance
@colinwu @wublockchain12 @WuBlockchain @DefiSquared @EmberCN @ai_9684xtpa @zachxbt
Repost this post to enter the giveaway. At 48 hours after publication, 8 winners will be randomly selected to receive 8.88 USDT each. One entry per person; multiple-account entries are ineligible. Your viewpoint does not affect your chances of winning. The draw and results will be made public. I personally fund the prizes, regardless of the outcome of my complaint.
我在币安正常做空 irys:native ,并非套利交易。北京时间2026年10月24日03:23,我的空单被强平。对此,我要求币安正面回应三个问题:
第一,标记价为何严重偏离指数?强平所在分钟,标记价最高值较指数价最高值高约39.38%。这一偏离是否符合规则?���时有哪些限制和保护措施,是否有效执行?
第二,是否存在通过操纵永续合约价格影响标记价的风险?简单说,标记价公式会参考最近30秒永续合约买卖报价与指数价之间的平均价差。如果有人持续推高永续合约的报价,就可能把用于判断爆仓的标记价一起抬高,进而触发更多空头强平;强平买单又可能继续推高合约价格。30秒窗口和现有保护措施,能否阻断这种相互放大的循环?
第三,指数成分与权重是否合理?我们事后核查的行情数据显示,Upbit的IRYS/KRW现货市场24小时成交量最大,却未出现在查询到的指数成分中;Binance Alpha与OKX则各占约28.6%。请说明事发时实际采用的成分和权重,以及如何评估各市场的成交深度、报价稳定性和数据质量。
请币安公开计算记录与保护参数,正式复核此次强平,并给出明确的处理及赔偿方案。对本次 irys:native 亏损或强平有疑问的交易者,欢迎补充脱敏证据,共同要求公开、可核查的答复。
@BinanceHelpDesk @binance @binancezh @heyibinance @_RichardTeng @cz_binance
@colinwu @wublockchain12 @WuBlockchain @DefiSquared @EmberCN @ai_9684xtpa @zachxbt
转发本帖,发布48小时后随机抽8位,每人8.88U红包。每人一次机会,多号参与无效,中奖与观点立场无关。公开开奖,奖金由我个人承担,与申诉结果无关。
I held a directional short position in irys:native on Binance. This was not an arbitrage trade. My position was liquidated at 03:23 on October 24, 2026 (UTC+8). I am asking Binance to address three specific concerns:
First, why did the mark price diverge so substantially from the index price? During the minute of my liquidation, the mark-price high was approximately 39.38% above the index-price high. Was this divergence consistent with the applicable rules? What limits and safeguards were in place, and were they properly enforced?
Second, could manipulation of perpetual-contract prices influence the mark price? In simple terms, one component of the mark-price formula uses the average difference between the perpetual contract’s bid/ask midpoint and the index price over the preceding 30 seconds. If someone persistently pushes perpetual quotes higher, this could also raise the mark price used for liquidation, potentially triggering more short liquidations. The resulting buy orders could then push perpetual prices higher still. Are the 30-second window and existing safeguards sufficient to interrupt this feedback loop?
Third, are the index constituents and weights appropriate? The post-event market data we checked showed that Upbit’s IRYS/KRW spot market had the highest 24-hour trading volume, yet Upbit was absent from the index-constituent list we retrieved. Binance Alpha and OKX each carried approximately 28.6% weight. Please disclose the constituents and weights actually used at the time, and explain how market depth, price-feed stability and data quality were assessed.
I demand that Binance disclose the calculation records and protection parameters, formally review this liquidation, and provide a clear resolution and compensation plan. Traders with questions about their irys:native losses or liquidations are welcome to contribute evidence with personal information redacted. We deserve a transparent, verifiable response.
@BinanceHelpDesk @binance @binancezh @heyibinance @_RichardTeng @cz_binance
@colinwu @wublockchain12 @WuBlockchain @DefiSquared @EmberCN @ai_9684xtpa @zachxbt
Repost this post to enter the giveaway. At 48 hours after publication, 8 winners will be randomly selected to receive 8.88 USDT each. One entry per person; multiple-account entries are ineligible. Your viewpoint does not affect your chances of winning. The draw and results will be made public. I personally fund the prizes, regardless of the outcome of my complaint.
我在币安正常做空 irys:native ,并非套利交易。北京时间2026年10月24日03:23,我的空单被强平。对此,我要求币安正面回应三个问题:
第一,标记价为何严重偏离指数?强平所在分钟,标记价最高值较指数价最高值高约39.38%。这一偏离是否符合规则?���时有哪些限制和保护措施,是否有效执行?
第二,是否存在通过操纵永续合约价格影响标记价的风险?简单说,标记价公式会参考最近30秒永续合约买卖报价与指数价之间的平均价差。如果有人持续推高永续合约的报价,就可能把用于判断爆仓的标记价一起抬高,进而触发更多空头强平;强平买单又可能继续推高合约价格。30秒窗口和现有保护措施,能否阻断这种相互放大的循环?
第三,指数成分与权重是否合理?我们事后核查的行情数据显示,Upbit的IRYS/KRW现货市场24小时成交量最大,却未出现在查询到的指数成分中;Binance Alpha与OKX则各占约28.6%。请说明事发时实际采用的成分和权重,以及如何评估各市场的成交深度、报价稳定性和数据质量。
请币安公开计算记录与保护参数,正式复核此次强平,并给出明确的处理及赔偿方案。对本次 irys:native 亏损或强平有疑问的交易者,欢迎补充脱敏证据,共同要求公开、可核查的答复。
@BinanceHelpDesk @binance @binancezh @heyibinance @_RichardTeng @cz_binance
@colinwu @wublockchain12 @WuBlockchain @DefiSquared @EmberCN @ai_9684xtpa @zachxbt
转发本帖,发布48小时后随机抽8位,每人8.88U红包。每人一次机会,多号参与无效,中奖与观点立场无关。公开开奖,奖金由我个人承担,与申诉结果无关。
I held a directional short position in irys:native on Binance. This was not an arbitrage trade. My position was liquidated at 03:23 on October 24, 2026 (UTC+8). I am asking Binance to address three specific concerns:
First, why did the mark price diverge so substantially from the index price? During the minute of my liquidation, the mark-price high was approximately 39.38% above the index-price high. Was this divergence consistent with the applicable rules? What limits and safeguards were in place, and were they properly enforced?
Second, could manipulation of perpetual-contract prices influence the mark price? In simple terms, one component of the mark-price formula uses the average difference between the perpetual contract’s bid/ask midpoint and the index price over the preceding 30 seconds. If someone persistently pushes perpetual quotes higher, this could also raise the mark price used for liquidation, potentially triggering more short liquidations. The resulting buy orders could then push perpetual prices higher still. Are the 30-second window and existing safeguards sufficient to interrupt this feedback loop?
Third, are the index constituents and weights appropriate? The post-event market data we checked showed that Upbit’s IRYS/KRW spot market had the highest 24-hour trading volume, yet Upbit was absent from the index-constituent list we retrieved. Binance Alpha and OKX each carried approximately 28.6% weight. Please disclose the constituents and weights actually used at the time, and explain how market depth, price-feed stability and data quality were assessed.
I demand that Binance disclose the calculation records and protection parameters, formally review this liquidation, and provide a clear resolution and compensation plan. Traders with questions about their irys:native losses or liquidations are welcome to contribute evidence with personal information redacted. We deserve a transparent, verifiable response.
@BinanceHelpDesk @binance @binancezh @heyibinance @_RichardTeng @cz_binance
@colinwu @wublockchain12 @WuBlockchain @DefiSquared @EmberCN @ai_9684xtpa @zachxbt
Repost this post to enter the giveaway. At 48 hours after publication, 8 winners will be randomly selected to receive 8.88 USDT each. One entry per person; multiple-account entries are ineligible. Your viewpoint does not affect your chances of winning. The draw and results will be made public. I personally fund the prizes, regardless of the outcome of my complaint.