Compare the businesses that succeeded alongside $RKLB, and now tell me something similar.
Exactly! Vertical integration.
In an industry where suppliers are almost nonexistent and demand is growing rapidly, $RKLB’s ability to manufacture components in-house allows the company to improve margins and ultimately grow faster.
Every stock has a story. For $HROW, it's "too high expectations for too short a time frame."
Roy Amara once said: "We tend to overestimate the effect of a technology in the short run and underestimate the effect in the long run." He meant computers and the internet. But it fits hardly any stock as well as Harrow. Harrow is a US eye care company that mostly buys or licenses drugs that are already largely developed and sells them through its own US platform. Unlike typical pharma companies, the risk lies in execution, not in development.
Recently, some investors have capitulated. I've been invested for about a year and a half. In my view, the problem isn't the company, the management, the business model or the operations. It's the expectations. Harrow is in a classic build-out phase. invest now, harvest later. Which other pharma company in that phase do investors try to forecast this precisely, quarter by quarter?
I don't know one, though I don't know them all. Zoom out, extend your time horizon, and life gets a lot easier.
So I asked myself today, what has to happen for today's price of around $28 to be fair? Short answer: Harrow misses its own guidance by a wide margin and hits its targets years late. I think that's unlikely. But it fits the drama queen this stock has always been. Forget the official guidance for 2026 and 2027. If it happens, jackpot. If not, there are plenty of other scenarios that still offer upside from here. Please take a critical look at my scenario below.
At $28, the market values Harrow at around $1.1 billion, plus about $250 million in net debt. Three things have to happen to justify that price.
1. Revenue reaches around $500 million by 2029. That's about 17% growth per year from my estimate of $316 million for 2026, which is already below management's guidance of $350 to 365 million. Without the TYRVAYA acquisition, it's about 14% per year, slightly below the pace of 2026, a disappointing year.
2. Harrow becomes clearly profitable. By 2029, 30% adjusted EBITDA margin, around $150 million. Today it's close to zero. Management aims higher: $80 to 100 million this year and around 35% margin in the long run. I expect about $20 million in 2026.
3. Growth slows to about 3% per year after 2029. No second growth phase, no G-MELT, no further acquisitions.
For comparison: management's target of $250 million in revenue in Q4 2027 means about $720 to 830 million for the full year, because Q4 is always Harrow's strongest quarter and brings in about a third of annual revenue. The share price assumes only about two thirds of that, and two years later.
So this isn't a pessimistic scenario.But it still has to be delivered. Harrow must keep growing at about 16% a year, the pace of my reduced 2026 estimate, not the official guidance, and lift its margin from almost nothing to around 30%. Those margins will be hard to achieve with such slow revenue growth.
The key question isn't whether Harrow hits its targets. It's whether they can turn growth into cash and keep costs under control. That's what I'll be watching in November.
Even though it’s not biotech, the market may have sold it off alongside the sector.
This is my conservative estimate for 2026, compared with the estimates circulating on X, which are based on official guidance. I still see over 50% upside to fair value.
Not financial advice. I own shares in $HROW
@wealthmatica It’s definitely impressive, but let’s not forget the contribution of acquisitions to this year’s revenue growth.
In Q2, $ZETA grew revenue by 44% YoY, but 28% excluding M&A. Organic growth is the key metric to watch.
That said, I agree with you — $ZETA is a top-class company.
$RXRX
Why do Roche, Sanofi and other pharma companies partner with Recursion instead of simply building this themselves?
They have more capital, more clinical experience and decades of pharmaceutical knowledge.
So why pay Recursion?
It's the data, infrastructure and years of iteration behind it.
Big Pharma has enormous amounts of data, but much of it wasn't generated specifically for AI. It's fragmented across different protocols, teams and silos.
Recursion built a data factory designed from the ground up to generate standardized, machine-readable biological data.
And you can't simply buy years of experiment → data → model → experiment cycles
You also can't easily recreate the culture of a startup inside a huge pharmaceutical organization. That's why big companies that fail to adapt and innovate eventually get disrupted by the companies that do.
Building something this different requires speed, experimentation, risk-taking and the willingness to completely rethink how drug discovery is done.
That culture compounds alongside the technology and data.
The AI is only as good as the system feeding it.
I went down the $NAUT rabbit hole and found something I think deserves much more attention.
The Dario Amodei / Parag Mallick connection goes much deeper than I realized.
Parag Mallick is the co-founder and Chief Scientist of Nautilus Biotechnology.
Dario Amodei is the co-founder and CEO of Anthropic.
But before Anthropic, before Claude, before the AI boom… Amodei was working on proteins.
And he worked under Mallick.
Amodei is listed as a Mallick Lab alumnus, and the two actually co-authored scientific research in proteomics.
They worked on methods involving mass spectrometry and protein analysis — exactly the world Nautilus is now trying to reinvent.
And the relationship didn't simply disappear years ago.
In his 2024 essay “Machines of Loving Grace,” Amodei thanked Mallick for reviewing drafts and specifically credited him for contributing an idea around the immune system and cancer.
Why does this matter?
Because one of Amodei's fundamental observations from biology was that the complexity is almost beyond human scale.
That helped push him toward AI.
Now look at what Nautilus is trying to build.
Voyager isn't simply another laboratory instrument.
The ambition is to generate incredibly deep information about proteins and proteoforms at massive scale.
And AI needs exactly this kind of thing:
DATA.
Not more internet text.
High-quality biological data describing what is actually happening inside cells.
Think about the potential loop:
Nautilus → generates massive proteomic datasets
AI → interprets biological complexity
Pharma → identifies biomarkers, disease mechanisms and potentially new drug targets
This does NOT mean Anthropic is buying Nautilus.
There is no announced Anthropic/Nautilus partnership.
There is no evidence I have seen that Amodei is investing in $NAUT.
And the “$10B+” claims circulating on X are speculation, not valuation analysis.
But the connection itself is real.
And I find it fascinating that one of the people at the center of today's AI revolution came from the exact scientific world Nautilus is trying to transform — and worked directly with Nautilus' Chief Scientist.
Maybe nothing ever comes from that relationship.
But it reinforces something I've been thinking about $NAUT:
The real opportunity may not simply be selling proteomics instruments.
It could be owning a platform capable of generating extremely valuable biological data in an era where AI is becoming increasingly capable of understanding it.
If Voyager works at scale, that could become very interesting.
I'm not buying the $10B story today.
But I'm definitely paying attention.
$NAUT $ABCL $RXRX $IVVD $TENX $PLTR
#Proteomics #AI #Biotech #SmallCaps #Investing
$RXRX
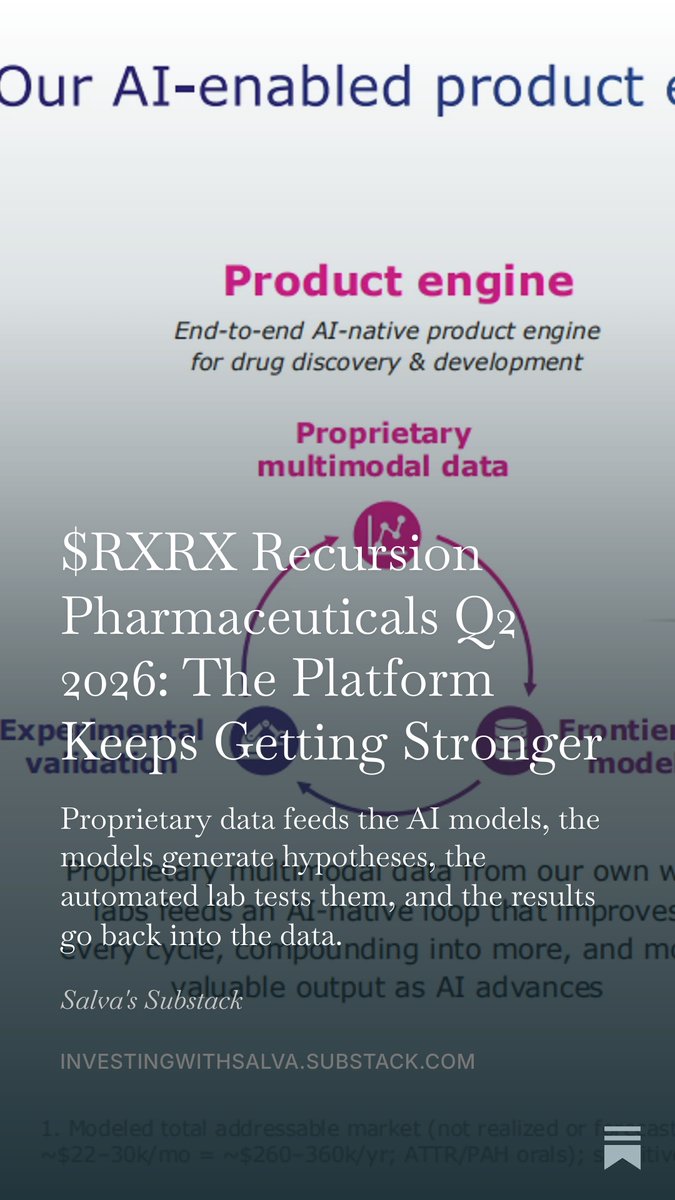
One of the most interesting parts of the Q2 2026 call was the progress on AI agents.
The Biology Agent can answer questions across Recursion’s proprietary maps in hours instead of weeks.
The Chemistry Design Agent reduced structural analysis from 4 hours to 30 minutes.
And orchestration agents are contributing to 1.3–1.6x higher enrollment rates vs. historical benchmarks.
This is where the AI thesis becomes tangible.
If you can run more iterations, faster and at lower cost, the same dollar can fund more, which is ultimately increasing shareholder value over time.
And in drug discovery, where probability is everything, increasing the number of iterations increases the outcomes and the improvement of the propietary data.
It's to make the entire drug development engine more efficient. This is the MOAT.
$HIMS
Healthcare today is fundamentally reactive.
We wait until something goes wrong before engaging with the system.
Yet preventive maintenance is the norm everywhere else.
Healthcare is becoming more expensive, fragmented, and difficult to access.
The system was built around the provider.
$HIMS is trying to rebuild it around the consumer.
I have no doubt the TAM is massive, and I believe $HIMS can capture a significant share of it.
Patience will pay.
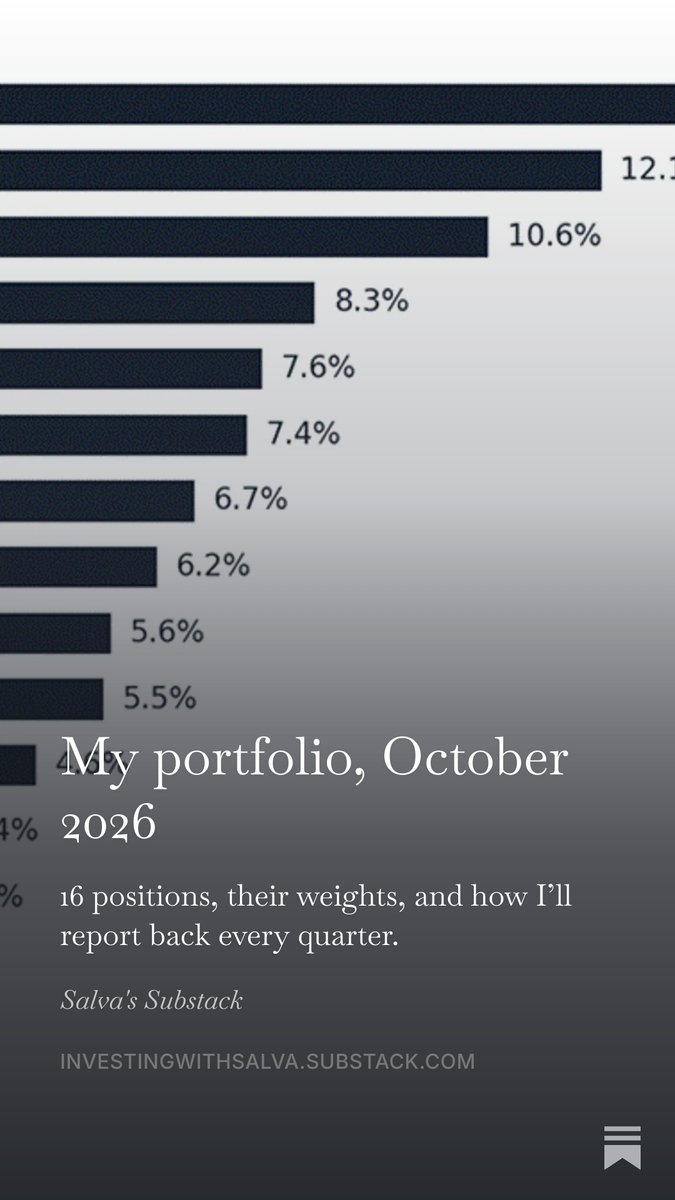
If anyone is interested in my portfolio weights, you can find my current portfolio here.
Of course, this is not financial advice.
And if you’re not following me on Substack yet, this is a good chance to subscribe!
I will keep sharing the portfolio updates every quarter.
https://t.co/GAF77jme6b
$HIMS, $DUOL, $AMD, $DLO, $ZETA, $RKLB, $PATH,
$PGY, $NIO, $CLPT, $IBRX, $NAUT, $RXRX
$NIO
What makes the Shenji story particularly interesting to me is the structure.
In February, external investors put RMB2.257B into Shenji, valuing the business at roughly RMB8.27B, while NIO retained 62.7%.
Then in June/August, Shenji raised another RMB493M at a RMB12.25B post-money valuation, with NIO still holding 59.95%.
This isn't just an internal R&D department anymore.
NIO is building a separately funded semiconductor business.
That's a very different economic model from simply saving NIO money on Nvidia chips.
And I think the market is still mostly valuing Shenji as an R&D expense rather than as an asset with external optionality.
This man is doing something big.
$IBRX is not just fighting cancer but soon preventing it.
Who wouldn’t want a strong, active immune system?
Thank you, @DrPatrick!
Best of wishes Michael and Congratulations .
There are millions of patients with cancer worldwide who are in complete remission. The next frontier is to develop therapies strengthening the immune system to prevent recurrence in these over 15 million patients in the USA alone, and drive long term durable freedom from cancer to win the war. Incremental short term duration of response should no longer be an acceptable outcome.
The therapies to address and maintain cancer free status are now here……..the orchestration of the immune system, the identification of tumor DNA in the peripheral blood, the easy measurement of the NK and T cell levels in the peripheral blood count, the sophistication of next gen PET/ MRI/ CT scans, the ability to grow and store activated NK cells, the ability to identify tumor educated T cells, the new knowledge of camelid derived heavy chain single domain antibodies and the ability to precisely target radioactive ligands, to precisely target CART and CarNK and CAR-iNKT cells. These immunotherapy advances are all here today and in various stages of clinical trials. The oncology community will enter this next generation of paradigm change. The need to establish these diagnostic and therapeutic combinations as IMMUNOTHERAPY 2.0 is both urgent and exhilarating.
This was the subject of my one hour talk with NIH and NCI and the decade of collaboration with Jeffrey Schlom and James Gulley to develop a cancer vaccine. Hope to release the talk once I receive the video recording and obtain clearance to make it public. We are closer than ever.
Small efficiencies compound, and businesses work the same way: a slight edge, repeated every day for years, is often what separates a good company from a great one.
Today with network effects, that effect is even stronger, because a small early lead can snowball into a dominant position.
$HIMS, $DUOL, $AMD, $DLO, $ZETA, $RKLB, $PATH, $PGY, $NIO, $CLPT, $IBRX, $NAUT, $RXRX
$NAUT
First large-scale, single-molecule analysis of the tau proteoform landscape reveals unique disease-associated modifications, a new source of potential biomarkers and drug targets, and a method Nautilus is now extending across disease areas.
When I first saw this news a month ago, I really didn’t understand how the stock was trading so low.
But this is what happens with micro caps like this one.
The rerating has started, with huge volume coming in over the past few days.
And these are simply such good results and a strong confirmation that the platform works:
Going beyond measuring bulk tau and being able to quantify individual tau proteoforms could be key for developing novel diagnostics and precision medicine in Alzheimer’s and other tauopathies.
Nautilus identified 130 tau proteoform groups at scale, with high precision, sensitivity and reproducibility, quantifying proteoforms present at just 0.1% of a sample and achieving a median CV below 5.5%.
Even more interesting: the same validated approach is now being applied to α-synuclein in Parkinson’s and AKT1 in oncology.
The roadmap is ~20 proteoform assays by mid-2028.
This is exactly what I want to see from the Voyager platform: prove it works, then expand it across diseases.
I published this deep dive on $NAUT when it was trading around $0.90, about one month ago.
You should have read it by now, but it is still early, so don’t miss it! I am quite sure Nautilus will be on the headlines several more times from here.
https://t.co/NVENSqODZ0
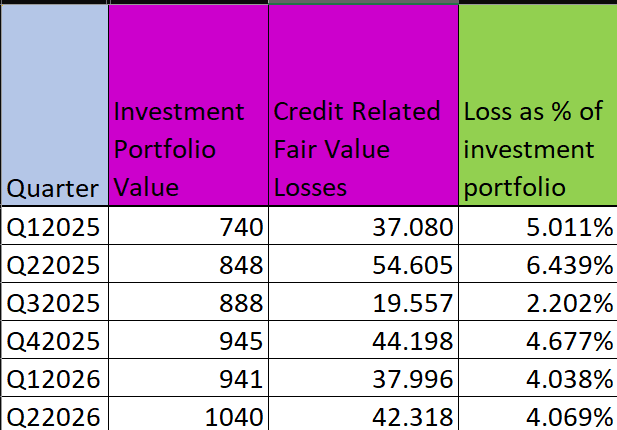
The important part of $PGY’s growth story:
They’re not growing by taking more credit risk.
Actually, they got more conservative earlier this year, pulling back from the riskiest tiers and haven’t reversed that since.
Growth has come from:
→ New products
→ New partners
→ Moving upstream
→ Deeper penetration with existing partners
Still, we need to keep an eye on these KPIs throughout different phases of the economic cycle:
$NIO's brand and reputation keep growing.
Among existing NIO customers, brand reputation & awareness now account for >30% of the purchase decision.
And NIO's Average Selling Price was RMB406K in Q2 and RMB430K in July. Above Mercedes-Benz, BMW & Audi, according to Insurance Association data cited by management.
NIO isn't just selling more cars. It's building a premium brand people are willing to pay for.
$NIO
The whole point is:
25.12 swaps per station yesterday.
https://t.co/cAsCOTD015
If each swap station can handle more than 400 swaps per day, do you still think the deal makes no sense?
NIO power needs more swapping to make the infrastructure profitable and the only way to do that is adding compatible vehicles.