Agree IREN is the next hyperscaler, @Joseph_Invests.
A challenge for the smart $IREN bulls:
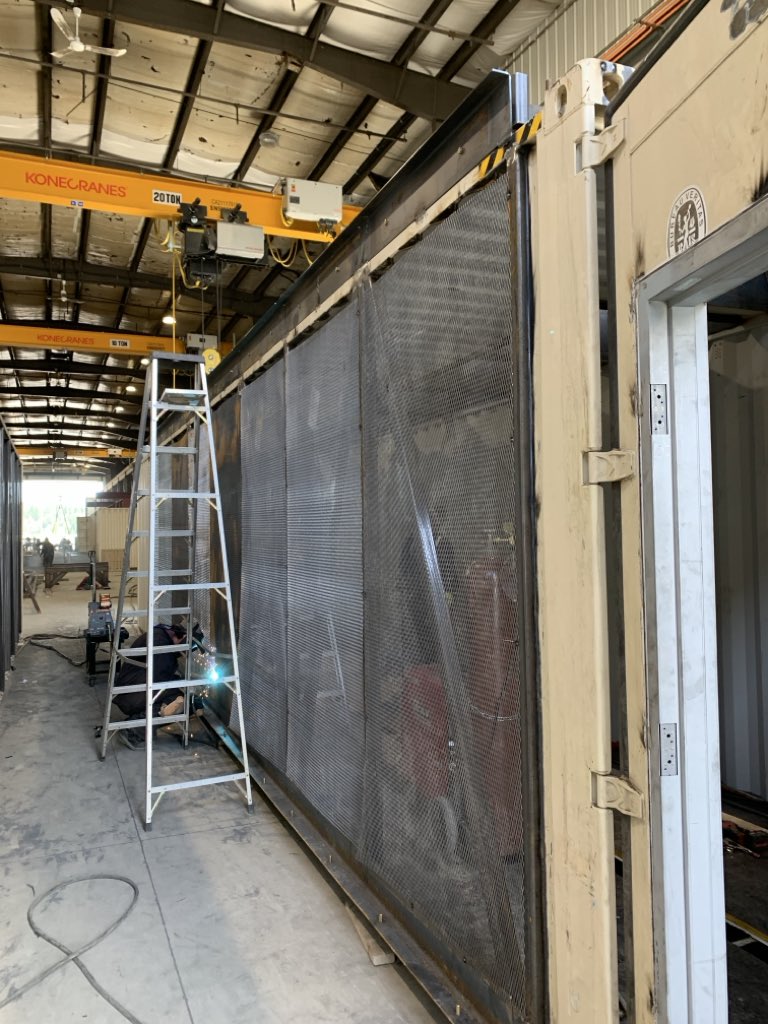
IREN has >5GW of secured power and a >35GW pipeline, and it isn't slowing down. On Thursday's call Dan was asked about NVIDIA's modular DSX PODs. His answer: IREN has had teams on modular and prefab construction for nine months, is working with NVIDIA on designs, and is still deciding whether to run the DSX POD exactly as presented.
The goal he named: simpler, faster builds with less labour on site.
My read: that's the path to factory-built PODs that deploy in weeks and are quickly upgradeable at any time.
Remember who they bought in 2020: PodTech. The name wasn't an accident. See photo from 2019.
While most of the space faces headwinds, I think IREN has huge tailwinds. What else does this unlock? Add your tailwinds below.
(Disclosure: large IREN shareholder, PodTech co-founder.)
@Agrippa_Inv@TheBigDegen Hey love your work! My thoughts are how can we get from under the tracking bitcoin and tracking Coreweave when they report bad news? How do these things get unhooked?
Because other neoclouds like CRWV and the dems winning scares them so they rate lower based on current market sentiment and what they believe are headwinds for this sector. But what they don’t realize is that $IREN is a standalone sector having left the other neoclouds in the dust.
Today is a day worth remembering for $IREN investors. We have witnessed firsthand just how absurd the market can become when driven by sentiment. Under normal circumstances, IREN's earnings report would have been more than strong enough to propel the stock toward a new all-time high. Yet ahead of its release, amid an atmosphere of overwhelming fear, the stock hit a new 52-week low.
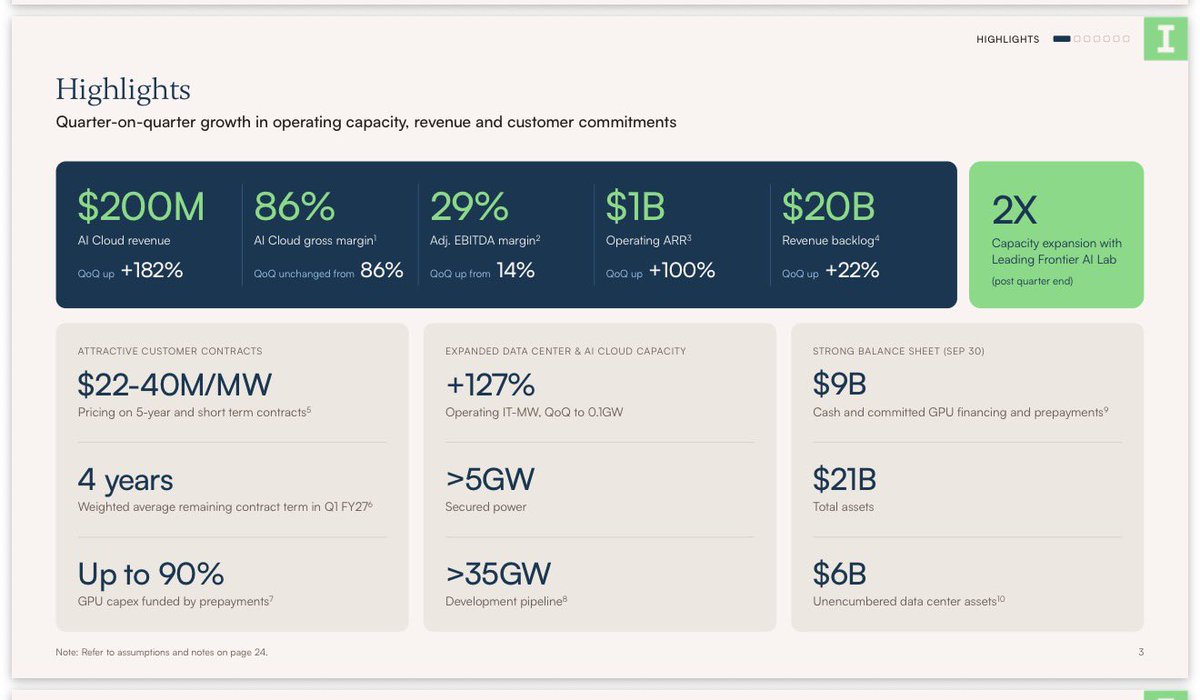
The numbers show that the team has done an outstanding job: an 86% gross margin, long-term pricing of $22 million per MW, short-term pricing of $40 million per MW, 90% GPU prepayments, and a faster overall payback period on hardware infrastructure investment, all of which will translate into better economics.
Then there is an additional 35 GW development pipeline.
This additional 35 GW pipeline is an overwhelming competitive advantage. No other player can match even one-third of this planned pipeline. IREN is a seasoned pioneer that began preparing sites earlier than almost anyone else in the industry. Its site selection criteria are extremely demanding. This is nothing like the approach taken by latecomers who jumped on the AI bandwagon, lowered their standards, and indiscriminately grabbed whatever sites they could find, regardless of cost.
Put simply, although IREN has made specific qualifying disclaimers regarding its planned 35 GW pipeline, I believe the proportion that can ultimately be realized will be high. This is because building such a pipeline requires a high degree of expertise, long-term follow-through, familiarity with local regulations and laws, and the combined ability to understand the construction and operational status of sites already brought online.
This is the first time IREN has disclosed the total size of its planned site pipeline. I expect this figure to be updated continuously going forward.
Recently, the entire AI industry has faced enormous and persistent selling pressure, driven by various doubts about AI's future development, as well as the Democratic Party's proposal to temporarily halt AI construction. Following yesterday's massive sell-off, this correction may well have found its bottom.
The Democrats' position represents an attempt to bring balance to the AI industry, not to stop its development. Nor could they stop it. The AI industry's economic connections have already become deeply embedded throughout the broader economy. That said, the previous approach of building without proper discipline, while disregarding people's livelihoods and environmental protection, genuinely needs to be brought under control.
I am very pleased that IREN is the standout student under this theme.
The value of its approach to environmental protection and community relations was completely overlooked in previous market speculation and valuations. Now we are beginning to see just how valuable these considerations really are.
I believe IREN will receive considerable recognition on this issue during the subsequent market recovery. This sell-off has sent the market an important message: no matter how fast you move, as illustrated by companies such as SpaceX and Nebius, violating regulations or ignoring environmental concerns and residents' demands may bring consequences far more serious than simple fines. Your projects could actually be suspended!
IREN's enormous moat is not simply about having high-quality sites, a large total capacity, and broad geographic distribution. More importantly, it is about prioritizing overall economics, environmental protection, green energy, and constructive community engagement, while contributing to local economic development and employment.
These are advantages that cannot be matched by approaches that attempt to bypass regulatory oversight and grid interconnection queues through behind-the-meter power generation.
I have always maintained that IREN's core team possesses exceptional foresight and strategic capabilities. A series of decisions has reinforced this assessment. In this particular area, I believe its strategic vision even surpasses that of Elon Musk.
The 35 GW figure also reveals another potential possibility:
High-quality sites that meet IREN's requirements may have been on this team's application and waiting lists for a long time. That window of opportunity may already have closed.
All of this is entirely consistent with the professionalism of a seasoned infrastructure team. As a result, IREN has built the industry's best portfolio of sites, with a quality, scale, and geographic reach far beyond those of its competitors. This has become Moat 1.0.
IREN's Moat 2.0 is now under construction.
If Moat 1.0 is primarily about securing advantages for IREN itself, then the emerging Moat 2.0 represents a systematic architecture with genuine industry-wide reach and influence. It will not only benefit IREN but also create value for others.
This will position IREN at the commanding heights of the industry, enabling it to become an important participant and leader in the new AI industry through a wide variety of major partnerships.
I will attempt to describe the state of IREN's Moat 2.0. This is what I consider the most important observation and the most important analysis I have written. Stay tuned!
For anyone with cash on the side lines, this is the easiest 'buy the dip opportunity' on $IREN of your lifetime.... NFA.
This earnings release couldn't have been any better.
🚨 @IREN_Ltd Fiscal Q1 2027: AI Cloud Revenue Nearly Triples 🚨
⚡ $200M AI Cloud revenue — up 182% quarter over quarter at an 86% gross margin
⚡ $1B operating annual recurring revenue — doubled in a single quarter
⚡ 29% adjusted EBITDA margin — more than doubled from 14% last quarter
⚡ $20B revenue backlog — up 22%, ~4-year weighted average term, priced at $22–40M per MW
⚡ 2X capacity expansion with a leading frontier AI lab — signed after quarter end
⚡ >5GW secured power, >35GW pipeline — backed by $9B in cash, committed chip financing and prepayments
Margins doubling while the backlog compounds: $IREN is building a hyperscale AI cloud on a balance sheet most neoclouds can't match.
🚨 $IREN's >35 GW Pipeline
They FINALLY did it.... I can't believe $IREN finally revealed the size of their massive pipeline.
For years investors were begging management to reveal the size of their power pipeline.
It only took the stock to crash 58% YTD for them to reveal this very relevant piece of info.
But honestly, wow. No other neocloud, or colo provider for that matter, even comes close to 35 GW...
$IREN: First Strong Execution Quarter Since Q3 2025
Revenue: Execution
$IREN has delivered 228m ARR of which 28m is BTC, ~170-180m is bare metal GPUs and 20-30m is Mirantis managed services. For reference, $NBIS hit 227m in Q4 2025 and went on a great run in the following quarters based on revenue growth.
Mirantis managed services will scale well now they have IREN bare metal compute to deploy to. This is evidenced by their managed services level economics in some of their newer contracts.
$IREN is are getting a long term 5-year contract at 22m/MW and 90% GPU prepayment. GPU cost is ~64% of total cost so that's ~57.6% of total cost.
$IREN is also able to participate in short term contracts at 40m/MW for likely B300s.
Power Pipeline and Margins
Many companies publish their pipeline as secured power. IREN has 5.6GW of secured power and for the first time ever, $IREN has published that they have a 35GW pipeline.
If $BE fuel cells stay valuable that 35GW pipeline remains valuable as it uses renewable energy rather than LNG. Not only is renewable energy easier to meet regulations but also much cheaper. Over 15 years, a 1GW site using West Texas renewables saves 11.82B over LNG as calculated from the Riot x Anthropic deal (1).
This advantage in energy cost is what allows $IREN to have 86% AI Cloud gross margins on revenue pre-dating it's managed services.
Uptime and Service Quality
The key metric for uptime is revenue because penalties are shown in decreased revenue. The key metric for service quality is renewals.
Despite all the @SemiAnalysis_ FUD, IREN has secured expansions with not only FireworksAI and TogetherAI but now a 2x capacity expansion with a Leading Frontier AI Lab. At the very least, this means what issues IREN has, the customer sees IREN capable of fixing it in the near term.
Financial Strength
IREN has 9B in cash and committed GPU financing and prepayments and 21B in total assets which includes delivered GPUs and datacenter equipment built and pre-built.
Crucially it has 6B in data center assets that it can do asset back financing against. This will be funding without dilution. Yes today there was a scare article stating that banks were looking to sell ORCL's datacenter loans but those are sites that ORCL is facing delays on.
Horizon Delays
Yes, my information that all of 4B will all be this quarter is wrong and it's now confirmed that there is a 1 month delay on some of the 4B ARR and clarified as customer requested change and supplier timing.
This is the networking changes I've been talking about and the liquid cooling equipment which had an issue and needs to be replaced. I have information that this equipment is separate from the sulfur contamination which was flushed earlier and will be billable with insurance as a defect.
At the end of the day, B300s are netting 22m/MW for 5 year contracts. If $MSFT backs out that would be great for $IREN as the GB300s would net more than 22m/MW which is well over the 9.7m/MW it's getting now. This is why $MSFT will not back out.
Yes, I am disappointed in this but H1 billing with GB300 Exemplar Status tested as a 19k GPU Cluster has me not worried that H2-4 will finish.
Note that the Exemplar Status on 19k GB300s tested as a cluster confirm that the networking is not an $IREN issue but optimization issue for $MSFT's specific workload. This is most likely due to some misunderstanding in Infiniband specific details related to the model that $MSFT is training. This will not be a big problem in managed services as inference clusters are easier to network.
I do not know how much of the Horizons are part of the delayed whether it's H2, H4 or both but H2 is undergoing GPU deployments. I am glad to see that Mackenzie Halls 1-4 and Aircooled Childress Halls 1-3 are undergoing GPU deployments and will be billing by either EOY or Jan/Feb.
Customer Mix
It is now confirmed that Prometheus, @baseten, Higgsfield are all customer! These are also key $CRWV and $NBIS customers and shows that $IREN has the managed services needed to serve these fast growing AI Natives.
These AI Natives do their due diligence on managed services and are a better signal than @SemiAnalysis_ ClusterMax Rankings. At the end of the day, AI Natives put their money as skin in game while @SemiAnalysis_ is getting paid by clients and has sponsorships with certain clouds to talk the talk.
Upside
IREN had 1 year contracts on some of their H100s. Now they are contracting them at over double the price! This is fully paid off and a huge tailwind.
At today's GPU prices, and VR200s on the first 200MW IT of SW1, $IREN will be able to achieve 16.5B+ ARR by end of 2027.
Furthermore, with 90% GPU prepay, $IREN is getting 0.4yr payback on GPUs and 2.4yrs on GPU + Datacenter full payback. Datacenter reits are trading at a premium right now.