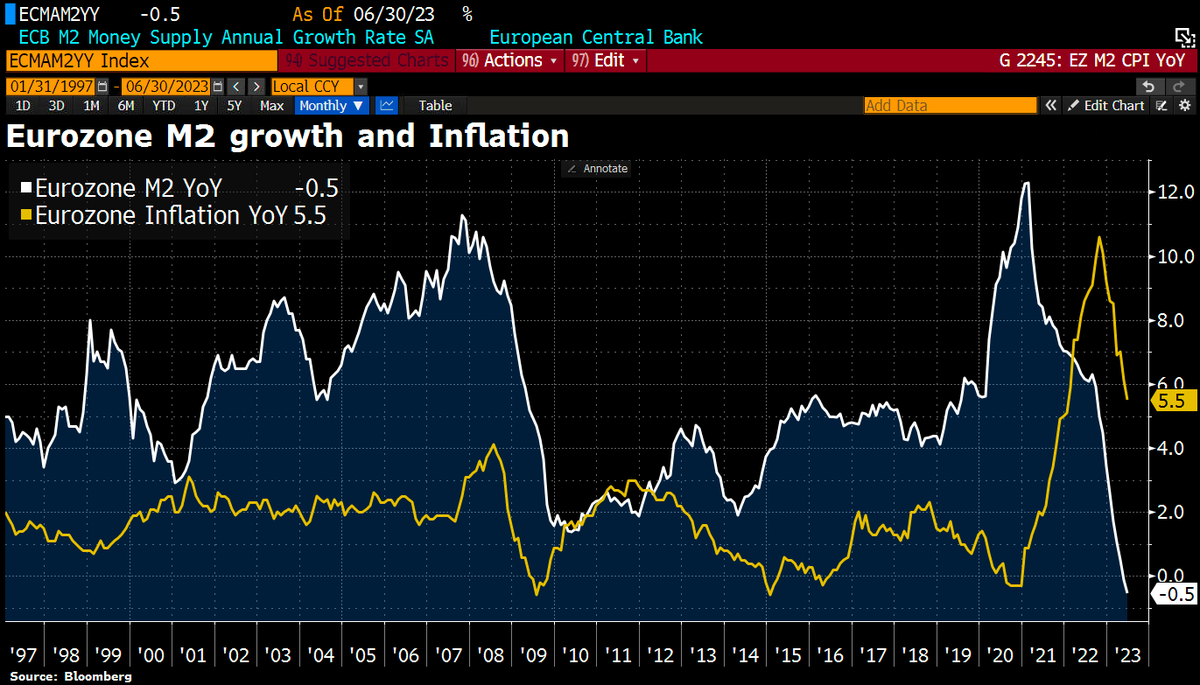
OOPS! #Eurozone M2 money growth turned NEGATIVE for the first time in Eurozone history, in a promising sign for #inflation. M2 growth revised to -0.1% in May from initially +0.3%, and falls deeper into negative territory in June to -0.5%.
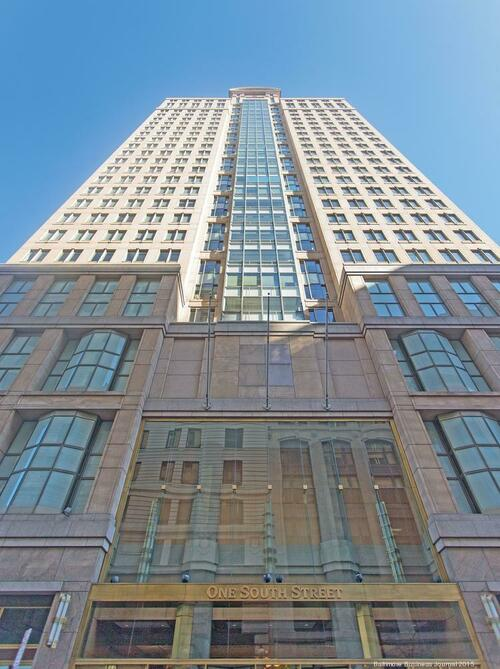
Immobilier commercial aux Etats-Unis : ça commence. Une tour de bureaux de 30 étages à Baltimore, a été vendue dans la panique avec une décote de 69 % par rapport à l'achat de la tour en 2015. Il s'agissait de la 2ème vente de ce type dans l'ère post-Covid ...
Le gouvernement prévoit d'augmenter le prix de l'électricité de 76% d'ici 2025.
En trois ans, le prix de l'électricité aura donc plus que doubler avec une hausse globale des tarifs de +105% entre 2022 et 2025. (CNEWS)
Mercedes operating margin: 11.9%
Mercedes PE ratio: 5.5x
BMW operating margin: 10.7%
BMW PE ratio: 6.2X
$TSLA operating margin: 9.6%
$TSLA PE ratio based on .78 GAAP Q2 annualized to $3.12 and today's close of $291.26: 93x
THIS SCAM HAS A PLUNGE IN ITS FUTURE
Retail is buying stocks at a record pace going into earnings; institutions are still on the sidelines (mostly bearish) and only dipping in because of FOMO
https://t.co/xkcUiLW20m
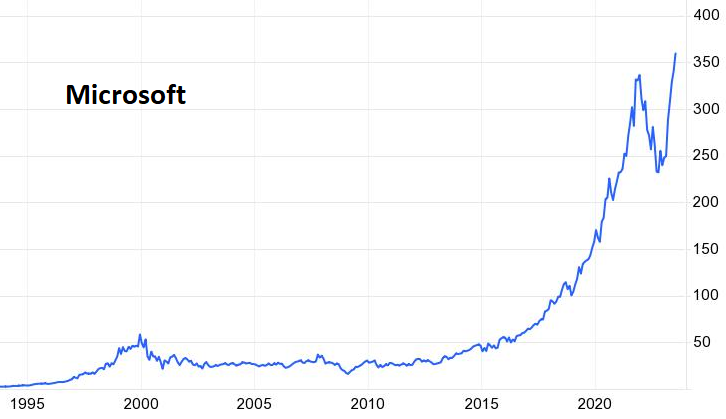
Bonjour ! Bienvenue dans un monde où Microsoft et Nvidia (combinés) ont gagné 175 mds USD de capitalisation boursière sur la seule séance d’hier, soit plus que la capitalisation boursière de 462 sociétés du S&P et plus que la valeur de Nike, Wells Fargo, Walt Disney ou MS... !
Selon Bloomberg, les entreprises du S&P 500 devraient enregistrer une baisse de 9 % de leurs bénéfices au Q2.
En Europe, la situation pourrait être encore pire, avec une chute prévue de 12 %.
Le crash-test des bénéfices arrive à grands pas 👇🧵
⚠️ #BankingCrisis update ⚠️
The banks reporting season has begun and, of course, $JPM $C $WFC all "beat" expectations, sending their #stocks higher in pre-market. However, when people started moving from reading the (cheerful) press releases to the (boring and lengthy) financial statements, bank #stocks quickly pared their gains and $BKX closed down 2.35% on Friday. 😅
What the hell did investors find in the financials that caused such a change of heart?🤔
Here are the interesting things I found so far:
1. $JPM "fair value" losses in their HTM Debt Securities book increased to 33bn$, and No here $FRC has nothing to do with it.
2. $JPM lost ~900m$ in their securities investments. What's wrong with this? These are 🥜 for Jamie! What's wrong is that this is the fourth quarter in a row $JPM books a ~900m$ loss despite the ups and downs in the market. That's a bit too regular, isn't it? However, if we compare this figure with the decrease in the HTM balance QoQ, $JPM has been selling HTM securities at ~30%, ~7.5%, ~20% discounts in Q2-23, Q1-23, and Q4-22. This is starting to be more aligned with the swings in the market, isn't it?
3. Now look at point 1 and 2 together. Do you notice anything strange? $JPM estimates a "fair value" of their HTM securities only 8% below book value, but then the price they have been selling their HTM asset is at a 30% discount! If we apply an MTM to HTM assets using what the bank itself is getting from the market, $JPM is carrying a 123bn$ MTM loss in their HTM books. 🥶
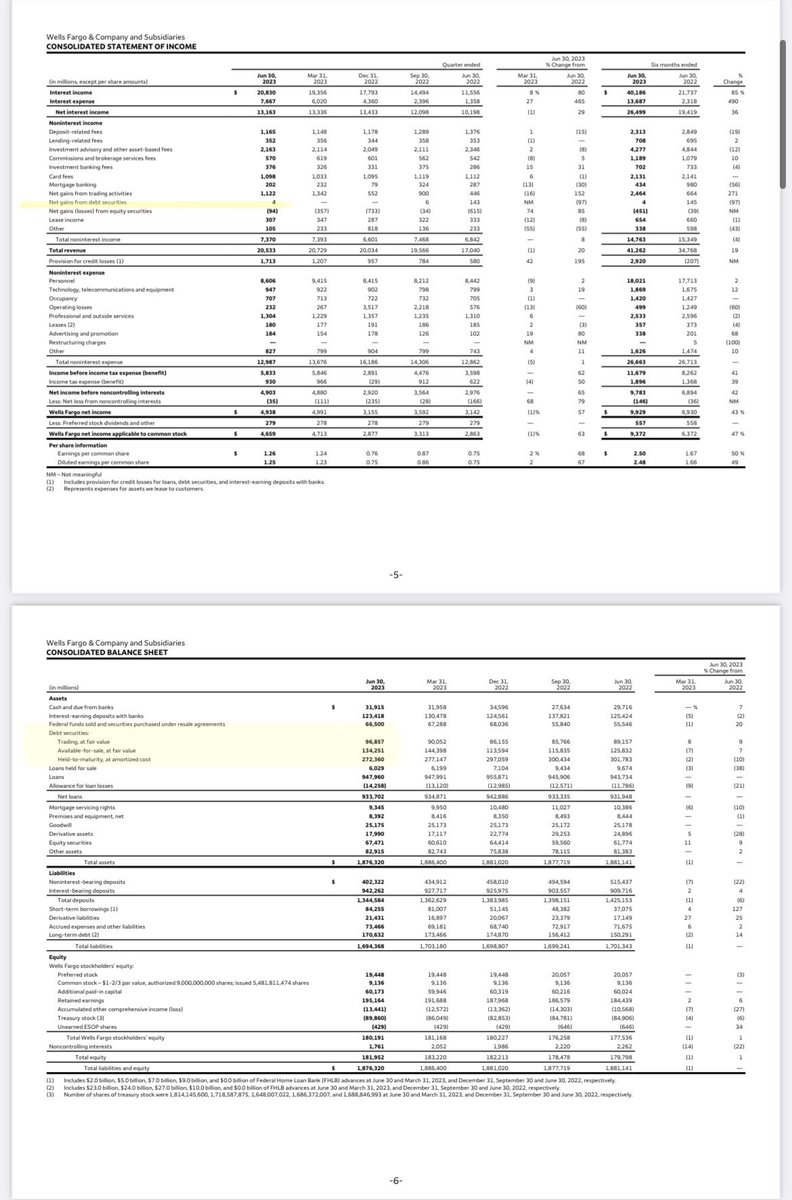
4. While at least $JPM still shares important data (wisely hidden in the various footnotes 😉), $C and $WFC don't bother to do so. However, from what they cannot avoid disclosing, we can easily see how both banks really pushed the limits in terms of accounting acrobatics this time around. For example, yesterday I flagged $WFC reported a 4m$ GAIN for Q2-23 related to their Debt Securities assets. $C did even "better," booking a 49m$ GAIN! 🙄
Both banks hold ~500bn$ of Debt Securities between AFS and HTM, and they are doing far better than Jamie in managing them… yes, if you believe in Santa and unicorns… 🤣
5. If we apply the same 30% MTM discounted value Jamie is getting to $C and $WFC, both banks might be hiding ~150bn$ in MTM losses each in their Debt Securities books. 🤷🏻♂️
6. What about Credit Losses? While $JPM and $WFC increased their provisions by 28% and 41% vs Q1, $C provisions decreased 8%… Cmon Jane! 🤣 However, none of these 3 banks still made any meaningful provision against their CRE books. Among them, I find $WFC "assessment" is the funniest one: "the vast majority of the [CIB] portfolio is institutional quality and with high-calibre sponsors." Ehmm… so what? Are those CRE loans guaranteed? No. Is "institutional quality" reassuring when filings for chapter 11 are at GFC levels? So basically $WFC is telling us that ~103bn$ of CRE loans they hold are "good" because they say so. 😅🫣
7. Last but not least, Deposits. $JPM (including $FRC) +21bn vs -11bn$ for $C and -9bn$ for $WFC. According to FED non-adjusted data, Large US domestic banks as a whole lost 152bn$ in deposits during Q2. Then if the net for the first 3 banks that reported is +2bn$, it means the remaining out there lost 154bn$ in deposits right? 🤷🏻♂️ Someone might have bleeding big time then..
Considering all that has been said so far, no wonder investors started dumping bank #stocks yesterday.
$BKX is down ~19% YTD vs $QQQ +43%. This is the equivalent of an F1 car leading a race without fuel. It's simply not possible for a car to keep racing without fuel unless you are playing a video game. Believing that you can do it in reality is equivalent to believing in Santa and unicorns
If this is the beginning of the banks reporting season, I foresee plenty of games of smoke and mirrors along with nasty surprises ahead (and not only for bank stocks, sorry)⚠️
Links to financials: https://t.co/69zDykJlou
https://t.co/2ImEMKG2RB
https://t.co/WODMyy2MAs
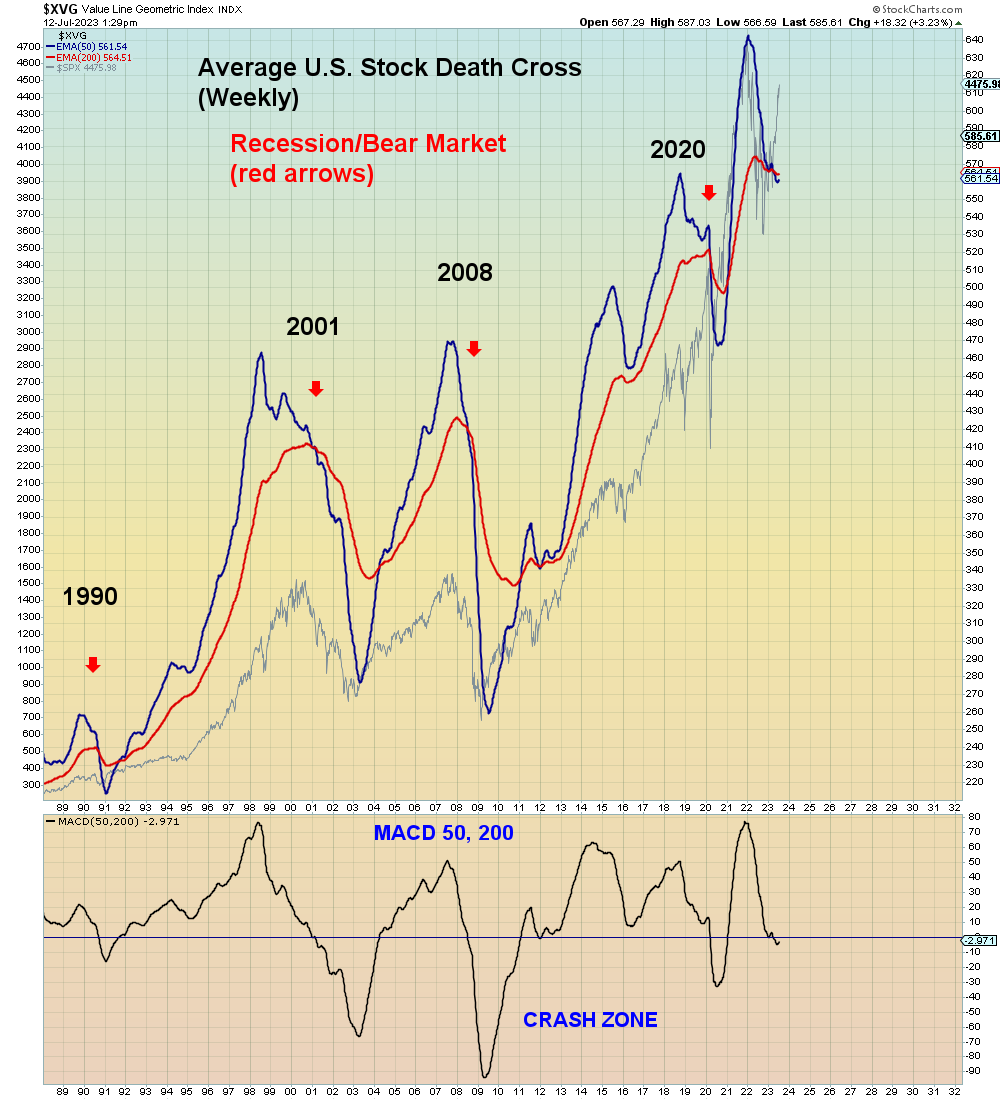
I would point out that the average stock remains in a death cross on a weekly basis.
This signal has never failed to produce an S&P crash in 30 years.
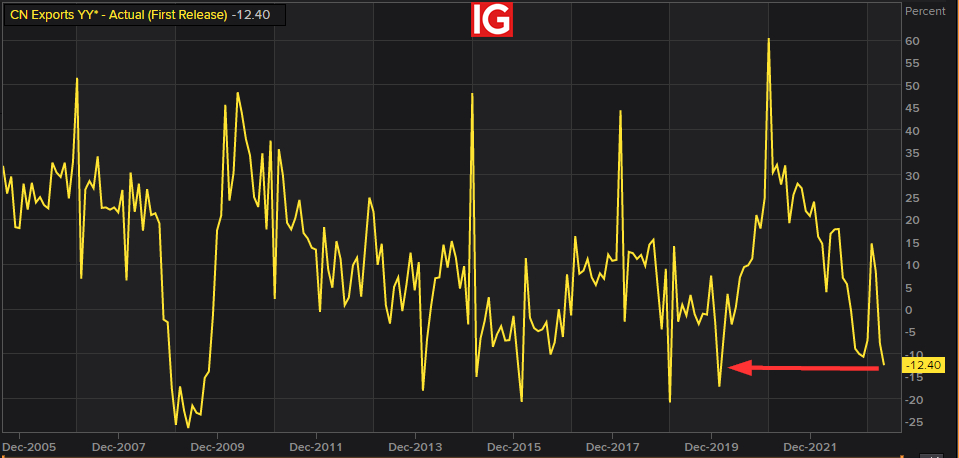
Marasme sur les exportations chinoises --> -12.4% en juin y/y soit le plus fort repli depuis février 2020 (en pleine crise Covid)
Le ralentissement de la demande mondiale est visible
(et -6.8% pour les import° vs préc -4.5%...)