I love @zerohedge but you guys are sending $ price charts for a bond that trades on spread to treasuries. We were a large byr of Beignet when the deal was issued last year and monetized the investment over time at much tighter levels than where it’s trading now. We were also excited to support @Meta in their Sopapilla financing this summer. Both bonds are substantially tighter from issuance. The Beignet (Hyperion) priced at 260/10y and now trades at 220/10y. Most of the decline you are showing is simply a move in rates. There are likely plenty of problems to be found over time in the AI financing chain but I’m not sure this is one of them. I would focus on less built projects with weaker counterparties in NIMBY heavy jurisdictions if you want to go looking for canaries.
registered for a fresh domain for my side project
threw on cloudflare pages for backend
2k+ hits from what appears to be llm crawlers within 48 hours (?)
google search console yet to log any organic pageviews - any one have a clue where this is coming from? @CloudflareDev
One big problem with codex usage limits is I now run both a bunch of personal life chores and tasks with codex. So if I vibecode too close to the sun I brick my day planner & workout log for a few days. So I end up being too conservative to keep my small personal infra alive and don’t run ambitious loops to limit max and test codex
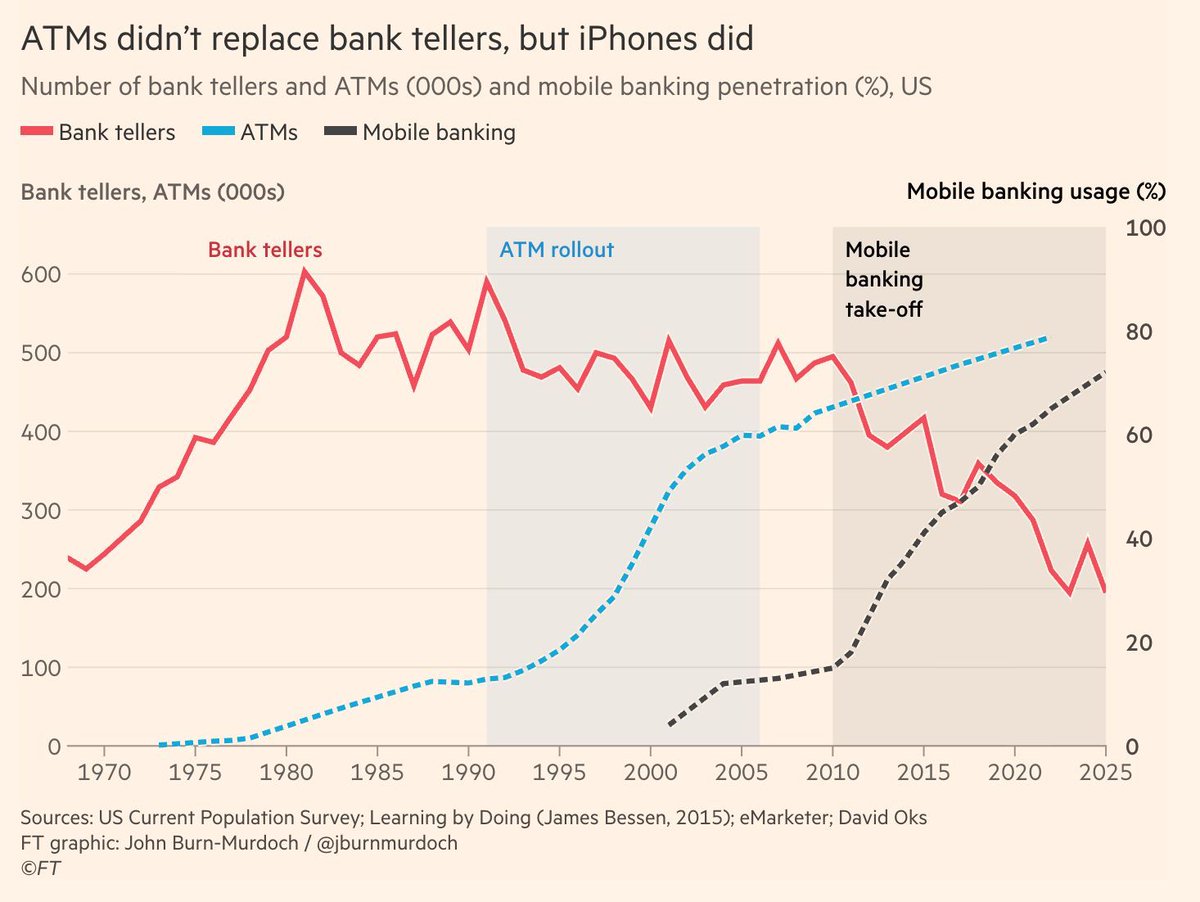
This graph shows why it’s so hard to predict what a new technology will mean for jobs.
It would've been natural to predict the decline of bank teller jobs when ATMs came out—which didn’t happen. It would’ve required a larger leap to do so when Apple released the iPhone—which did. https://t.co/jH5OaCor5i
Two comments
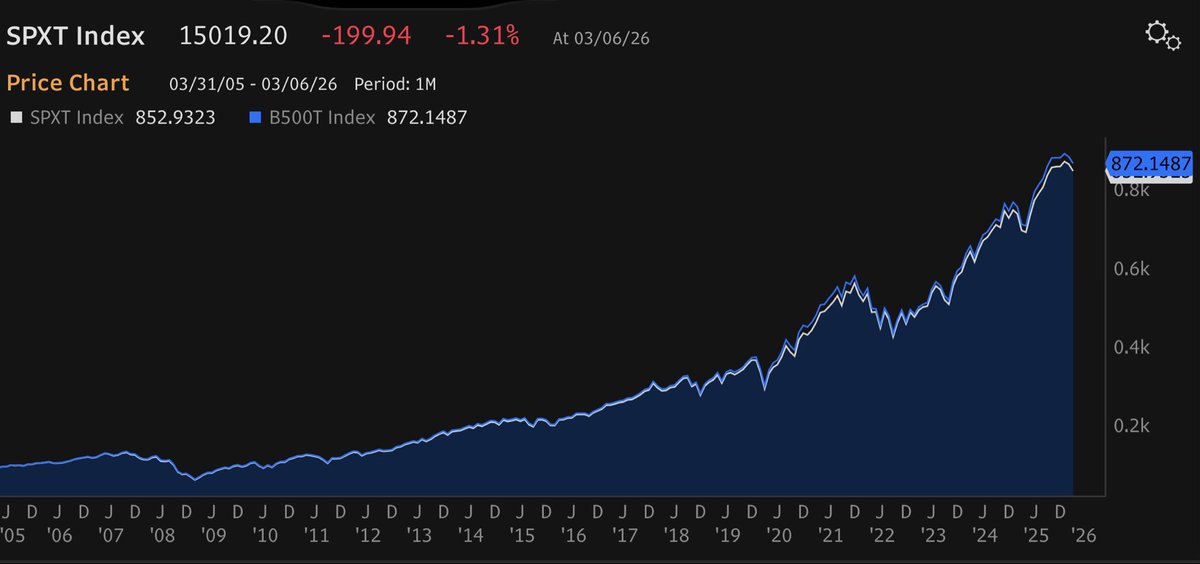
1. The idea of S&P 500 index adding expensive stocks that subsequently underperform post addition is vastly overstated by discretionary managers who aren’t very quantitative. Do some simple maths and returns attribution. Take a look at the weights at which expensive stocks were added. They are tiny. Ultimately they don’t matter in the grand schemes.
2. The reason or primary fault of these additions is not that the index committee added these stocks at too expensive valuations. Au contraire, the issue is that S&P imposes some arbitrary rules about four quarters of profitability that delay the entry of stocks that would’ve qualified on market cap ranking hence missing a lot of the explosive stock appreciation.
A benchmark index isn’t supposed to also reflect the discretionary judgement of an investment committee about quality or whatever. It’s supposed to reflect the market as is as much as possible, bubble or otherwise. The overlay of discretionary rules was a vestige of the past when S&P 500 index wanted to both a passive benchmark AND a good investment vehicle. Today, we know how to construct quality factor indices much more explicitly.
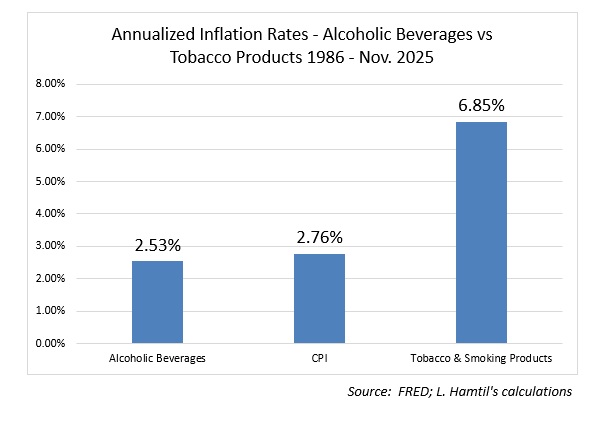
The problem I see with that analogy is that the pricing power for alcoholic beverages is not anything close to tobacco. In fact, over the last ~40 years, CPI for alcoholic beverages has < general inflation; tobacco has more than 2x CPI
I think the Fed should cut by 50 bp. I feel we overanalyze each data point for what it means on timing & size of rate move rather than ask what *level* of rates is appropriate. I think it's obvious the right level is well below where we are now. My reasons ... https://t.co/IXOGnF9SH5
PE is starting to really buy again but exits continue to go down. This is creating a very difficult fund raising environment where LPs aren't getting money back and have less capital to allocate.
My view is that after we get the first cut you are going to see a rush of PE firms looking to sell. This should improve the fund raising environment a bit but I still think we are in a new normal for fund raising....
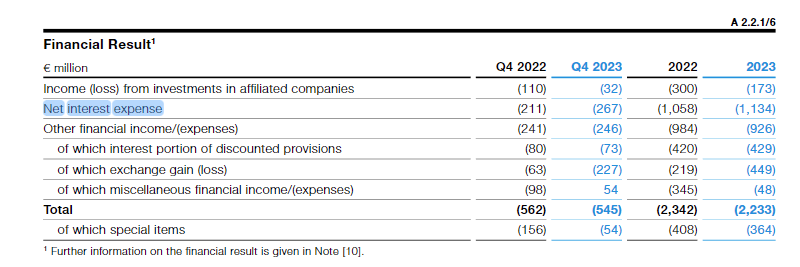
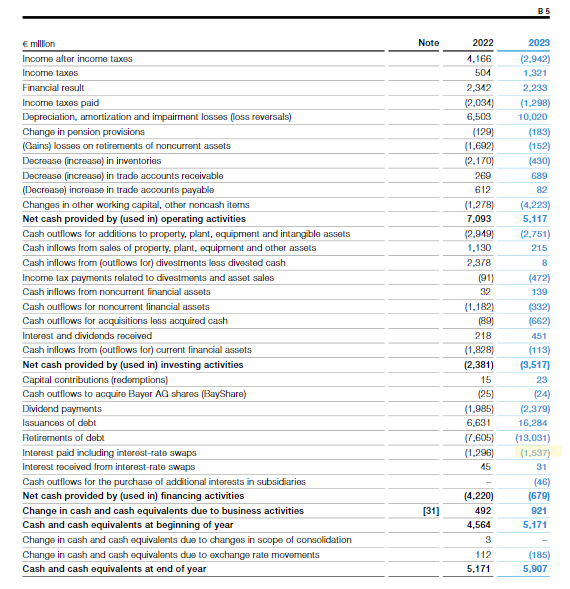
The European convention of putting interest expense outside of operating cash flows is insane.
If you look at the CF statement of Bayer AG you might think the company did around $2.5b of FCF in 2023 ($5b operating cash flow - $2.5b in capex etc excluding acquisitions).
But then you realize that they had $1.5b in interest paid.... and that they had a $2.3b of "financial result" which has been added back in operating cash flows to generate the $5b.
So, actually, this company had ZERO true FCF in 2023 despite $6b of adjusted net income.
No wonder it trades at 4x (adjusted!) PE ratio.