The US can't afford higher rates... Warsh knows that.
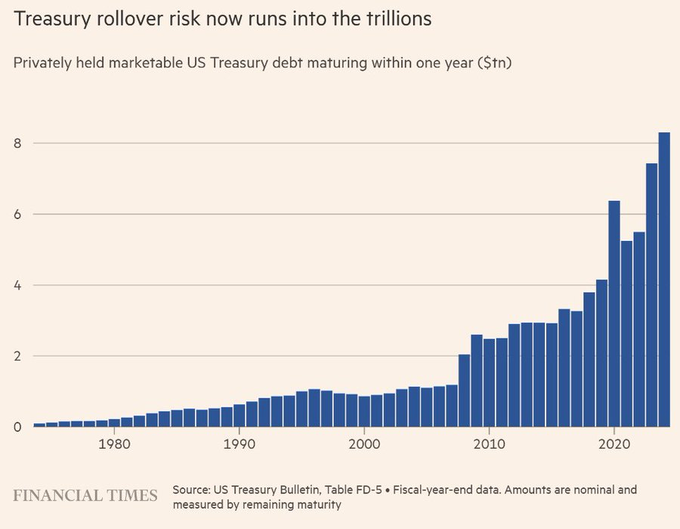
- Over the next 12 months, ~$8T in USTs will need to be rolled over.
- The average coupon is ~3.3%.
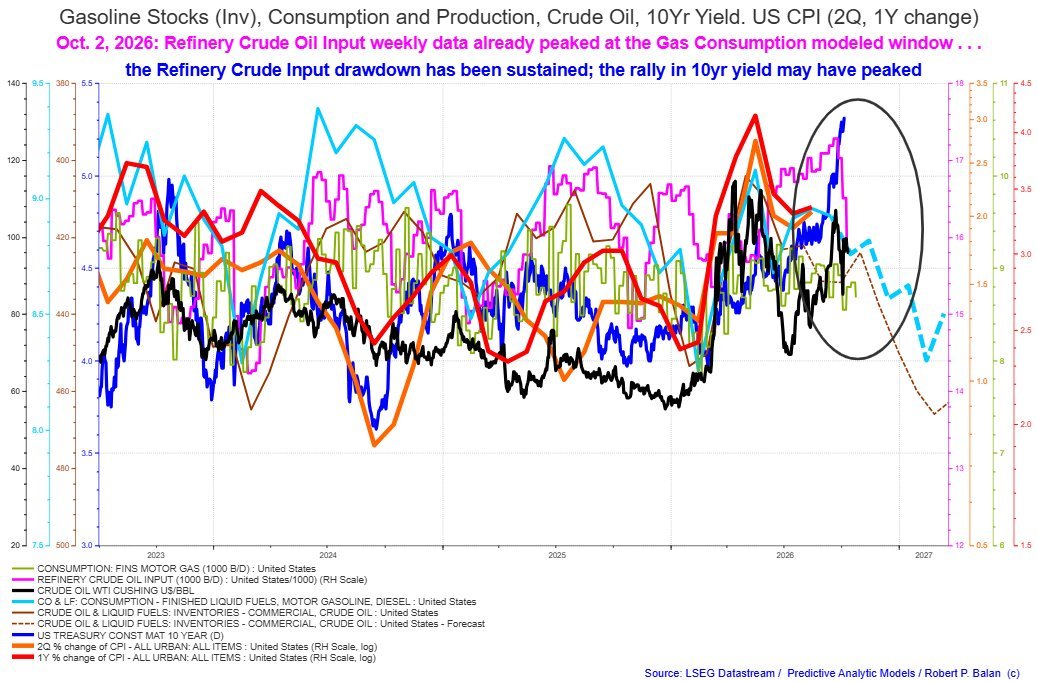
- The US 10Y yield is ~5%.
Refinancing that $8T at today's 10Y yield would add ~$136B in annual interest costs...
And that's before factoring in the interest burden from an ongoing $2T annual deficit.
Meanwhile, with long-term USTs becoming increasingly "bidless," Bessent is shifting more issuance toward short-term debt...
Shortening the refinancing cycle and making the US even more vulnerable to rising rates.
Volcker could crush inflation with double-digit interest rates because inflation had already helped reduce debt to GDP from ~120% to ~30%.
Today, we're back at ~120%...
First, you inflate away the debt, then, you raise rates to crush inflation.
We're still in the inflation phase of the cycle...
You know what that means.
This doesn’t happen often.
$SPY just logged 3 distribution days in a row (lower close on higher volume each day) with a -3.3% drop.
This chart highlights every time SPY had at least 3 distribution days in a row and fell at least 3%.
As long as we don’t have another pandemic on our hands, these have marked some great bottoms.
The Fed is printing money to buy US Treasury bills... more than during Covid.
- Covid: ~$320B
- Last 9 months: ~$355B
Everyone is talking about Fed rate hikes... no one is talking about Warsh printing money Covid-style to buy UST bills.
Some purchases are offset by declining holdings of MBS and other assets.
But the Fed's total balance sheet has still expanded by ~$160B.
Meanwhile, Bessent is issuing more UST bills to buy back long-term US debt.
In other words, the Treasury is shifting debt issuance toward the front end while the Fed is creating money to absorb more of that supply.
QE in disguise...
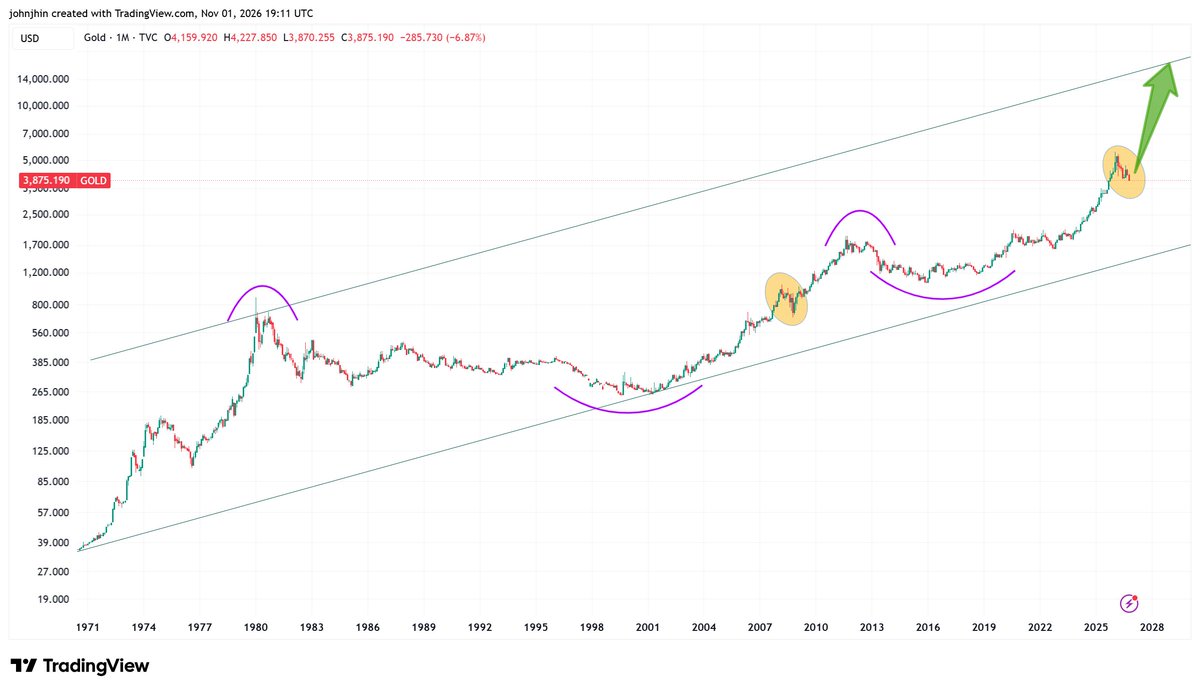
We don't own enough hard assets for what's coming.
Silver: Range expansion at the end of a move w close outside the Keltner Channels is a sign of a selling climax. The market still needs to come "into balance" (three bars price overlap). or, take out the high of the climax bar within 2 days.
$POET (October 26, 2026-Monthly Chart)
I’ve never been a fan of small stocks. $POET remains in a downtrend, with a new volatility hole forming on the monthly chart. $5.40 needs to hold — a break below it would signal a loss of price momentum in the long term, and a breach of the lower boundary at $4.16 would likely trigger a sharp plummet.
@TriggerTrades In your 5 waves down it looks like the top of wave 4 exceeds into wave 1. I thought that invalidates wave 4 from being wave 4. Please explain.
Not sure why you‘re picking on @KCTrades777 . He is legit. I am one of his many happy subscribers. I listen to him every single day and he puts out solid trades. So what if he makes some money. He should be making more honestly. I‘ve subscribed to many traders and he is the one I’m sticking with.
$IQE Earnings are out
IQE has reported a strong first half of 2026, with
revenue increasing 43% year-over-year to £64.6 million.
Wireless revenue grew 40% to £26.0 million, while
Photonics revenue increased 45% to £38.5 million,
supported by demand from AI, data centres, and
defence-related programmes.
Adjusted EBITDA improved significantly to £6.0 million,
compared with £0.4 million in H1 2025. The company
also reported £41.6 million in cash and cash
equivalents, with adjusted net cash of £30.2 million
following its strategic review and fundraising.