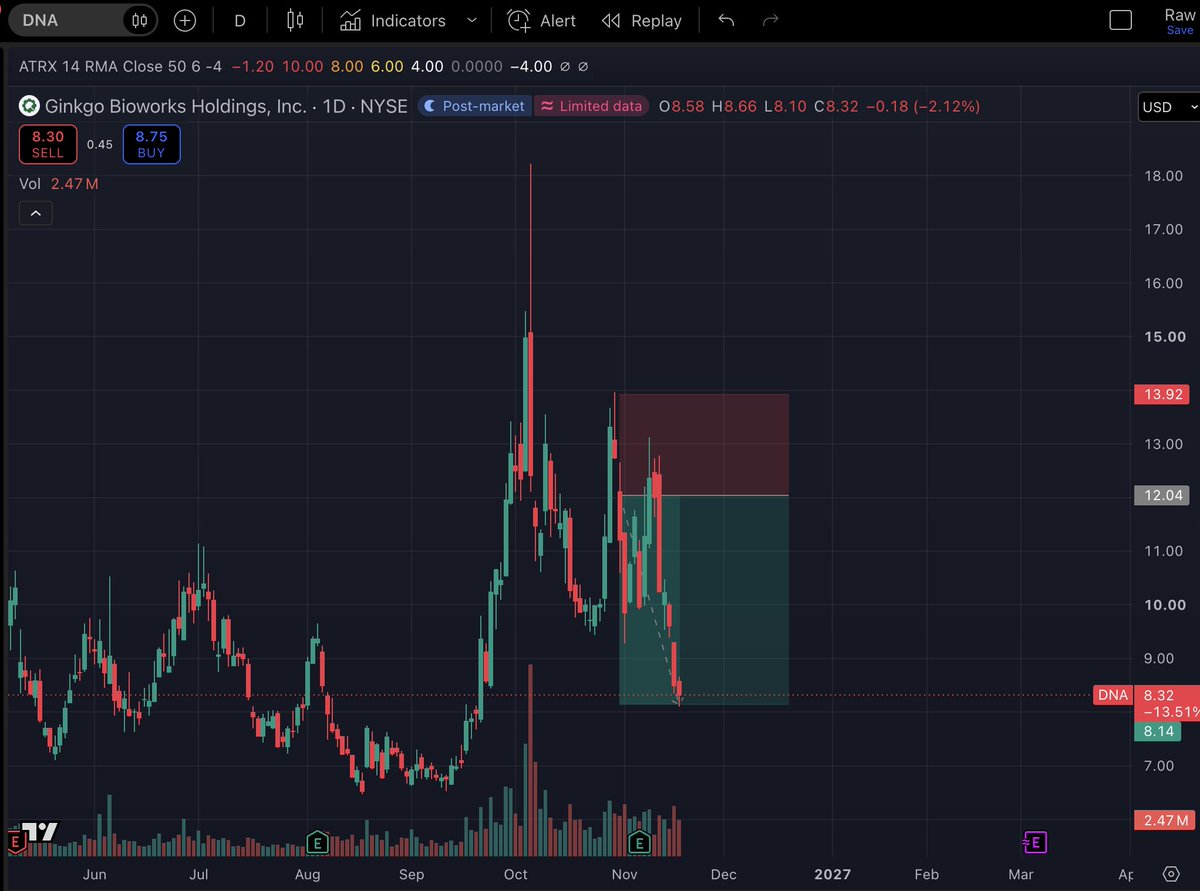
Closed 2 shorts today $AMD and $DNA
$NVDA just put out good numbers so taking profits on my $AMD short here
$14k profit from the 2 shorts for a +5% return on total port
Not too shabby
You have to subtract project debt
3 contracted sites of $CIFR at ~7% cap rates
= ~$10B
-$4.5B project debt
= $5.5B net pv of contracted sites
-$1.5B in net corporate liabilities (convert notes + unrestricted cash)
=$4b or $7.40 per share acquisition/liquidation value (if you assign no value to their pipeline)
The issue is this is all data center contracts don't deserve the same cap rate and not every bitcoin miner -> PSP has achieved the same amount of financing
$CIFR has achieved enough financing to build out its existing contracts and has better credit tenants
financing these data centers has been under a lot of stress and discount rates themselves have been rising recently so you need to discount that stress showing up in less favorable financing terms for the contracted MWs
Amazon as a tenant and fluidstack with a google backstop deserve lower cap rates
compared to $RIOT with all their MWs signed to Anthropic
Got Stopped out of $SBM.AX at A$0.69
put my stop at a new low since the rally on the announcement of Simberi sale
Still bullish on this name but right now the macro is driving flows
Gold I am not bullish on in the short-medium term because of liquidity environment (rising of yields, real yields, & dollar)
So going to wait on the sidelines a bit and see if I can get a better entry until the timeframe where idio catalysts for the name start to appear
Then idio may take the driver seat again of the share price
Now short $BGIN a shitco that popped on news that don't reflect a fundamental change on the business and shitcos in this environment of tightening liquidity tend to be treated like the reality of the shitco they are
Now net short on my positioning right now and happy with it based on my macro view
1/ I'm short $AMD here. Not because I'm bearish AI. Because of what it does to my book.
Macro → factor → idio.
2/ Macro: I'm bearish risk assets short term. A Fed hiking cycle is getting priced and Iran is heating up again. 10Y real yields are at the top of their 10-year range.
High beta gets hit first by negative liquidity environments. $AMD moves about 2.7% for every 1% in the Nasdaq.
3/ Factor: my biggest long is $CIFR. I'm bullish the name, on a medium term horizon.
Cipher carries a lot of AI and neocloud beta. AMD has run 0.62 correlated with it, 0.74 with a neocloud basket. Shorting AMD strips that out and leaves me with more of Cipher's own story.
And allows me to ride my $CIFR long through my short-term bearish view on risk assets
4/ Idio: AMD/NVDA ratio just hit a 2-year high, about 2.7σ above it's 21-day average
AMD is catching flows from the Jensen news.
IMO Jensen news is not going to change how much more earnings/market share $AMD will take from Nvidia.
So I think the idio move of $AMD and it's gap to $NVDA is more likely to close.
6/ Why one short matters for the whole portfolio:
It greatly improved my total portfolio exposures to align with my short-term macro view.
Nasdaq beta: 0.77 → 0.18
Net long: 45% → 24%
Book vol: 37% → 31%
7/ Risk: stop above 609, target around 469, about a month.
Risking 100bps on this $AMD short here
1/ I'm short $AMD here. Not because I'm bearish AI. Because of what it does to my book.
Macro → factor → idio.
2/ Macro: I'm bearish risk assets short term. A Fed hiking cycle is getting priced and Iran is heating up again. 10Y real yields are at the top of their 10-year range.
High beta gets hit first by negative liquidity environments. $AMD moves about 2.7% for every 1% in the Nasdaq.
3/ Factor: my biggest long is $CIFR. I'm bullish the name, on a medium term horizon.
Cipher carries a lot of AI and neocloud beta. AMD has run 0.62 correlated with it, 0.74 with a neocloud basket. Shorting AMD strips that out and leaves me with more of Cipher's own story.
And allows me to ride my $CIFR long through my short-term bearish view on risk assets
4/ Idio: AMD/NVDA ratio just hit a 2-year high, about 2.7σ above it's 21-day average
AMD is catching flows from the Jensen news.
IMO Jensen news is not going to change how much more earnings/market share $AMD will take from Nvidia.
So I think the idio move of $AMD and it's gap to $NVDA is more likely to close.
6/ Why one short matters for the whole portfolio:
It greatly improved my total portfolio exposures to align with my short-term macro view.
Nasdaq beta: 0.77 → 0.18
Net long: 45% → 24%
Book vol: 37% → 31%
7/ Risk: stop above 609, target around 469, about a month.
Risking 100bps on this $AMD short here
What was the difference between my winners and losers?
Timing of buys and sells
For my biggest winners
- $LPKF and $SOI I bought during march when Iran war broke out
Capital was in a flight to safety while AI fundamentals continued to improve. I was able to time my buys right when capital return to risk & AI and when the market discovered attractive AI themes like photonics for $SOI and glass substrates for $LPKF.
Then I was able to use my technical indicators and fundamental valuation metrics to time my sales
technical indicators showed px action rising fast which made marginal upside difficult
&
px reflected a bull case valuation for fundamentals of the companies
For $025560 Mirae corp I was able to buy a large position in May. $SMH and semis were in a strong uptrend.
I was just able to find this name before a majority of other people found it.
Modeled it and found it was very cheap relative to other AI names and thought it was able to squeeze upwards if retail and other people found it.
They did and I sold a lot of it in July when I thought the share px reflected a bull case and technicals were showing it rose enough where marginal upside was difficult.
For my losers such as $IREN $INTC and $CIFR I bought at the wrong times.
My cost basis for $IREN and $INTC was too high and already reflected a bull case for valuation. I did not wait to enter at an attractive valuation. I fomod in was too bullish on these 2 stocks and bought when everyone else was buying and sold when everyone else was selling
$CIFR I entered at what i thought was an attractive valuation in October but
a) factor flows & degrossing flows overwhelmed fundamentals and
b) I was most likely just outright wrong in my model & fundamental analysis
Why $CIFR is the one PSP I bought during this selloff
When the whole high beta AI equity trade is selling off what you really want to look for is first the forced selling flow being exhausted
Then equities that fundamentally have low risk to further downside
Credit/tenant quality is the most important thing to getting your PSP valued at a lower cap rate
I modeled the PSPs with the highest credit tenants $CIFR $APLD $HUT
And $CIFR was the best
Additionally, credit markets have been showing signs of stress which is one of the reasons companies like $IREN recently stated they slowed the amount of Capex they planned to spend in 2027 as they wait for credit markets stress to calm down.
$CIFR also came out on top here as all 3 contracted sites have already received funding to build out
So why is the valuation here asymmetric to the downside?
In June, DLR just bought AA- hyperscale leases at a 6.5% year 1 cap rate with 3.6% annual rent bumps. Assuming exit cap rate ~8.5% 200bps risk premium.
The transaction gets DLR an unlevered yield of 9%.
I priced Cipher's three signed leases the same way: NOI and the building's resale value, discounted at 9% (10% for the weaker Fluidstack lease)
To get PV
Black Pearl (AWS): $4.34bn
Stingray (AWS): $1.52bn
Barber Lake (Fluidstack / Google): $4.12bn
= $9.98bn
Subtract
•$4.54bn of project notes
•$2.16bn of converts
•$0.72bn of cash and bitcoin
•$0.44bn of taxes
= $3.56bn, or $6.53 a share
I bought $CIFR at $5.90
Receiving the rest of their pipeline for free.
Decided to close $HUT take small profits today.
Don’t want weekend risk of Iran War potentially heating up again.
And like $CIFR more after working on models more
Planning to take a pretty big bet on some of the PSPs down in the gutters here
Favorites so far from existing models are $HUT and $CIFR
Modeling PSPs seeing which ones have been sold off way too hard relative to
- value of their contracted MWs (analysis on tenant credit quality
- value of their pipeline (analysis on geogrpahic risks, permitting and regulatory timelines and risks, etc)
https://t.co/DNrccRcqY3