@yarvolk@Curvance I am the same.
When tracking through Monovision, cwmon was missing from my address.
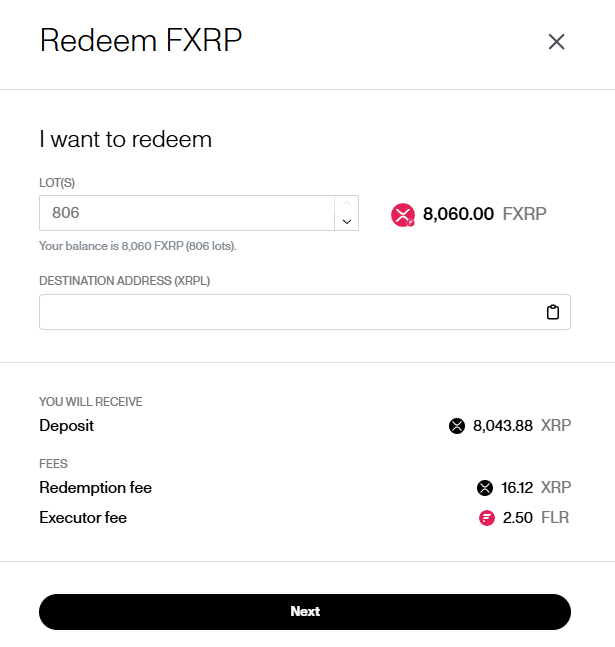
Sent to 0xF32B334042DC1EB9732454cc9bc1a06205d184f2.
@ClearstarLabs@FlareNetworks@upshift_fi The figures provided by earnXRP are excellent, but the actual interest and point payments are disappointing. Point payments stopped after the 22nd, and it appears that interest payments have not even increased by 2-3% since the beginning.
@iampaulgrewal If foreign banks pay interest on stablecoins, I think there will be no need to deposit money in U.S. banks. Ultimately, this is expected to make the U.S. cryptocurrency less competitive, and eventually the big banks in the U.S. will pay interest on stablecoins.
@bambben@FlareNetworks Upshift doesn't offer 8% interest. I recently received around 1.5%, but even that was deducted as a fee.
And even point payments stopped for over 8 days. I contacted them through Discord, but they gave me a phishing-like solution: linking my wallet to resolve the issue.
@upshift_fi@Aptos Discord inquired about this because the points have been suspended
I was nervous about suggesting that it be resolved through a certification partner at the following link (https://t.co/eojS0mQQch ), so I have removed the delegation.
@EleanorTerrett Banks need to return a greater portion of their deposit income to users.
Paying interest on stablecoins isn't essential for bank survival; it's a deception.
Banks generate far more profits by maintaining minimum reserve requirements and offering minimal interest.
@SenLummis@SecScottBessent Banks require a 7% collateralization ratio, while stablecoins require a 100% collateralization ratio.
The bank must choose between increasing the collateralization ratio or raising the interest rate.
@SenLummis@SecScottBessent I don't understand why stablecoin interest income under the CLARITY Act is a problem for banks.
Some banks pay interest on deposits, while some stablecoins earn interest simply by holding them in their wallets. Essentially, they're the same thing.
@SenLummis@SecScottBessent In conclusion, the options are as follows:
1. The bank applies the current interest rate on long-term deposits to general deposits.
2. The bank increases the collateralization ratio and adjusts the interest rate to the same 0.35%.
@SenLummis@SecScottBessent JP Morgan and Coinbase's 2024 net income will be roughly 20 times different, so why can't banks raise interest rates?
The problem lies in the way banks pay interest. Banks only pay regular interest when customers deposit long-term.