@VarshaEGaikwad Maam i would like to request you to streamline the procedure of RTE reimbursement for schools. As in such time it will help the promoters to meet the basic needs. The current system is very time consuming.
Been trying out @periskope_app this week for our clients WhatsApp groups:
Early impressions: a shared inbox across numbers, tickets straight from a message, and private team notes inside the chat. Works on a regular WhatsApp number too.
Still exploring, but so far it's Soothing !
Day 7/100 🧵
On a ₹1 cr CPWD/PWD/MES/NHAI bill, the department withholds:
2% GST TDS u/s 51 CGST = ₹2L
1-2% IT TDS u/s 194C = ₹1-2L
₹3-4 lakh sits with government before your cheque hits the bank.
Miss one GSTR-7 reconciliation and that credit dies. 👇
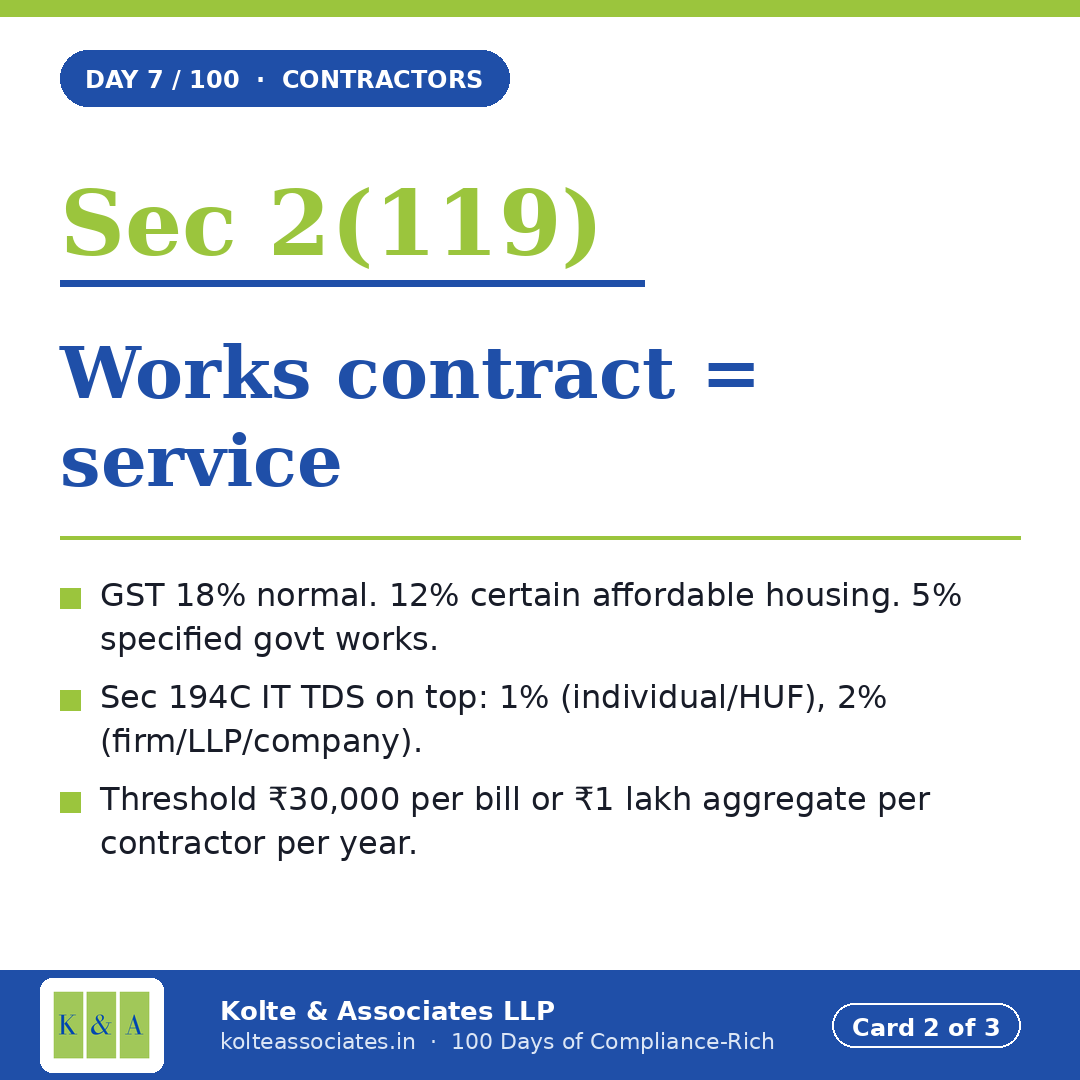
2️⃣ Works contract = service u/s 2(119) CGST.
GST 18% normal. 12% certain affordable housing. 5% specified govt works.
Sec 194C IT TDS on top: 1% (individual/HUF), 2% (firm/company). Threshold ₹30K/bill or ₹1L/year per contractor.
3️⃣ Rule 6F — the silent disqualifier.
Receipts >₹1.5L in any of last 3 years → cash book + journal + ledger + bills >₹50.
Doctors: + daily case register (Form 3C).
Miss Rule 6F → 44ADA disallowed.
https://t.co/NuJPzY964r
— @kolte_rohit
Day 6/100 🧵
Three professionals walk into a GST audit:
Lawyer → reverse charge
Doctor → exempt
CA → 18% forward charge
Same Act. Same client. Three different invoices.
Mixing them up is the #1 GST error in professional firms 👇
2️⃣ Three GST regimes:
• Advocate → business client → RCM (Notif 13/2017 Sl.2). No GST on invoice.
• Doctor in clinical establishment → exempt (Sl. 74).
• CA / CS / cost accountant → 18% forward charge with full ITC.
One regime per profession. No mixing.
Day 5/100 🧵
Healthcare in India is GST-exempt — until you charge ₹5,001/day for a non-ICU room.
Cross that line and you owe 5% GST AND lose ITC on linen, disinfectant, meals, software.
If you run a hospital or clinic, FY 2026-27 looks like this 👇
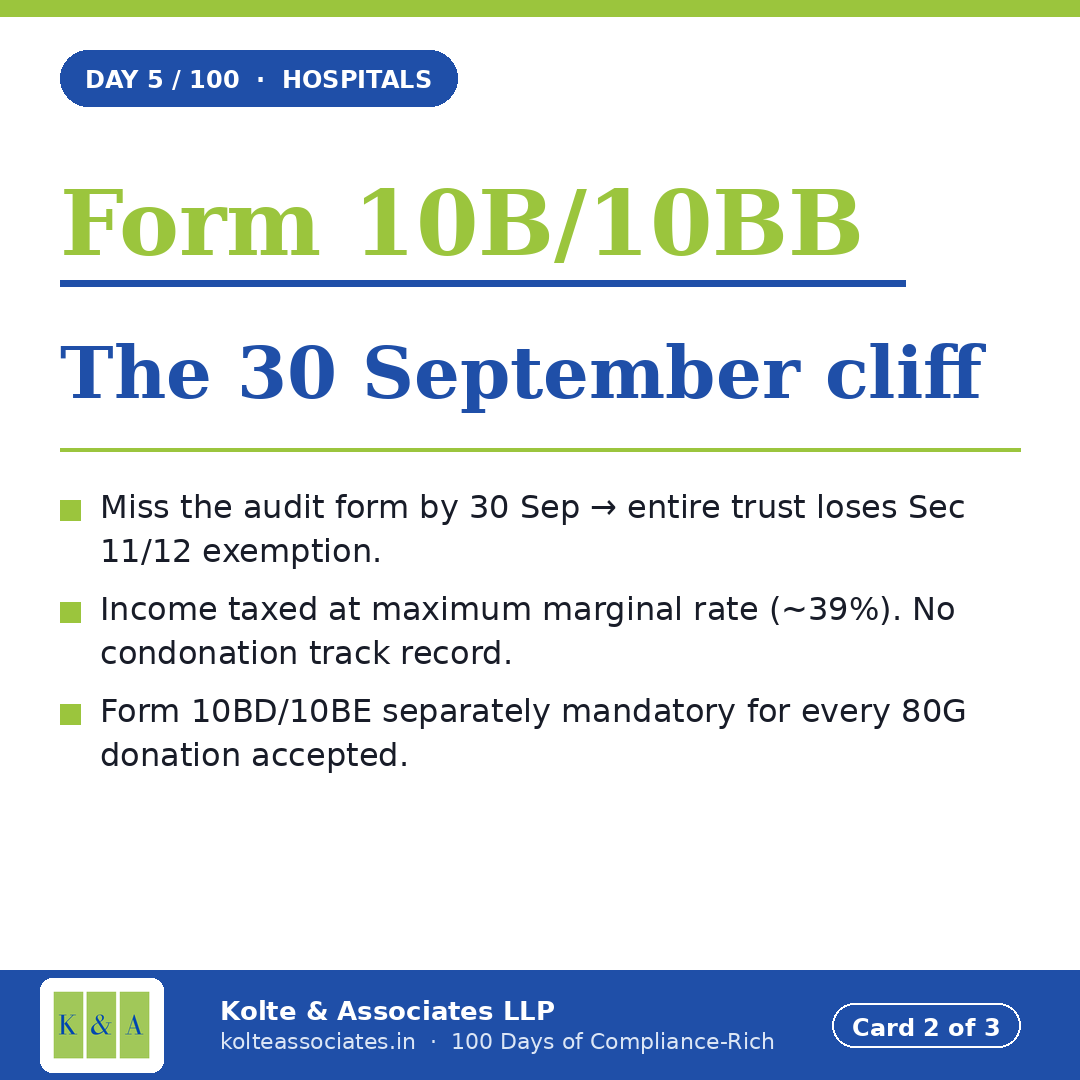
2️⃣ Charitable hospitals — the 30 Sep cliff.
Miss Form 10B/10BB by 30 Sep → entire trust loses Sec 11/12 exemption → taxed at MMR (~39%).
No condonation track record.
Form 10BD/10BE separately mandatory for every 80G donation accepted.
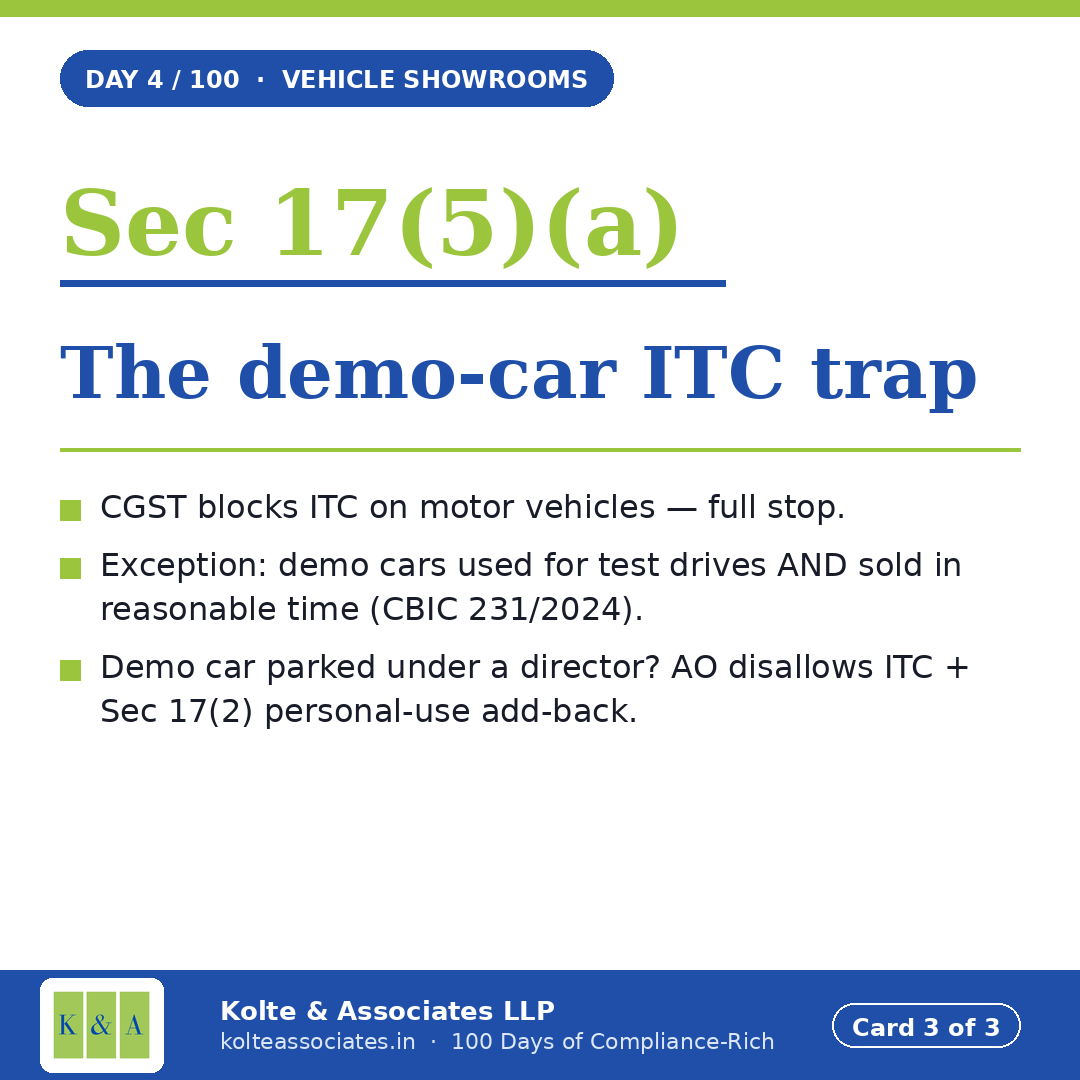
3️⃣ The demo-car ITC trap.
Sec 17(5)(a) blocks ITC on motor vehicles — except demo cars used for test drives AND sold in reasonable time (CBIC Cir 231/2024).
Demo car parked under a director? AO disallows ITC.
https://t.co/FlxtdOhuR7
— @kolte_rohit
Day 4/100 🧵
Every motor vehicle sold above ₹10 lakh in India = 1% TCS.
No exemptions.
No de-minimis.
No "government buyer" carve-out.
Sec 206C(1F) is the single most-missed compliance in vehicle showrooms. Here's what it actually means 👇
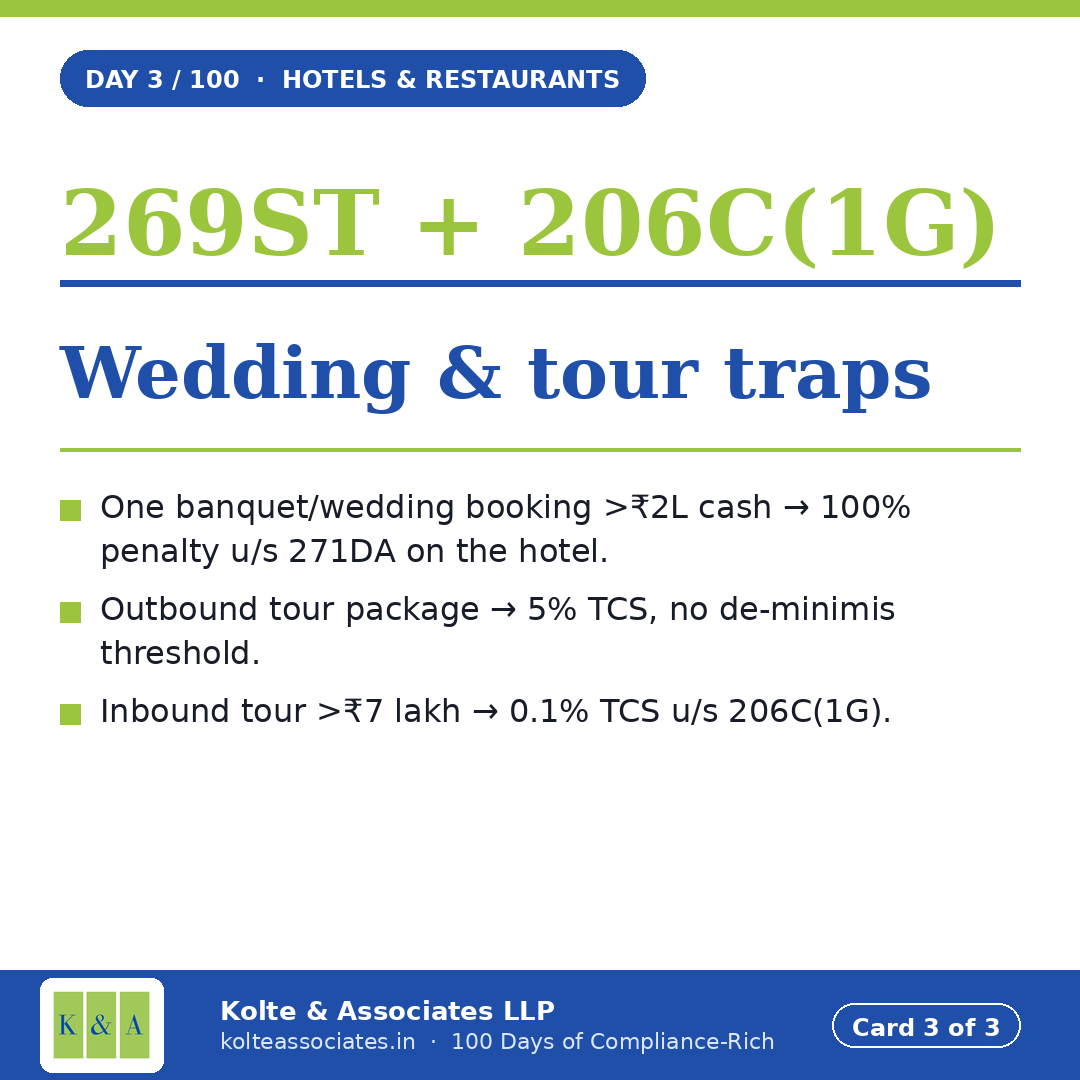
3️⃣ Sec 269ST + 206C(1G) — wedding & tour traps.
One banquet booking >₹2L cash → 100% penalty on you.
Outbound tour package? 5% TCS on every value, no de-minimis.
https://t.co/RmAMTFiWxx
— @kolte_rohit
Day 3/100 🧵
Charge ₹7,499/night → 12% GST.
Charge ₹7,500/night → 18% GST.
One rupee. Six percentage points. Plus your in-house restaurant's GST also flips on the same day.
If you run a hotel or restaurant in India, this is your morning briefing 👇
2️⃣ Sec 40A(3) — the daily cash trap.
Cash to vendor >₹10,000/day → fully disallowed.
Vegetable mandi, fish market, daily-wage staff — all of them.
A ₹15,000 cash voucher = ₹15,000 added to taxable income. Splitting across days won't save you if same vendor.