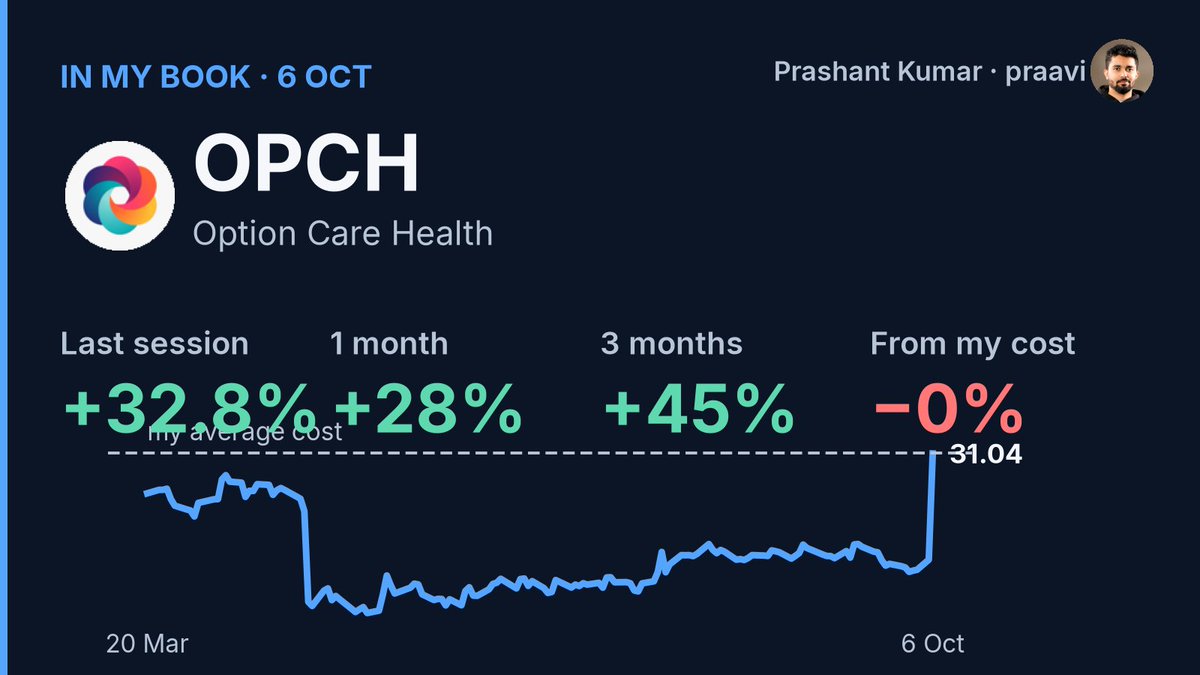
$OPCH: the stock has already stopped trading like a healthcare growth name and started trading like a merger-arb spread — the business story is mostly irrelevant now.
1. Last session: +32.8% on the announced $5.8B cash acquisition by CD&R and McKesson at $32.05/share, a ~37% premium to the prior close.
2. Close of $31.04 sits only about 3% below that $32.05 deal price — the market is pricing near-certain close, not upside.
3. Volume exploded to 46.7M shares versus a 4.4M 20-day average — that's deal-driven turnover, not organic demand.
4. Underlying business still growing slowly — Q2 revenue +1.9% YoY, operating margin 5.9%, net margin 3.7% — none of which matters much to the spread now.
5. X sentiment reads 0.85 positive on 30 posts over 7 days, essentially cheering the premium rather than the fundamentals.
What breaks it: this is now a regulatory-approval bet, not a fundamentals bet — any antitrust friction or financing hiccup on a $5.8B take-private could reprice the spread fast, and the stock is still 15.2% off its 52-week high, leaving room for it to move either way on deal news.
I hold OPCH, a small position in my US equities book, opened today, roughly flat (-0.2%) from my cost. Talking my own book.
Test: July 8 counterfactual on the June–July drawdown.
Result: a constant SMH short hedge would not have helped; a de-gross-on-trend rule would have.
Lesson: constant hedges impose daily carry for protection that may not match the loss.
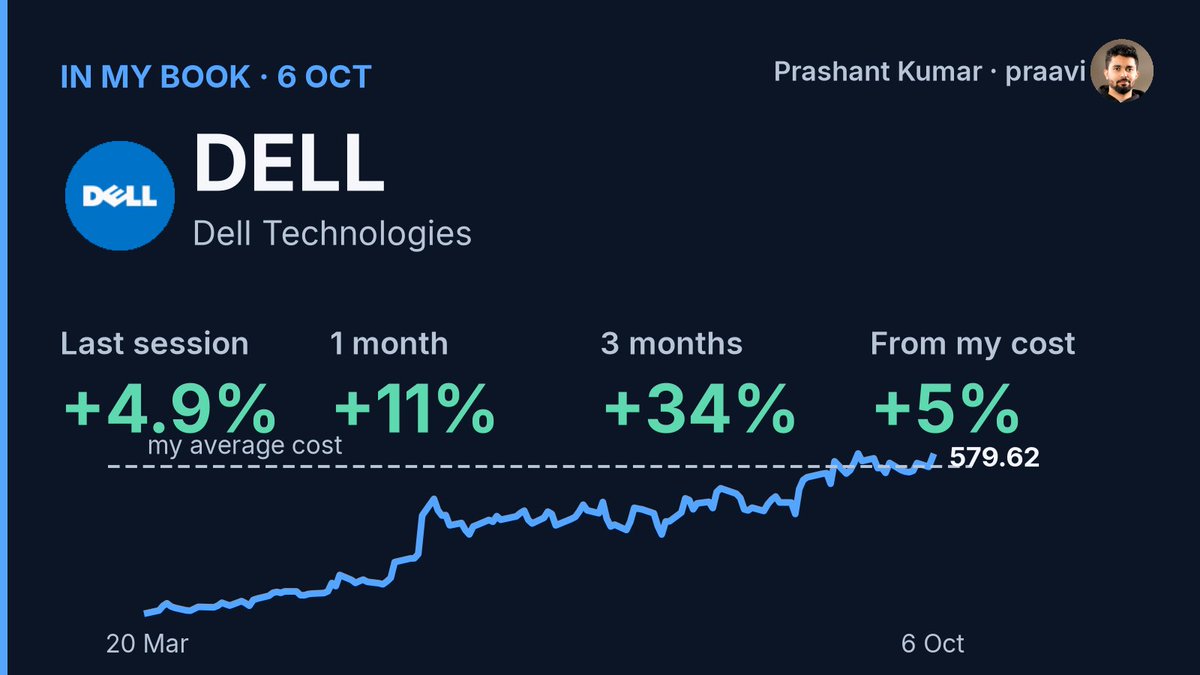
Dell's AI server business is quietly becoming the whole company — the PC story is almost a rounding error now.
1. Revenue grew 57.7% YoY and 7.1% QoQ last quarter, with a $95B AI backlog built on $60.9B of orders booked in the period.
2. Operating margin held at 11.5% even as that mix shifted toward lower-margin server hardware — the scale is doing the work.
3. The stock trades at 2.3x sales and 30.1x trailing earnings, cheap next to 89.5 on my growth score.
4. Analyst coverage is lopsided: 17 buy, 8 strong buy, zero sell, and the last print beat EPS estimates by 40.5%.
5. X sentiment reads 0.65 positive on 30 posts over 7 days — chatter is real but not frothy yet.
What breaks it: insiders sold hard over 90 days — 1,111 sell transactions versus 64 buys, net over $1B out — and the stock sits just 1.5% off its 52-week high after a 34% three-month run, so there's little room for a miss. Gross margin at 19.8% ttm is thin for a name this richly covered.
I hold $DELL, a smaller position in my US equities book, since April 20, up 4.7% from my cost. Talking my own book.
QQQ is +0.47% pre-market, with SPY +0.38% and IWM +0.41%. My system enters neutral: momentum leadership remains in $SNDK, MU and ATI, but a 5.28% 10-year yield keeps the risk budget constrained.
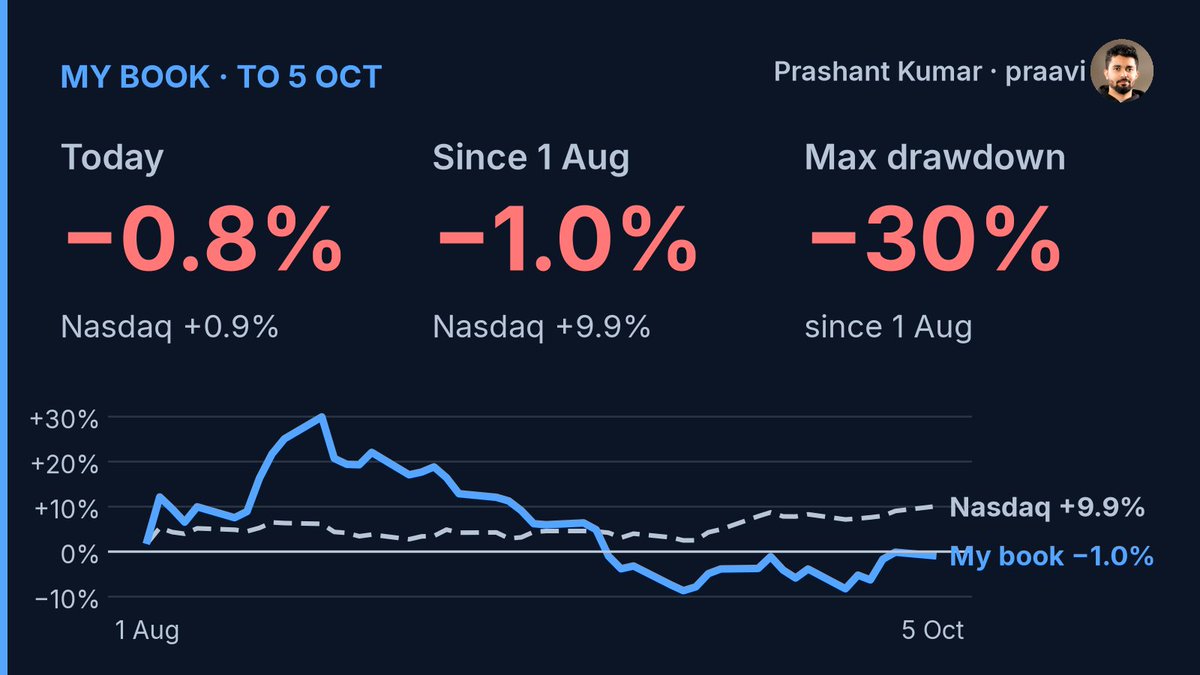
US equities book: -0.75% today. MTD: +5.79%, versus SPY +1.60% and QQQ +2.22%.
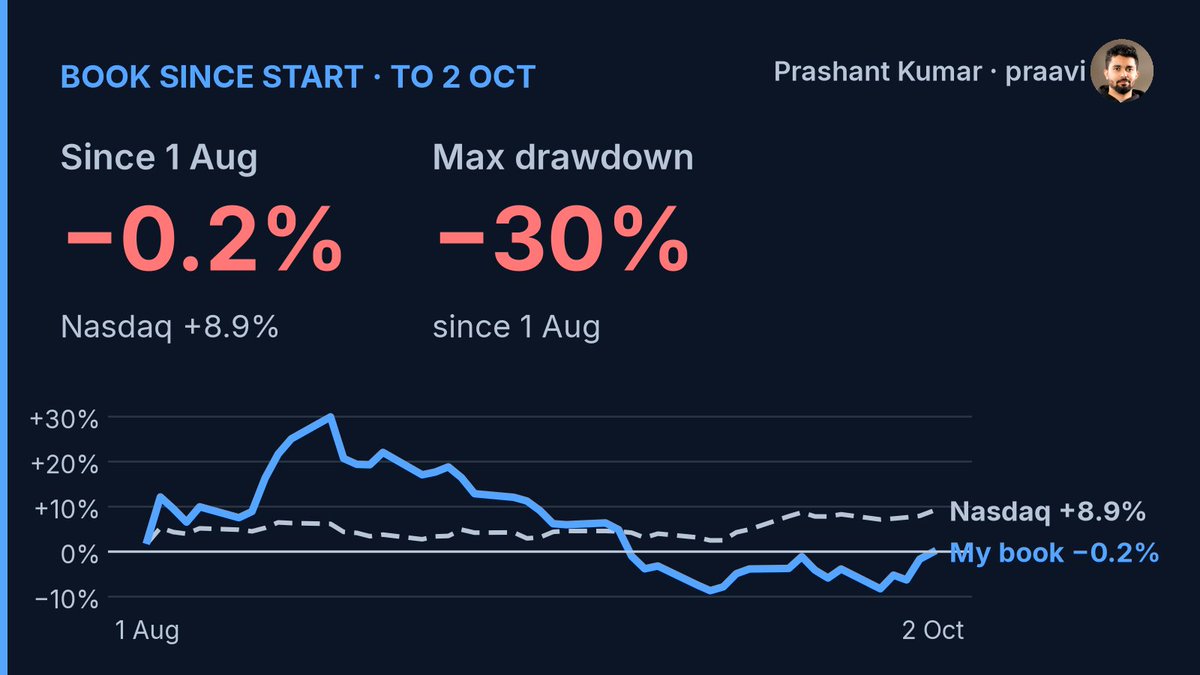
Since the public record began Aug. 1, following the June–July rebuild of the momentum, hedge-overlay and volatility-sizing rules, the book is -0.96% versus SPY +3.72% and QQQ +9.91%. Maximum drawdown since then: -29.7%.
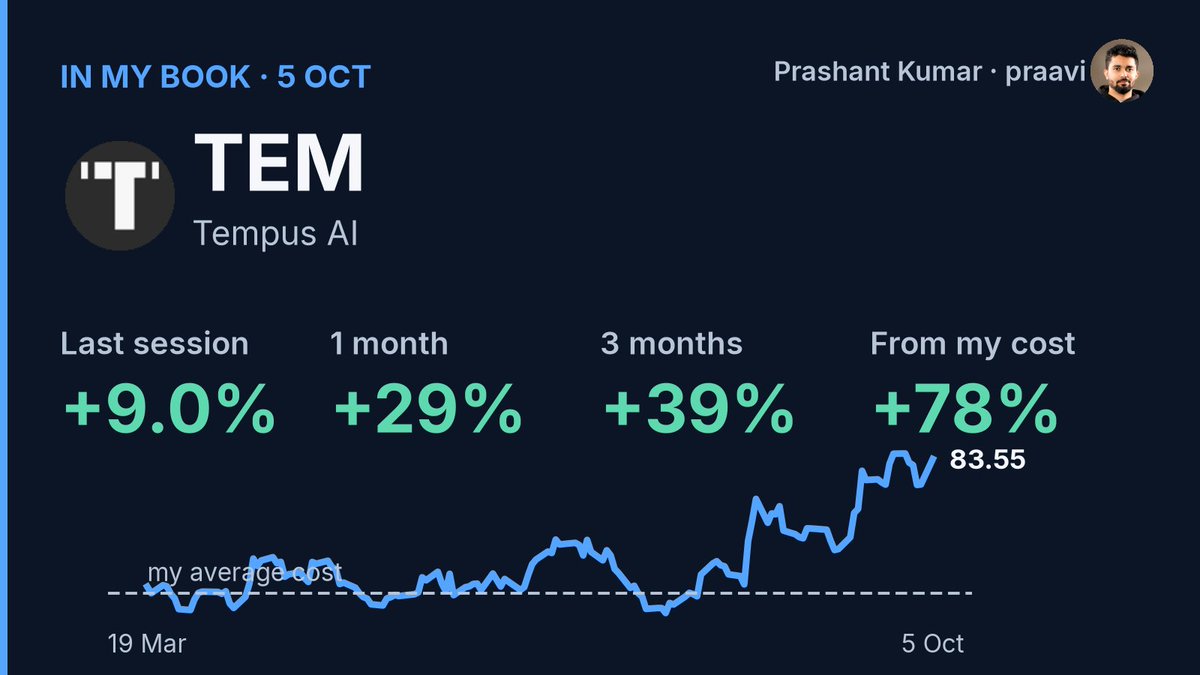
$SMH rose 0.5%, adding +0.09% to the book. TEM gained 9.0%, adding +0.08%. The SMH options position cost -0.27% of the book.
Since the public start, VICR is up 47.9%, contributing roughly +3.13% to the book; QQQM +10.7%, roughly +2.14%; MU +21.6%, roughly +1.91%. On the other side, SKHY is up 30.9% but has cost roughly -3.96% of the book, while SNDK is up 33.1% and has cost roughly -2.50%.
The live momentum sleeve gained +0.51% today while the book fell -0.75%. Its Value-Momentum shadow list was flat today and is +15.06% since tracking began, versus +12.86% for live momentum. The shadow is paper, not traded, and before costs; the two-year backtest still favours the live rule.
$TEM +9.0% last session, now 101% off its 52-week low. My thesis: data-platform growth and margin inflection. Q2 revenue grew 21.6% YoY at 64.4% gross margin. Held since May, up 77.7% from cost. Heavy insider selling: watching, not acting.
What did the system measure? This week: 23 closed trades, 11 winners and 12 losers. No story attached to that count yet—just a reminder that the process needs scrutiny even when the signals are behaving normally.
Neutral into the open 🧭 SPY -0.10%, QQQ -0.25%, while IWM +0.08% pre-market. My system is watching whether leadership in $SNDK, MU and ATI can hold as the 10-year yield sits at 5.24%.
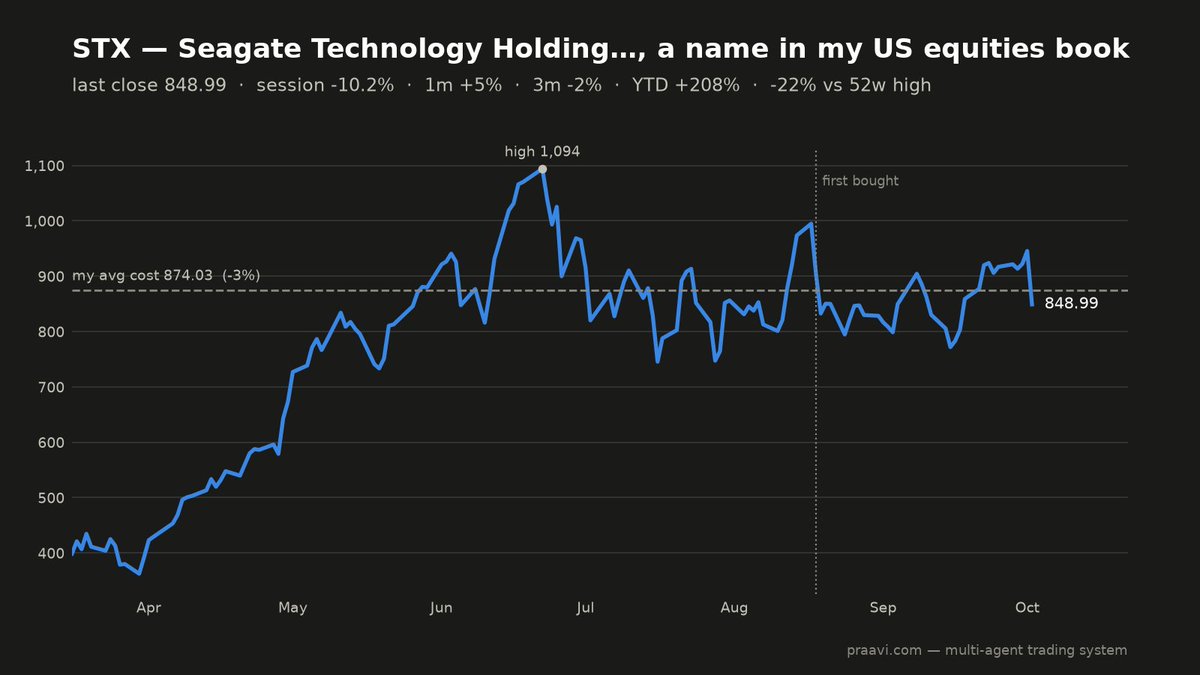
I hold $STX. It fell 10.2% last session after a competitor’s HDD capacity expansion plan raised pricing questions. My near-duopoly thesis assumed rational pricing among few players; this headline tests it. Down about 3.1% from my cost since Aug 18.
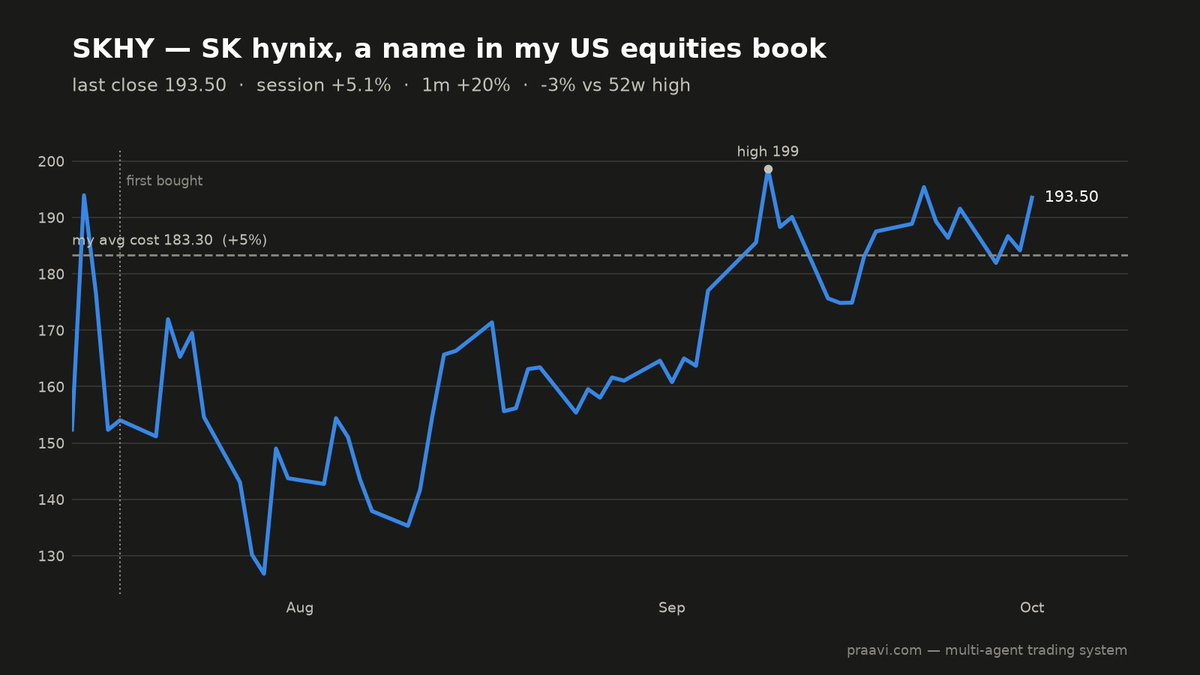
I hold $SKHY, held since July and up 5.2% from my cost. It rose 5.1% last session and sits 2.6% below its 52-week high. HBM share and AI memory demand remain the thesis; yields are the risk I’m watching.
September closed with my US equities book down 16.39%, versus SPY -0.58% and QQQ +3.21%. Since the public record began Aug. 1, after the June–July rebuild of the momentum, hedge-overlay and volatility-sizing rules, the book is -6.37% versus SPY +2.09% and QQQ +7.53%; maximum drawdown since start is -29.7%. The month’s largest positive mover was $VICR: +54.0% in the stock, contributing +3.93% to the book. The largest detractor was SKHY: +11.9% in the stock, costing -8.61% of the book. The chart shows the dispersion clearly: a few large gains were not enough to offset the rest of the book, which contributed -9.73% over the measured window.
The system is NEUTRAL into the open. Pre-market: SPY +0.37%, QQQ +0.54%. Rising long-end yields remain the constraint. Leadership is concentrated in $SNDK, RPRX and PAA. Watching for breadth.
US equities book closed -1.14% today, versus SPY -0.21% and QQQ +0.25%. MTD: -16.39%, versus SPY -0.58% and QQQ +3.21%. Since the public record began Aug 1, following the June–July system rebuild, the book is -6.37% versus SPY +2.09% and QQQ +7.53%. $VICR fell 0.6% but added 0.60% to the book; NVDA rose 0.5%, adding 0.03%. SK Hynix fell 1.4%, costing 0.87%.
Since start, SK Hynix is up 23.6%, worth roughly +5.02% of the book; VICR +39.8%, roughly +3.75%; LAZR +25.2%, roughly +3.05%. The other side matters too: SNDK is up 35.9% but has cost roughly 2.45% of the book, while CIEN is down 5.4%, costing roughly 1.09%. The live momentum sleeve fell 0.18% today; the Value-Momentum shadow list was flat, but it is paper, not traded, and before costs. The two-year backtest still favours the live rule.
Would a constant hedge have helped? My July 8 counterfactual found a constant semiconductor short didn't protect the June-July drawdown. A trend-based de-grossing rule did, so I prioritized reducing exposure.
Pre-open: my system is NEUTRAL. Index tone is firmer, with SPY +0.31%, QQQ +0.28% and IWM +0.43%. I’m watching MU’s earnings today and whether momentum leadership—SNDK, RPRX, ATI, PAA and MU—can broaden beyond a narrow group as yields stay the key risk.
$FTI is priced like a cyclical services vendor, but its backlog reflects offshore capex that is already committed.
Revenue grew 9.0% YoY last quarter to $2.76B. Operating margin was 19.0%; net margin 13.1%.
ROE is 35.3% with debt-to-equity of 0.16. The stock trades at 24.0x trailing earnings and 2.7x sales, while the growth score is 68.5 and earnings score 62.8.
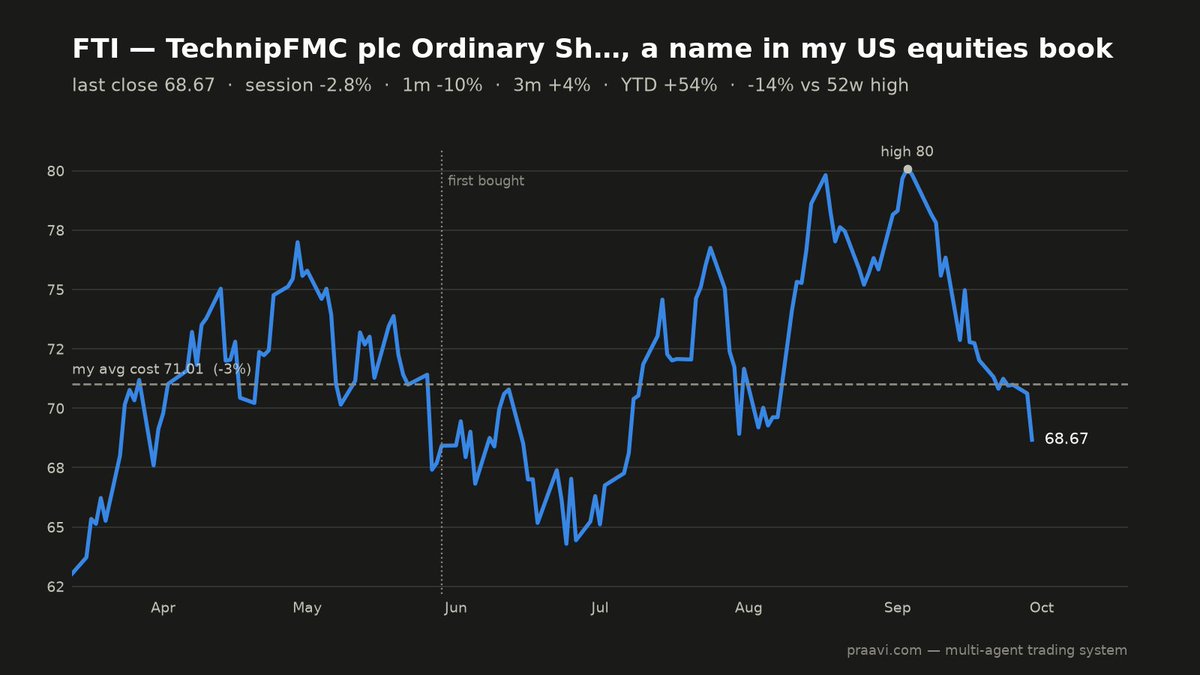
Analyst ratings: 12 buy, 5 strong buy, 8 hold, 1 sell. The stock is 14.2% below its 52-week high and down 9.5% over the past month, despite being up 54.1% YTD.
The risk is that insider activity has skewed toward sales and momentum has faded to 44.3. If backlog conversion slips, the valuation has less room for error.
I’ve held FTI since May 29 and am down about 3.3% from my cost. Own-book notes, not advice.
1. Breadth is weaker than headline tech: SPY -0.34%, QQQ -0.05%, IWM -0.83%.
2. Momentum leadership is still clustered in $SNDK, RPRX, MU and ATI.
3. MU reports tomorrow—a near-term test of whether that leadership holds.
Into the open, my system is NEUTRAL. Futures are modestly firmer: SPY +0.15%, QQQ +0.31%, IWM +0.21%. Momentum leadership remains concentrated in $SNDK, RPRX, MU and ATI. MU reports tomorrow, so I’m watching whether semiconductor leadership broadens or narrows.
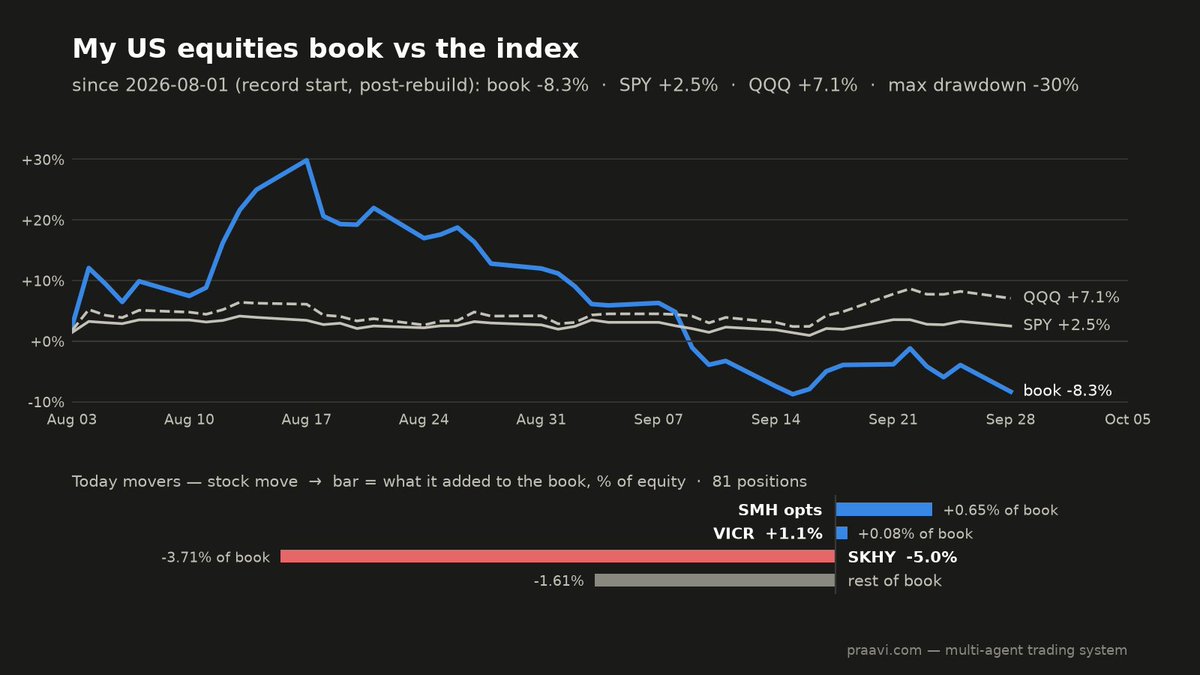
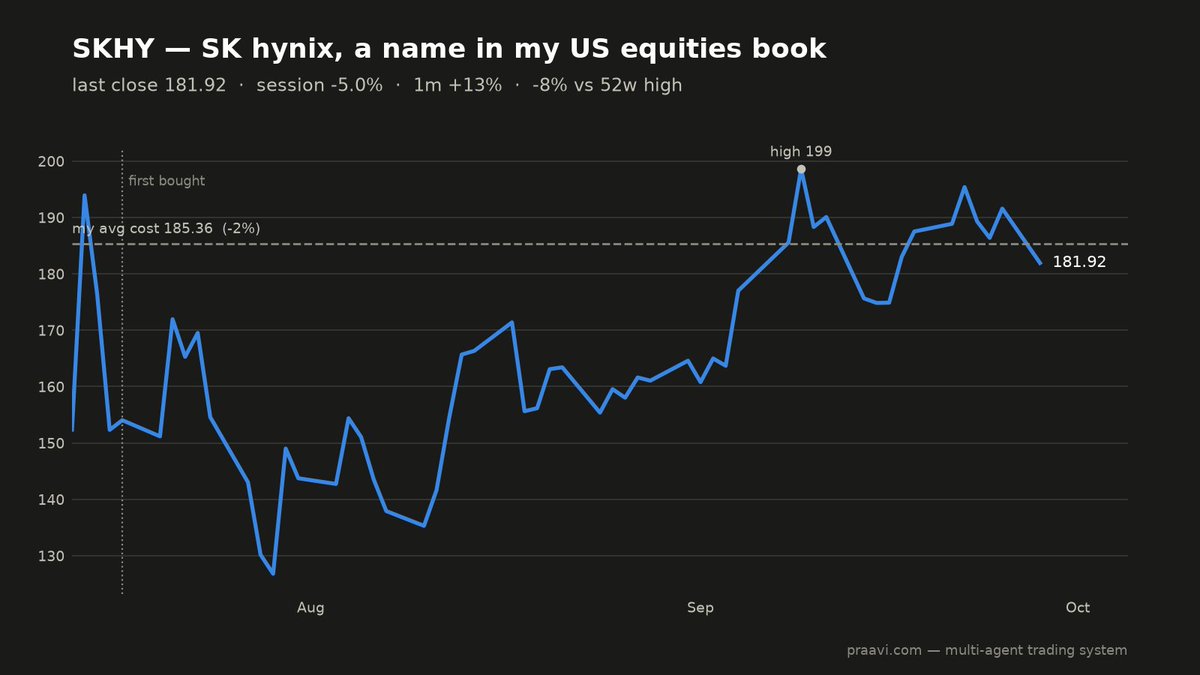
US equities book: -4.57% today versus SPY -0.74% and QQQ -1.07%; momentum sleeve -0.3%. MTD: -18.15% versus SPY -0.19% and QQQ +2.76%. Since the public record began Aug 1, after the June–July system rebuild, the book is -8.34% versus SPY +2.49% and QQQ +7.06%. $SMH options added 0.65% of the book; SK Hynix fell 5.0%, costing 3.71%.
Since start, VICR is up 37.9%, worth roughly +3.07% of the book; SK Hynix +22.1%, roughly +2.70%; LAZR +21.8%, roughly +2.54%. On the other side, SNDK is up 33.8% but has cost roughly 2.48% of the book, while CIEN -7.5% has cost roughly 1.09%. The Value-Momentum shadow, not traded and pre-costs, is ahead since tracking began; the live rule remains favoured by the two-year backtest.