Betting markets price a 94% chance the Fed holds at 3.75–4.00% on Wednesday. September PCE and the first estimate of Q3 GDP land Thursday morning, the day after the decision.
Alpine Income expects to close a $117.3M industrial portfolio this quarter, 1.9M square feet on absolute NNN leases at about $63 per square foot. The REIT raised its full-year investment guidance about 80% and bought at an 8.5% initial cash cap in Q3.
📰 The Latticework Letter — Issue #018 is live.
This week:
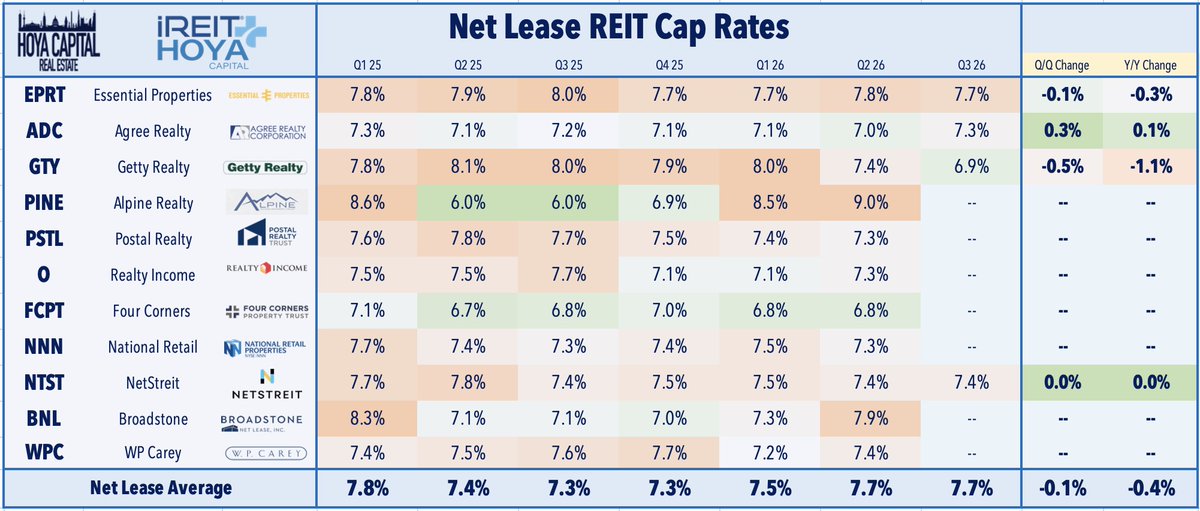
• The prints are in: four net-lease REITs reported Q3, and the executed cap rates — Agree 7.3%, NETSTREIT 7.4%, Essential 7.7%, Getty 8.0% ex-Refuel — all cleared wide of the 6.92% survey ask, while the 10-Year closed back below 5%
• Car-Mart's ninth waiver dropped the word "transaction" the day after Bloomberg reported sale talks that could run through Chapter 11; Leslie's lender-takeover plan; Meritage closes 13 more Wendy's
• The Number is 66: every Olive Garden and LongHorn lease expiring at Four Corners in 2027 renewed — full rent, 1.5% bumps, zero concessions — and Samuelson's revealed preference: underwrite what they paid, not what they said
Read it 👇
https://t.co/ZLEbav78jd
@jasonmiller15 Two-thirds of $350M is about $233M from newly built stores. At a 6.8% cap, that is roughly $15.9M of annual rent Tractor Supply takes on.
Meritage's bankruptcy sale prices 42 of its Wendy's restaurants at $18.6M, about $443,000 each. The buyer, a Dunkin' and KFC operator, plans to run all 42 as a going concern. The deal needs court approval and could close by late November.
Getty Realty closed the $261M Refuel portfolio at a 6.9% initial yield. Investments since quarter-end closed at 7.6%, and its roughly $75M committed pipeline is pricing around 8%.
📊 REIT Earnings Quick Takes
Four net lease REITs reported results over the past 24-hours, with a common theme emerging across the group: underlying portfolio performance remained solid and earnings guidance was generally stable-to-higher, while the sharp rise in interest rates is forcing a rapid reset in acquisition pricing, capital deployment, and funding strategies.
Management teams broadly described a market in which seller expectations are beginning to adjust, private-buyer competition is thinning, and well-capitalized REITs with liquidity and low leverage are gaining negotiating power, even as near-term investment volumes may slow while cap rates catch up with higher capital costs.
---
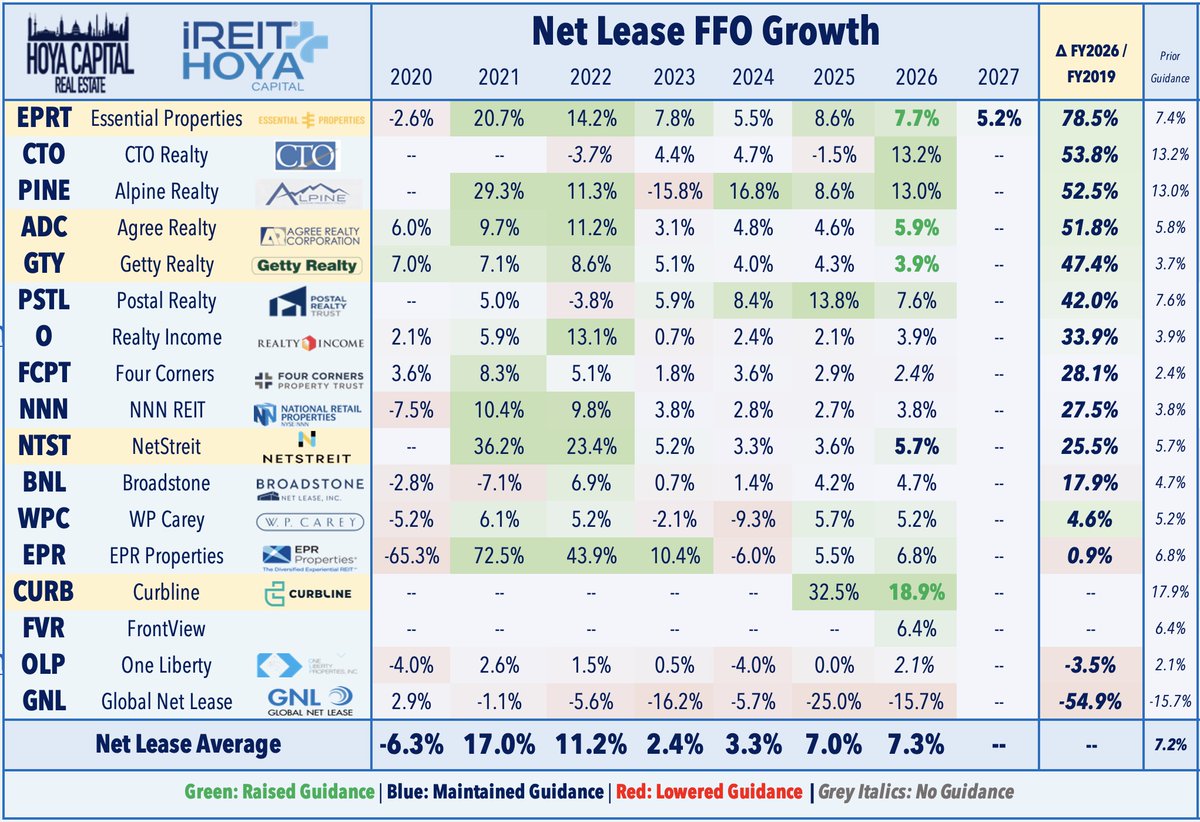
Essential Properties (EPRT) - the fifth-largest net lease REIT - rallied 3% after another solid quarter of deployment and a modest guidance increase, while management provided an initial 2027 outlook calling for continued above-average earnings growth. EPRT raised its 2026 AFFO growth outlook to 7.7% from 7.4%, while its initial 2027 guidance implies another 5.2% increase.
Q3 acquisitions accelerated to $342M at a 7.7% cap rate, but the more notable commentary centered on how quickly the recent rise in interest rates is reshaping transaction economics. EPRT noted that its forward pipeline is now pricing around an 8% cap rate, with GAAP yields approaching the high-9% range, as reduced competition from private buyers and tighter middle-market lending conditions improve EPRT's negotiating leverage.
EPRT said it has actively repriced a large portion of its pipeline over the past month, while acknowledging that closing probabilities have declined as some sellers resist the new pricing environment. EPRT expects investment volume to slow over the next several quarters as asset pricing catches up with its higher cost of capital, but emphasized that it does not need to stretch for volume or move further out on the risk curve.
That patience is supported by 3.8x pro forma leverage and $1.3B of liquidity, while management increasingly views dispositions as an attractive source of capital after selling assets around the mid-to-high-6% cap-rate range. The dynamic closely matches the theme we highlighted in our earnings preview: higher rates are creating near-term pressure on net lease valuations, but increasingly attractive acquisition spreads for REITs with dry powder.
---
Getty Realty (GTY) - which focuses on gas stations and auto-related sectors - is flat today after raising its 2026 AFFO outlook and completing its largest acquisition quarter on record. GTY now expects 3.9% AFFO growth compared with 3.7% previously, while Q3 investment volume surged to $297M, bringing year-to-date deployment above $500M following the $261M Refuel transaction.
The Refuel portfolio closed at a relatively compressed 6.9% initial yield, reflecting the quality of the assets and tenant, but management stressed that the transaction was negotiated earlier in the year and funded substantially with capital raised at more favorable pricing. More recent economics look considerably different: post-quarter investments closed at a 7.6% yield, while GTY's roughly $75M committed pipeline is now pricing around 8%.
GTY described the rise in interest rates and capital costs over the past 60-90 days as unusually rapid, but said counterparties have been surprisingly receptive to repricing because most of GTY's transactions are directly negotiated rather than broadly auctioned. GTY expects acquisition cap rates to continue moving higher if current conditions persist and indicated that it is prepared to delay or walk away from deals where spreads no longer work.
At the same time, the company is building a more programmatic disposition platform, taking advantage of strong demand from 1031 and bonus-depreciation buyers to recycle mature assets into higher-yielding opportunities. The result is a more selective acquisition environment, but potentially a healthier one for long-term spread investing.
---
NETSTREIT (NTST) - which focuses primarily on necessity and service-oriented retail properties - gained 2% after maintaining its 5.7% AFFO growth outlook while raising its full-year net investment target to at least $800M. NTST completed $273M of Q3 investments at a 7.4% cap rate, but management's commentary suggested that transaction pricing is changing rapidly following the recent rise in Treasury yields.
NTST said private buyers financed through community banks at 50%-65% leverage and borrowing costs above 7% are becoming materially less competitive, while institutional buyers also have less dry powder, creating a more favorable supply-demand backdrop for well-capitalized public REITs. Management believes cap rates need to move higher unless interest rates reverse, and it is deliberately back-loading Q4 deployment to give sellers additional time to reset expectations.
That repricing is already occurring. NTST revisited roughly 10 transactions late in Q3 and improved pricing by an average 30 basis points, with management noting that sellers have been substantially more receptive than during the 2023-2024 rate shock. Importantly, NTST does not plan to change its investment criteria or enter riskier verticals to generate higher yields.
The company can afford to wait, with leverage of just 3.7x and roughly $550M of remaining investment capacity before reaching 5x. Management currently estimates acquisition spreads at only 60-70 basis points versus its historical preference for more than 100 basis points, but sees a path to mid-single-digit AFFO growth in 2027 without issuing additional equity, providing considerable flexibility to wait for better pricing.
---
Curbline Properties (CURB) - the 2024 spin-off from SITE Centers focused on convenience shopping centers - surged 7% after raising its full-year earnings outlook and continuing its rapid acquisition-driven expansion. CURB now expects 18.9% FFO growth, up from 17.9%, after investing roughly $800M year-to-date and raising its full-year investment expectation above $1B. Same-property NOI accelerated to 3.4%, while its nearly $8M signed-not-open pipeline should provide another occupancy and earnings tailwind into 2027.
The rate discussion was somewhat different from the traditional net lease REITs, as management argued that transaction pricing within convenience centers is becoming increasingly bifurcated. Lower-quality, slower-growth assets purchased primarily by leveraged private buyers are already seeing meaningful cap-rate expansion, while higher-quality properties with strong demographics, national-credit tenants, and significant embedded rent mark-to-market have shown considerably stickier pricing.
CURB has nevertheless raised its required unlevered return thresholds as both debt and equity costs have increased, while management emphasized that it remains willing to slow deployment rather than alter its buy box. It believes the embedded growth profile of convenience centers, including strong new leasing spreads around 20%, renewal spreads in the 6%-8% range, and very low capital requirements, can justify lower initial cap rates than slower-growth real estate.
CURB enters this repricing period with nearly $900M of immediate liquidity, an entirely unencumbered portfolio, and expected year-end leverage of only about 2.1x-2.2x. Management believes that combination provides unusual flexibility to remain active as leveraged competitors become more constrained, while still targeting double-digit earnings growth into 2027.
$CURB | $EPRT | $GTY | $NTST | @AllTheREITNews | @DailyREITBeat | @ReitAcademy | @bradthomas | #REITs #Dividends #Investing
To finish building its 20,000-capacity amphitheater in McKinney, Texas, VENU sold the land under the venue and its parking garage to STORE Capital for $60M and leased it back. Opening is expected in the first quarter of next year.
@jonathanmaze A rejected lease caps the landlord's claim at the greater of one year's rent or 15% of the remaining term, up to three years. With 12 years left, that is 1.8 years of rent.
$EPRT delivering again. 🏠📈
+3.6% after hours following Q3 results:
• AFFO/share +6% YoY to $0.51
• Rental revenue $157.8M — ahead of estimates
• 2026 AFFO guidance tightened to $2.02–$2.05
• 2027 AFFO guidance introduced at $2.10–$2.18
What stands out to me: disciplined underwriting in a changing cost-of-capital environment.
That’s exactly what I want from a net lease REIT: steady growth, disciplined capital allocation, and no need to swing for the fences.
$EPRT remains one of my favorite net lease REITs.
Agree Realty's third quarter: $309M of retail net lease bought at a 7.3% average cap and a 14.5-year average lease term, 52.1% of it investment grade. Full-year acquisition guidance now sits at about $1.6B.
An all-cash buyer paid $3.5M for the land under a brand-new Palmdale McDonald's, on an absolute NNN ground lease with a corporate guaranty. The deal closed about a month after escrow opened.
@realEstateTrent A Phase I is where a dry cleaner from 40 years ago shows up. For CERCLA protection, its key parts must be updated within 180 days before closing.
The 10-year spiked to 5.33% on the hot September CPI print, then finished the week at 5.10% as stocks sold off. Market odds of a Fed hike this month fell to 17%.
All 66 Olive Garden and LongHorn leases expiring in 2027 at Four Corners were extended about five years at the same 1.5% annual bumps — no rent concessions, no landlord capital. Darden renewed every one that came due this year.