US CPI shows the stupidity of rate hikes.
The entire impact comes from refined products.
Rate hikes will not create more barrels nor increase refining, but they damage families and businesses.
Bessent Gets What the Fed’s Echo Chamber Misses
The Keynesian echo chamber is preparing its excuses. The Warsh Fed’s policy mistake will become “risk management.” Expect elaborate rationalizations and little engagement with the facts.
This is not prudence. It is misdiagnosis.
Housing is in recession. Inflation expectations remain anchored. Recent trimmed-mean PCE is 2.1%. Two-year inflation breakevens are lower than when President Trump took office. Where is the overheating?
Recall the Fed’s 50-basis-point cut before the 2024 presidential election. Trimmed-mean PCE for that September stood at 3.25%. Why did flexibility then become restraint now? “Risk management” cannot mean whatever excuses the latest decision.
Scott Bessent identifies the distinction: Democrats stimulated demand while regulation constricted supply. Trump’s tax, energy, and trade policies stimulate private-sector demand, but deregulation expands supply alongside it. Bessent says 120 regulations have been cut for every new one. Demand growth need not be inflationary when supply can respond.
Trump’s America First policies are sprouting green shoots of non-inflationary growth. Productivity is rising. Capacity is expanding. The Fed is confusing secular growth with cyclical overheating and risks choking off progress.
The technocrats pretend monetary policy is a fine-tuning instrument. It is not. It is a blunt instrument with long lags and uneven effects. They wield a sledgehammer while congratulating themselves on surgical precision.
Fixating on headline inflation compounds the misdiagnosis. Tariff-driven price adjustments are not sustained inflation. An oil supply shock weakens purchasing power and growth. Higher rates cannot manufacture oil, reverse tariffs, or expand capacity.
Worse, the hikes will not be fully felt for 24 months. The Fed adds restraint before the consequences arrive.
The technocrats and their Wall Street apologists must leave Plato’s cave. They interpret 2026 through the shadows of the 1970s.
When the damage becomes undeniable, they will claim nobody could have anticipated it.
The evidence was there. The echo chamber preferred its own reflection.
If you have $500,000 invested and drive a $35,000 car, people think you’re broke.
If you have $0 invested, $0 saved, and drive a $90,000 car, people think you’re rich.
That pretty much sums up why so many people stay broke.
La verdad es que yo no recuerdo que durante los tiempos de Massa el lobby industrial confrontara con el gobierno de la forma que lo está haciendo ahora. Y tampoco recuerdo el mismo nivel de alarma en los medios, que debería haber sido por lo menos tan grande como el actual.
¿Por qué es eso?
Se me ocurren algunas hipótesis.
1. Una es que no es lo mismo perder producción que perder rentas. Con Massa la industria sufría por la falta de dólares, las SIRA, la imposibilidad de importar insumos y una macroeconomía que se deterioraba rápidamente. Pero al mismo tiempo seguía operando detrás de un cerco de protección, con acceso al dólar oficial, crédito subsidiado y muy poca competencia importada. Era un sistema espantoso, pero para muchos industriales preservaba al menos el valor de la franquicia.
Lo de ahora es distinto. La apertura, la reducción de aranceles y un peso relativamente apreciado no sólo afectan el nivel de actividad: amenazan de manera mucho más directa los márgenes, el market share y, en algunos casos, modelos de negocios construidos durante décadas cazando en el zoológico.
2. La segunda hipótesis es más política. El régimen de Massa era enormemente discrecional, pero justamente por eso daba mucho espacio para "negociar". Una cámara empresaria podía pedir una SIRA, una excepción, un dólar diferencial, protección adicional o algún beneficio sectorial. En un sistema así, estar cerca del Gobierno tenía valor.
Este Gobierno, en cambio, les está diciendo básicamente que muchas de esas cosas van a desaparecer. Quizás parte de la diferencia entre el silencio de entonces y el ruido de ahora tenga menos que ver con cuánta industria se pierde y más con cuánto poder pierden quienes la representan.
3. Y agregaría una tercera posibilidad: en 2023 había tantas cosas incendiándose al mismo tiempo (inflación de tres dígitos, reservas netas negativas, brecha explotada, cepo, riesgo de hiper) que la caída industrial era apenas una parte de una crisis mucho más grande. Hoy, con buena parte de esos desequilibrios corregidos, cada cierre de fábrica tiene mucha más visibilidad.
Nada de esto implica que la situación industrial actual no sea dolorosa para los involucrados. Lo es. Pero mirando este gráfico resulta difícil sostener que la intensidad de las reacciones sea proporcional a lo que está pasando con la producción.
Para los desmemoriados:
Los jubilados ya marchaban todos los miércoles a la plaza reclamando aumentos durante el
primer Gobierno de Carlos M.
De hecho el Ministro Cavallo en un enfrentamiento con Norma Pla terminó llorando por la angustia de no
poder hacer más.
Luego los K expropiaron las AFJPs y tras volver a la jubilación de
Reparto, jubilaron 3 millones de personas sin aportes o con aportes incompletos, licuando a los jubilados que sí aportaron.
Es muy triste e injusto que quien trabajó toda su vida y aportó no pueda vivir de su jubilación.
Pero esto no es nuevo ni empezó con Milei. Es un problema sin solución hace décadas!
Buen domingo!
You have just 18 months to buy hyperscalers.
Then free cash flows will explode and they’ll be violently re-rated.
Time to accumulate.
$MSFT $AMZN $GOOG $ORCL
버핏이 CNBC에서 구글 얘기한 2분이 요즘 AI capex 논쟁 전체를 정리함.
"구글이랑 경쟁자들 전부 수천억 달러를 깔고 있다. 그건 진짜 돈이다. 우리 철도 개발에도 그런 돈은 안 들어갔다. 소프트웨어 시절엔 없던 게임이다."
자산 가벼울 땐 안 사더니 capex 무거워서 주주들이 싫어하는 지금 샀냐는 질문엔 — "기록을 보면 이 회사들이 월스트리트가 파는 물건의 90~95%보다 승자가 될 확률이 높다. 월스트리트 보고서 중에 기업의 실제 내부수익률을 파고드는 걸 본 적이 없다. 다음 분기 얘기만 묻는다. 우스운 일이다."
버크셔는 이 판에 310억달러를 얹었음. 어제 구글 FCF가 22년 만에 처음 마이너스가 된 바로 그 지출을, 버핏은 사야 할 이유로 읽는 중.
Ben Affleck says you're ruining your kids if you make life too easy for them as they won't be able to survive
"life has to be hard and difficult in some ways...it shouldn't be traumatic or awful or painful but things have to be hard for you to learn to do hard things"
"I don't want my kids to have that first big tough experience in life and fall apart...some of the best lessons I learned in life were from failure and not success"
"this world like it or not is going to demand that you do hard shii...if you want to have anything like provide for your own family cause if you don't do it the guy next to you will do it better"
I completely stand by my 2030 projections for $META, if anything I've become more confident despite the recent price action.
My base case of $1425 implies ~150% upside over the next four years. Even in my bear case I still make a decent return.
That's not a setup you can find very often, especially in a well known mega cap tech stock like $META.
Sometimes the best opportunities are right in front of you. In my opinion this is one of those times.
Full projections 👇
$SPCX:
$18 billion revenue, -$10 billion net income, valued at $2.2 trillion
$META:
$215 billion revenue, $70 billion net income, valued at $1.45 trillion
But yeah it all makes sense..
🚨LA ESPECTACULAR HERENCIA QUE DEJARÁ MILEI🚨
➡️Para 2030, solo energia y mineria exportaran lo mismo que una cosecha anual de soja de 50 MM tn a USD 400 la tonelada. Esto es un valor de u$s 20.000 M
➡️A ello hay que sumarle la liqiudacion del agro, endeudamiento privado, RIGI, los dolares del colchon, exportaciones industriales.
➡️Ademas, será con una economia saneada en terminos fiscales y una recomposicion total de la hoja de balance del BCRA
➡️A ello se le suma el desendeudamiento que llevó a cabo este Gobierno ya que gran parte de la deuda que vencio se pago cash
➡️Lo que dejará Milei a su proxima gestion es oro en polvo economico y politico
CHART @1816_estrategia
Luego de meses de que todo el sistema de poder haya atacado al Gobierno de una manera inédita hoy tenemos: $447 palos de US$ comprados en un día, tasas bajando, inflación bajando, EMAE y economía creciendo, inflación bajando, tipo de cambio estable, reservas en niveles record, superávit fiscal, superávit comercial, empleo privado creciendo, pobreza bajando...alguién más esta viendo lo mismo que veo yo? Me parece que se dió vuelta la tortilla.
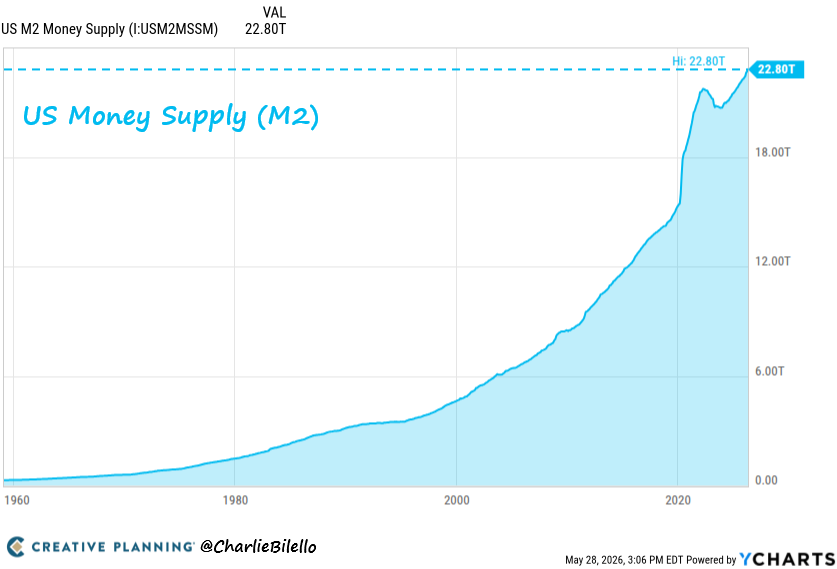
The Fed expanded the money supply by nearly $9 trillion under Powell.
Inflation has averaged >4% per year over the past 6 years.
Powell's explanation? It was nearly all due to rolling “supply shocks" over which the Fed has no control.
The truth: this inflation was made in Washington as it always is - from too much government borrowing/spending and too much government creation of money.
The 17% gain in the S&P 500 over the last 8 weeks is the 20th biggest 8-week gain for the index since 1950.
What has happened in the past following the biggest short-term rallies?
Above-average forward returns (+27% average over the subsequent year vs. +11% in other periods).
JEFF BEZOS WAS ASKED ABOUT THE CLAIM THAT "YOU CAN'T EARN A BILLION DOLLARS"
His entire response was a burger joint:
"Let's say you start a burger joint with 10 employees. People love your burgers, so you open a second outlet. Then a third. By the time you've opened 1,000 outlets, you are a billionaire."
"This is a real life story. It happens all the time. In-N-Out Burger. Raising Cane's. At what point did that money all of a sudden become unethical? It didn't."
His point:
"If you create a service that people love and millions of people choose it, you're going to end up with $1 billion."
Do you agree?
La IA no es una web con visitas y promesas.
Es productividad, publicidad, chips, nube, automatización y ahorro real para empresas.
Puede haber correcciones, sí.
Pero comparar esto con las puntocom es no mirar los balances.
Alphabet, Meta, Taiwan Semiconductor Manufacturing Company o NVIDIA no cotizan solo por “hype”:
- generan decenas de miles de millones,
- tienen márgenes enormes,
- recompran acciones,
- dominan infraestructura crítica de IA.