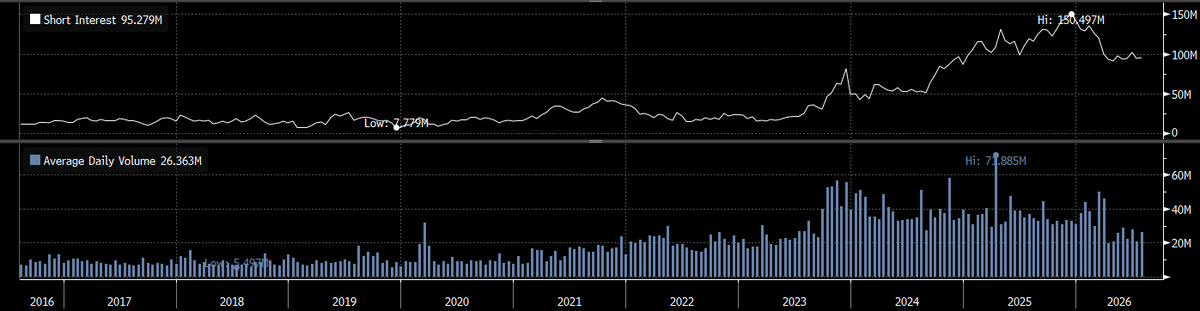
@DeItaone That's *BS*. They're postponing because their growth has slowed and there may not be enough interest to pay anything remotely close to $1.5T, much less the $2T valuation they wanted.
@RaithRoguestar@infolibnews You guys… come on… I thought you were smarter than spreading miss-information. An easy and quick check debunks those as lies or totally out of context.
@A_May_MD Good point. But I looked at it, and seems the keytruda before and after surgery only became the SoC only in 2024-25 (SWOG S1801 published results in Mar 2023) while the trial started in Jul/2023. That said, it's true, even great Ph3 data won't prove beats the current SoC.
$MRNA up +14% Today on this. Reality is it creates more competition since funding for mRNA tech has disappeared. Meanwhile the co valuation already price their V940 vaccine succeeding for ALL INDICATIONS, and they only own 50% of it. The most out of fundamental it's ever been.
Let's all take a moment to understand how self-serving it is for OpenAI, Anthropic and other execs of big hyperscalers to talk of slowing things down.
1. LLMs are not AI and won't be AGI. There is nothing AI to slow down.
2. Competition is coming up fast, slowing benefits incumbents.
3. IPOs need hype & puffery; "we are so awesome it could become dangerous" is hype & puffery
4. Cover for real uncontrollable slowing growth as IPOs look to be pushed out
Of course, being conservative is always good but the biz itself can be lumpy Q/Q. Last Q was bad bc the GLP facility construction delayed some new services. That can happen. The point I’m making is the quarterly guidance is useless for this company. Matters only that they grow 15-20% per year, while they progress on a huge pipeline of shots on goal that if any hit, could represent an >2x their total revs.
@shmilylt@mike98572986 No one cares about their guidance! If that's what you are focusing on, you're missing the thesis ENTIRELY!
Sales can be lumpy Q/Q, ultimately their base biz just need to grow 15-20%, for the market to care, and the rest is about FDA approval!
💾 Smaller KV cache. Bigger savings.
Compared with the previous generation, V4.1-Flash’s KV cache needs just:
🔹 1/4 the HBM
🔹 1/8 the SSD storage
Cache-hit charges often account for a large share of agent costs. Compressing the cache cuts those costs significantly.
3/6
$clpt
Couple factual statements, clearpoint is still in a decent cash position, they have Oberland if needed to pull cash. Anyone that truly feels they have dilution risk here right now is wrong imo. Might want to go look at the structure of the Oberland deal.
Again, not happy with lowering guidance but if I am Joe and I got amt 130, rgx 121 in early 27 and ngn 401 (speculation) in early 28 I am likely putting all resources to get ready for that. I agree with @StockDaddy6597 , bad forecasting on Joe’s part here but the amt 130 situation has changed in a positive way from 3-6 months ago. That doesn’t excuse being off on guidance this many times, that is a bad look.
If Joe announced the ngn 401 situation I think this would make a lot more sense in that context. Again, contractually they can’t talk about that program at this point so this plan seems a little more off putting but if I know that for a fact I am definitely putting all heads towards launches.
$CAT blow out quarter, but helped by ~400m tariff refunds and dealer inventory build up. So the print was less impressive. And Power & Energy segment (main bull thesis) barely beat Street numbers (sales 8.2bn vs 8.1bn consensus). At 33x peak earnings, this print is NOT enough!🚩