@DavidBeckworth It’s wonderful when you pick chapters and topics well. Combine it with Mehrling and BoE (2014) essays to reinforce money creation and balance sheet mechanics. Include Ihrig to depart from multiplier and introduce ample reserves. And some BIS papers to land on EM constraints.
Please join us tomorrow 10am EST to discuss Monetary Dynamics in Dollarized Economies: The Case of Ecuador. Webinar hosted by the International and Monetary Economics Network. Registration attached. https://t.co/1NZArj3WLj
#Opinión | @LorenzMaldo sostiene que 2026 ofrece una combinación poco común de factores económicos a favor del Ecuador, pero advierte que esos “vientos de cola” no duran para siempre.
Lee más aquí: https://t.co/i752IaMjil
#ForbesEcuador
En nuestro Summit Banca & Finanzas 💼📊, @LorenzMaldo , fundador y economista en jefe en Aequus Economics, será parte de este encuentro para hablar sobre los retos y oportunidades que marcarán el futuro del sector financiero en Ecuador 🇪🇨.
🗓️ 08 de octubre de 2025
⏰ 16:30
📍 Quorum, Paseo San Francisco, Cumbayá
Inscríbete ya en el link: https://t.co/fc9zmT6ZUI
Entrevista en Hora 25 con @AndresCarrionTA sobre la situación macro del país, medidas, crecimiento, y FMI. // Interview in Hora 25 about Ecuador’s macro situation, policy measures, and IMF program. #Ecuador#IMF#EmergingMarkets#latam
https://t.co/1YLPuZeULt
Comparto este trabajo escrito con Samuel Pienknagura, para quienes tienen interés en el tema. Central Bank Independence and Inflation in Latin America—Through the Lens of History - JÁCOME - Journal of Money, Credit and Banking - Wiley Online Library https://t.co/gsTi0Mjwcc
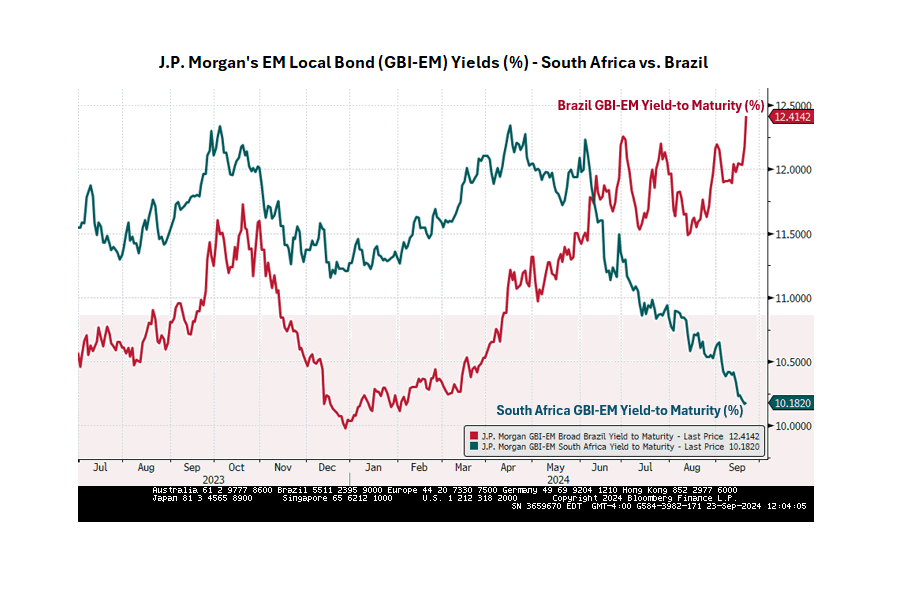
Emerging markets cannot ignore global drivers, but domestic fundamentals matter a lot (including the diverging fiscal stories) - the chart shows local yields (GBI-EM Index) in South Africa and Brazil:
Out now - @vaneck_us's Eric Fine & @NGurushina on:
- the U.S. dollar's new competition
- why U.S. dollar assets will have to "work harder" to be appeal to emerging market (EM) central banks
- the yen’s impact on EMs & global interest rates
- why central bankers cannot be independent when government debt is too high (EMs used to be on the bad side of it, but now it is developed markets (DM) such as Japan and perhaps others)
- much, much more!
This interview is a Fireside Chat and paid sponsorship on behalf of the VanEck Associates Corporation.
Enjoy 🔥
Sovereign debtors, creditors, and IMF staffers: Are you getting tired of overly complicated value recovery mechanisms?
Lee Buchheit and I propose a simpler—and more beneficial—alternative to use next time.
Just up on SSRN.
@HarvardBizGov@CIGIonline
https://t.co/x0AYBin1QC
The rise in the unemployment rate in July to 4.3% brought the Sahm rule to 0.53 — just above its trigger. Even so, there is good reason to view the current rise in the unemployment rate as overstating the recessionary dynamics, at least somewhat.
#CongresoComExAustro Ahora, damos paso a Juan Lorenzo Maldonado (@LorenzMaldo), quien cuenta con más de 10 años de experiencia en análisis e investigación macroeconómica aplicada y asesoría en políticas públicas.
Nos dará su perspectiva económica sobre la temática "Escenarios: Mapas factores políticos y económicos en Comercio Exterior".
@IvanWerning Hipótesis: Si mi FX siempre se está depreciando, lógico esperar que si se dolariza en el futuro mi tasa será más débil que hoy. Incentivos para adelantarme a la medida y comprar dólares hoy -> presionas más al FX hoy, Complicando otros objetivos de política económica?
@R2Rsquared@R2Rsquared do you mean QE-3 as explained in your previous post? CB balance sheet provides liquidity to backstop runs, while interest rate continues fighting inflation via traditional channels? Tx.
** What does SVB's failure imply for the Fed hiking cycle?
Bank failures and bailout of large depositors has important implications for financial regulation, moral hazard, and general fairness. Good discussions here and in media.
What about for inflation and monetary policy?
🧵
In a recently published paper, @luigiiov and @d_sergeyev investigate the effects of central bank balance sheet policies without rational expectations.
@Unibocconi@cepr_org
https://t.co/AplfgHet2N
@faustortizd En 2011 no teníamos mejor RI, si no un balance del BCE más sano. La descobertura actual no es por una RI muy baja, es por un pasivo muy alto. La diferencia no es trivial. El problema se originó al crear depósitos para gob a cambio de deuda interna. Repago: contracción monetaria