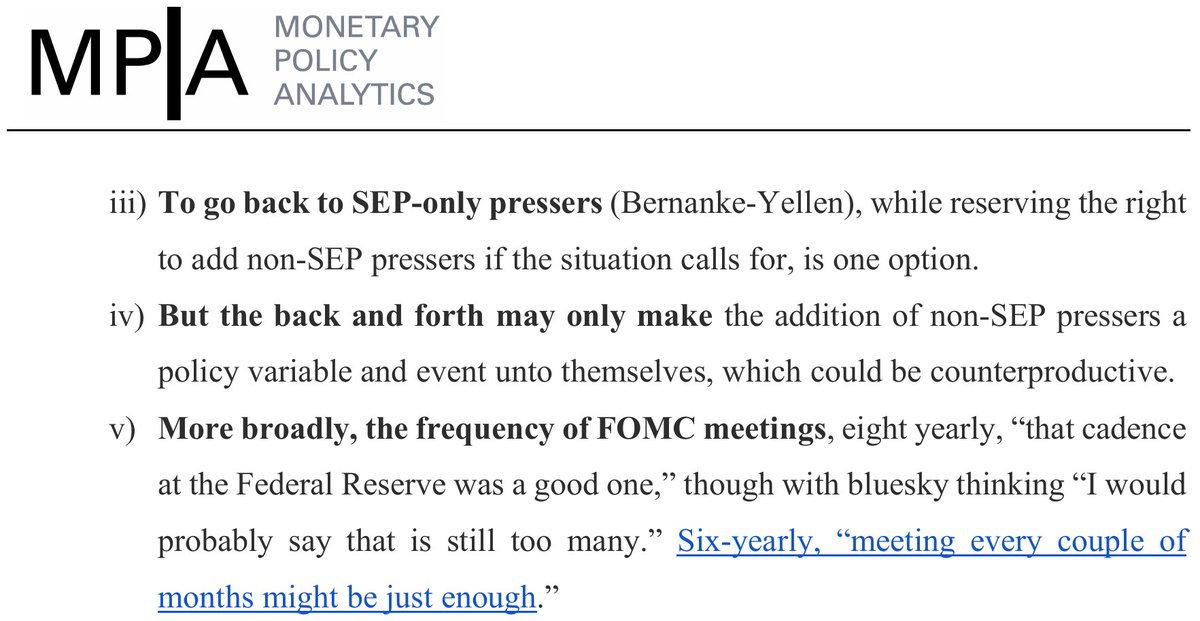
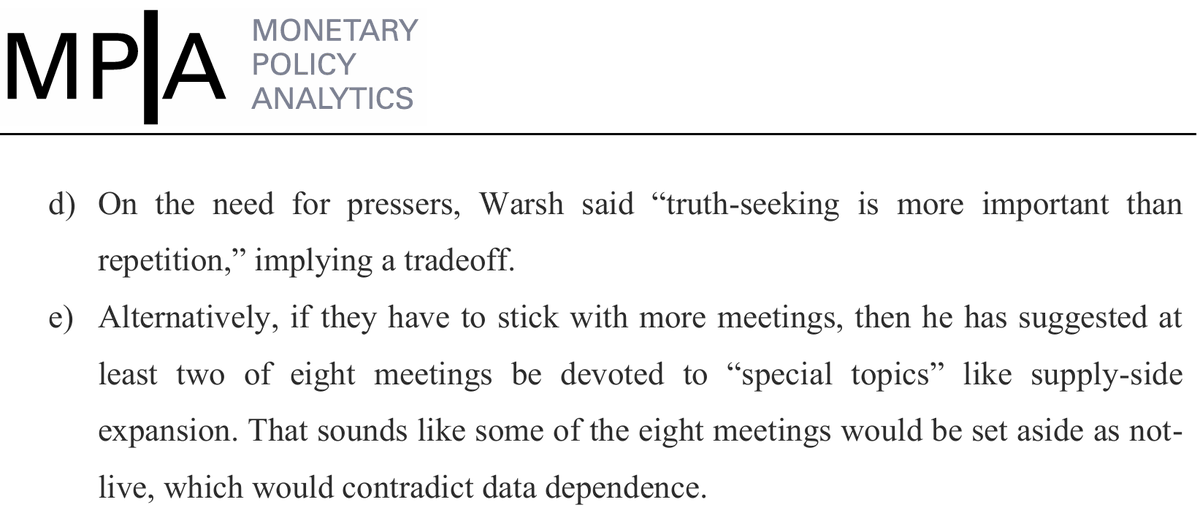
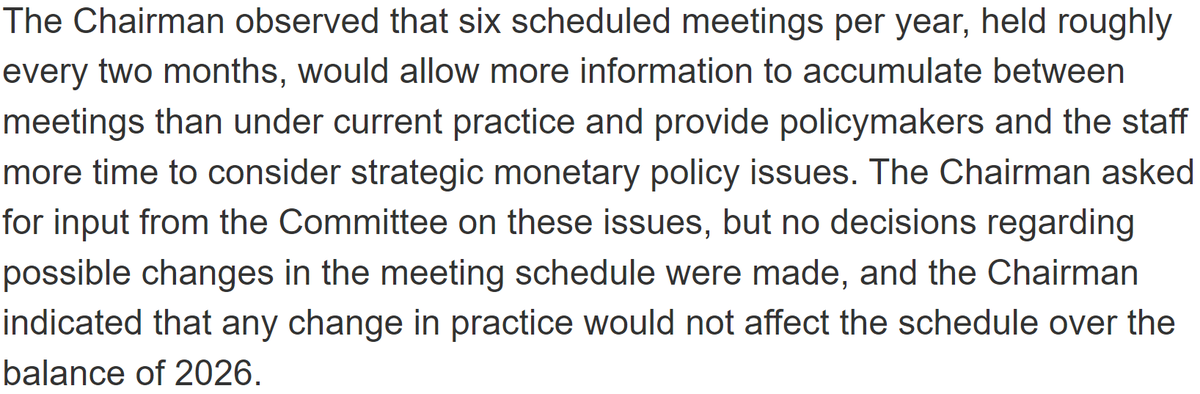
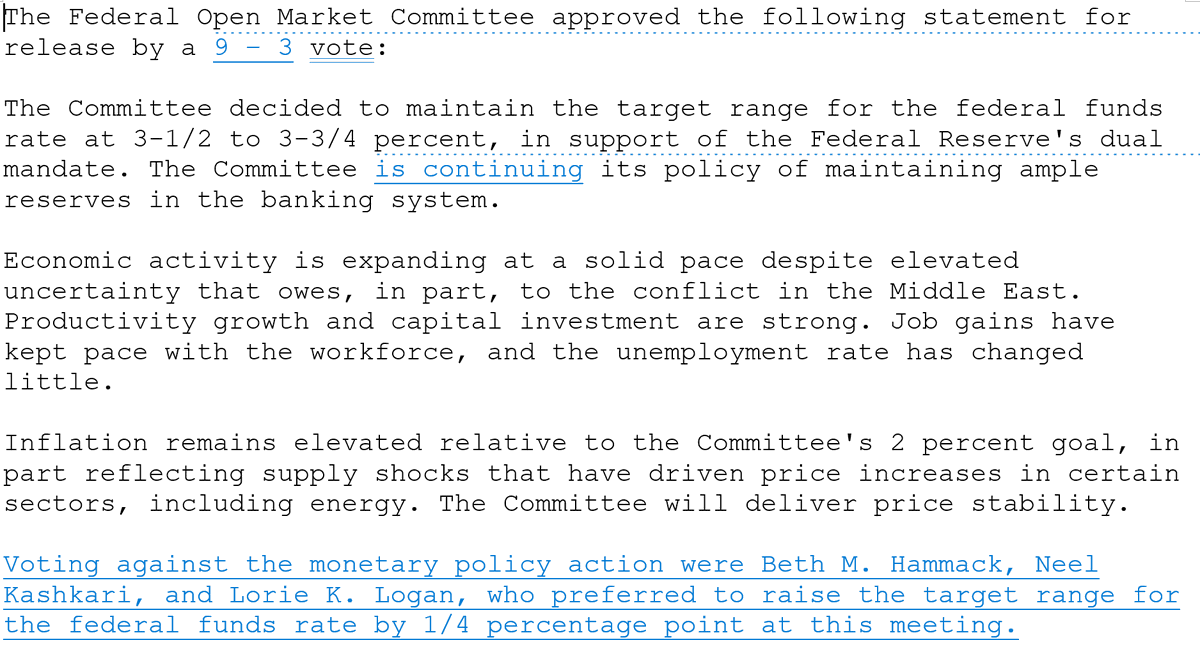
On Warsh's plans to taper FOMC meeting frequency from 8 to 7+1 (2027) to 6+2 (2028):
We had flagged to clients Warsh's preference for meeting six-yearly, and barring that setting aside a couple of meetings for longer-term issues:
Sec Bessent had backed off market-mispricing talking point: "I don't think that I can change the equilibrium interest rate, but what I can do is slow things down." He added today: "But nothing’s ever in equilibrium..."
https://t.co/XHW7u4PIOa
https://t.co/gAd5UuHpYR
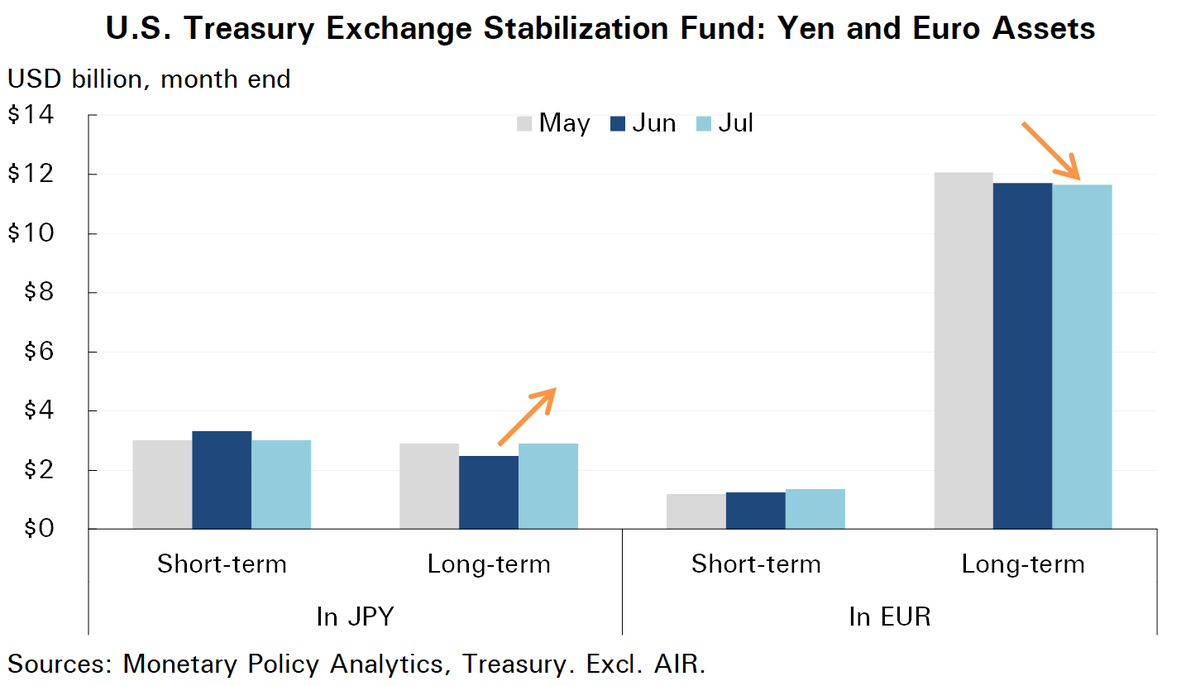
When the US jointly intervened in yen with Japan late July, it sold euro/bought yen.
Our analysis suggests the net changes in the US portfolio were modest compared to Bessent's "Buy Japanese Yen (JPY) $5-10 bil."
Governor Waller speaks in Q&A next Thursday morning, just before pre-September FOMC blackout begins, with @hpschneider at @LSEGplc
Whether he dissents to hike (if the FOMC holds) is the key issue at hand, said the event organizer.
We warned clients in early June that Warsh was seeking to lower FOMC meeting frequency to six yearly, but we didn't know when he'd take steps toward it. Now we have confirmation:
https://t.co/WBVKPUvWDE
An update:
There was no FIMA repo takeup for the week ending Wed.
The current $60bn per-nation cap was reached only once before (SNB).
Another repo pool, thought to be heavily Japan, did fall, coincident with FX interventions over the period.
https://t.co/jcTNmIjeoK
A little-used Federal Reserve backstop built for the 2020 pandemic dollar shortage is being put to a use it was never designed for: bankrolling Japan’s defense of the yen.
Treasury Secretary Scott Bessent, who has lamented Fed mission creep, wants the backstop made bigger.
..., this generated mostly by the energy shock and the history of supply-side shocks would tell you that they will work their way through the system.
What we are seeing is this core inflation remains quite under control."
Bessent, Tuesday:
"I have great confidence in Fed Chair Warsh that he will effectively balance the dual mandate of employment and inflation.
I do believe that we are seeing, in terms of headline inflation, temporary headline inflation...
On price stability
Warsh answered "PCE infl...that's our number we're sticking with it...
Who knows, come after next January, what we might say about strategy, I suspect the task forces might have something to add!"
Such comments on infl objective are interesting!
@AnnaEconomist Might the crediblity issue come from the quality of explanations he gave in the press conference, rather than the decision to hold?
“If the suggestion is somehow we're going to be fine-tuning aggregate demand so it catches supply, that's not my mental model.” Then what is?