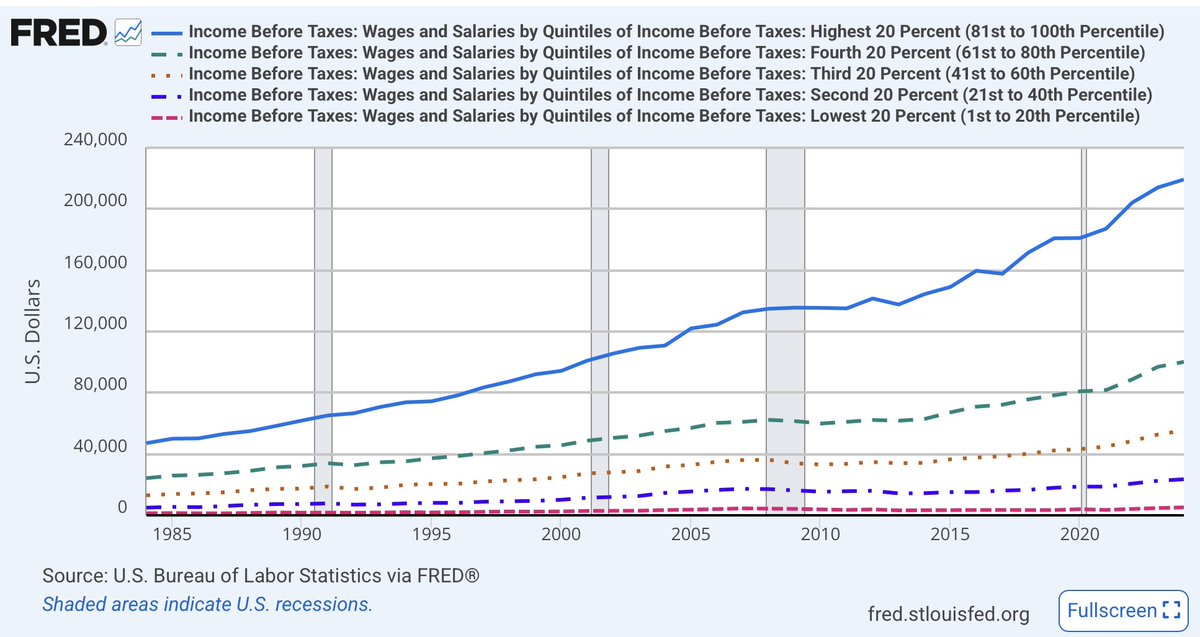
Solved: Drivers of the dollar cycle, by @ThematicMarkets https://t.co/1UVdb2Z3QB
Wait no longer! @ThematicMarkets has officially launched with an unmissable piece of research on the #USD with myriad #markets implications. Don't wait, subscribe right now!
New episode out now 🎙️
This week, @jam_croissant and I are joined by @marvinjbarth of @ThematicMarkets for a lively and insightful debate on how the US navigates its debt burden going forward.
🎬 Watch the full video now:
https://t.co/kj43SQIn9S
My old friend @JamesKanag - best political data scientist in the business - makes a very compelling case for left-right populist converge on economics in The Times…and even kindly cites my research at @ThematicMarkets:
https://t.co/ZVqhMPVuLF
My original article on Epstein effects on US inflation expectations (really!) here:
https://t.co/HzIFoBcFoD
The greatest irony is that in 16 years living in London the most common response when people learn I grew up in California is “Why would you leave the sunshine?!” Yet it is the unair-conditioned summers that are causing the rethink. (Note: summers in my childhood were 110F/45C+.)
This is not the type of economic convergence that development economists had in mind.
London remains my home & favorite city in the world, but things like this really make me rethink my decision to emigrate from a developed country…
I’m taking some time off this month, which is a great opportunity to prove the enduring value of the hematic Markets’ archive( https://t.co/mciknTyYG5). Because my research is both farsighted and long lived it applies to burning market questions long after it is written. Every other day this month I’ll apply the archive to a current issue. Today’s focus is the increasing importance of blockchain finance to geopolitics, payments and the financial system, and its implications for crypto currency value.
While it is becoming better understood, it remains outside consensus to view blockchain finance and stablecoins as a geopolitical issue rather than niche financial speculation. Western abuse of their domination of global payment systems (or ��rails”) has help pushed Western adversaries to pursue independent payment systems that rival the Wests. Aside from removing control of payment rails as an economic weapon to deploy against adversaries, the development of rival payment systems could irrevocably tie third-party states that adopt them to the West’s adversaries. A “second-best” solution was needed and stablecoins, traded on independent cryptocurrency payment rails, rode to the rescue (Leitmotif 8: The geopolitics of crypto (payments), https://t.co/E874J9Y2z4, 23 January 2025). Countries on independent payment rails would not be captive to anyone, yet still consolidate global trade on the US dollar (What debasement (Debasement Part II),https://t.co/Rscui7cIOm, 8 March 2026).
Originally a bipartisan issue, crypto finance and stablecoins have become strongly associated with the Trump Administration, which actively pushed the GENIUS Act to regulate and give US official imprimatur to stablecoins and the forthcoming Clarity Act to regulate crypto finance ((Monetary revolution in the making*, https://t.co/Q1ZMKPsNqu, 23 June 2025). This has led to a rapid expansion of international use of US dollar stablecoins (Easy money*, https://t.co/rS5qLGWXn6,* 29 July 2025) that Treasury Secretary Scott Bessent has claimed will help finance the US government and lower interest rates, though my research suggests otherwise (Revolutionary money & banking, https://t.co/j9bE6N95Qk, 27 June 2025). Integration into the core of the US payments system — the Federal Reserve and money markets — likely is next (Warsh cycle, Part II, https://t.co/fwgEaUY6IL, 27 July 2026).
It also has given fundamental value to the cryptocurrencies on whose payment rails these new “dollars” are flowing by making them geopolitically valuable to governments that might otherwise crush their use (Valuing Bitcoin (Debasement Part III), https://t.co/j3ELVDHw3D, 29 May 2026), despite pervasive myths that cryptocurrencies have long-run value without government support (21 Million and other myths of value*, https://t.co/n34trefJ3p,* 17 June 2026).
*Free articles.
@DomoDomo994@bilalhafeez123 You aren’t the 1st to request & I’ve asked @LukeGromen to join me on the Thematic Edge Podcast, but he has declined. To be fair to him that was because of unkind remarks I made about his views.
Maybe you can convince him to join me on neutral ground.
Nice to see anecdotal support from @tepingchen at @WSJ for my rigorous analysis last year showing that payrolls significantly understate high-paying “solopreneur” jobs.
@ThematicMarkets readers see key market & economic trends months or years before others.
WSJ article: https://t.co/y3kzw2oSad
Thematic Markets research from Sep’25: https://t.co/7cp2m3WVBH
I’m taking some time off this month, which is a great opportunity to prove the enduring value of the Thematic Markets’ archive( https://t.co/mciknTyYG5). Because my research is both farsighted and long lived it applies to burning market questions long after it is written. Every other day this month I’ll apply the archive to a current issue. Today’s focus is US debt sustainability amid rising Fed rates.
One of the most frequent questions I get about my expectation for higher Fed policy rates is: “How can they raise rates amid high US debt?” The question reminds me of the late economist Rudi Dornbusch’s quip that “The crisis takes a much longer time coming than you think, and then it happens much faster than you would have thought.” There is no question that the current US fiscal path — both the level of debt and rate of borrowing (deficit) — is unsustainable. But that would be true even if real interest rates were zero given the gaping fiscal deficit. The mathematics of debt sustainability are relatively intuitive yet widely misunderstood. As I explain in Debt reality versus perceptions (https://t.co/RaN6ysYUfU, 12 January 2023), even levels of debt as high as the US are sustainable if tax revenues, which grow with GDP, grow faster than interest due and, importantly, it doesn’t borrow more to cover non-interest expenditures. Real US GDP growth does exceed real US interest rates but unfortunately, the primary fiscal deficit (non-interest borrowing) is faster still (2.6% of GDP). That���s the unsustainable part.
Yet, in keeping with the first part of Mr. Dornbusch’s observation, markets don’t seem very worried. While term premia have begun to edge higher, they remain contained relative to history (Veni, vidi, vocavi, Part I, https://t.co/2QS6BtTHht, 6 September 2023) and the dollar remains near multi-decade highs amid robust demand (What debasement (Debasement Part II), https://t.co/Rscui7cIOm, 8 March 2026). To Mr. Dornbusch’s second observation, that can change quickly, especially if it is only a narrative like “US exceptionalism” holding up demand for US assets. Yet, the foundations of US exceptionalism aren’t a narrative, but are instead due to attributes no other economy can match (Exceptional, elastic, or just erratic?, https://t.co/AtgwRWGE8t, 13 April 2025) and sustained innovation-led growth (Missing productivity,*https://t.co/iD7H8KOK6W, 3 June 2026) that is attracting unrivalled investment inflows (The US outlook takes shape, https://t.co/ZNVV2oJdgo, 21 August 2025). Furthermore, as bad as US debt dynamics look, they compare favorably to many of the world’s alternatives (May you live in interesting times, The Devil, Leitmotif 3: Fiscal challenges, https://t.co/ZLhpYmcxWc, 5 January 2024; Leitmotif 5: Time to pay the piper, https://t.co/Lwdp3rFTEY, 20 January 2025), even before considering the large increases in defense spending that will be required in most of those countries (La Cosa Nostra Americana, https://t.co/X0bP1v7YSd, 4 March 2025).
That doesn’t mean the US can continue running large primary deficits forever without consequence. But while markets are giving the US the benefit of the doubt the best thing the Fed can do is pursue credible policy to keep term premia in check. That means addressing inflation aggressively. Raising short-term interest rates to fight inflation raise T-bill rates for a year or two; failing to address inflation raises term premia across the US Treasury curve, perhaps for a decade or more, raising the costs of funding US debt at all maturities. Hence, for now, there is no contradiction between the Fed being vigilant on inflation and US fiscal sustainability.
*Free articles.
Caveat: This was my FOMC, so take what I say with a grain of salt.
Obviously, I’m surprised by the hold, but completely mystified by Warsh joining the doves that created the mess. It really challenges my mental model of him. Something I’ll have to dig into when I return.
I’m not watching markets but my expectations, given the way markets were trading pre-FOMC & the persistent doubts many had about Warsh, are for significant bear steepening & dollar softness.
Good luck and check out the Thematic Markets archive while I’m away:
https://t.co/ViHJw9AeYy
BREAKING:
*FED VOTES 9-3 TO HOLD BENCHMARK RATE IN 3.5%-3.75% RANGE
*FED: HAMMACK, KASHKARI AND LOGAN DISSENT IN FAVOR OF RATE HIKE
https://t.co/ctCcOVDbfb
Caveat: This was my FOMC, so take what I say with a grain of salt.
Obviously, I’m surprised by the hold, but completely mystified by Warsh joining the doves that created the mess. It really challenges my mental model of him. Something I’ll have to dig into when I return.
I’m not watching markets but my expectations, given the way markets were trading pre-FOMC & the persistent doubts many had about Warsh, are for significant bear steepening & dollar softness.
Good luck and check out the Thematic Markets archive while I’m away:
https://t.co/ViHJw9AeYy
How can one possibly improve on the insights yielded by Thematic Markets’ investment Themes? Pair them with wine, or course!
Comment below on where I should hold my next ‘Wine & Themes’ dinner.
Read Thematic Markets here: https://t.co/DzKbikMuM4
What myths & value are common to ‘Cypherpunks’, Campbell’s Soup and Bitcoin? Find out in ‘Valuing Bitcoin’ & ‘21 million and other myths of value’ at Thematic Markets/Seriously, Marvin?!
📎Thematic Markets - Valuing Bitcoin: https://t.co/j3ELVDHw3D
📎Seriously Marvin – 21 Million and other myths: https://t.co/n34trefJ3p