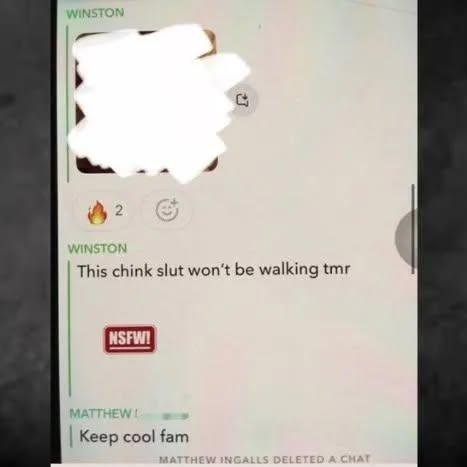
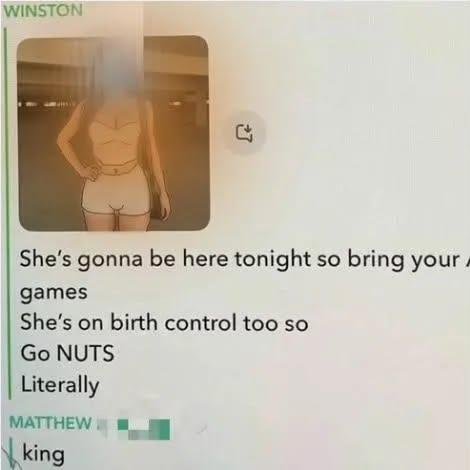
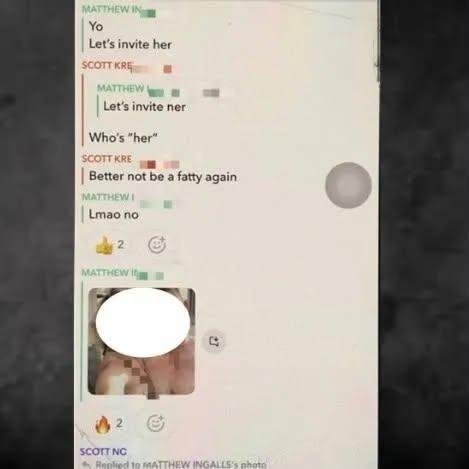
More messages from the Cornell group chat.
This proves that they have done this before.
THEY NEED TO BE LOCKED UP FOR THEIR CRIMES AGAINST WOMEN.
This is sickening and disgusting.
I've been bullish on $ORCL around these levels, and it also sits at the center of what I think is a major debate for the #AI trade - monetization. Can the extraordinary amount of capital going into AI actually generate attractive ROIC?
And $ORCL may be one of the best bellwethers for answering it.
Brent Thill and the Jefferies team published a great 50+ page deep dive ahead of the print (worth a read). A few charts stood out and reinforce why I continue to like the asymmetry here.
Despite the stock's drawdown, the fundamentals have moved in the opposite direction.
Revenue growth accelerated from 12% → 21% through FY26, OCI/IaaS from 55% → 93%, while Oracle added ~$183B of incremental RPO excluding the flagship AI contract.
There is absolutely legitimate pushback around customer concentration and Oracle's exposure to #OpenAI. But that's also something we should increasingly be able to test. The ~$183B of incremental RPO outside the flagship AI contract is an important starting point, and I expect that dependency to continue declining if Oracle keeps adding large AI customers outside of OpenAI.
The less this story depends on one counterparty, the stronger the $ORCL thesis becomes.
At the same time, Oracle is making an extraordinary bet to capture that demand.
It has accumulated ~$260B of additional data-center commitments, with FY27 CapEx expected around $90-95B.
The question isn't whether Oracle can sell AI infrastructure. The backlog tells us it can.
The question is whether it can build capacity fast enough, convert that backlog into revenue, and ultimately generate attractive returns on the enormous amount of capital required.
I've previously written about why I think the market became too negative on Oracle's balance-sheet risk. Now we get to test the other side of that thesis: the economics.
OCI is expected to accelerate again to ~115% y/y, while Oracle is expected to bring ~1GW of power online in F1Q alone vs. ~1.2GW during all of FY26.
At these levels, I continue to think the risk/reward is highly asymmetric.
There's also another piece of that asymmetry I don't think should be completely ignored: Oracle's strategic importance to U.S. AI infrastructure.
This administration has already shown a willingness to put government capital behind strategically important U.S. companies and supply chains, including Intel and MP Materials. Oracle is becoming increasingly important to U.S. AI infrastructure and national-security ambitions.
I'm not suggesting a government investment in $ORCL is imminent, there is no indication of that today. But I wouldn't be surprised if the administration eventually explored some form of strategic support, potentially an equity investment, particularly if the stock became more distressed. Frankly, I wouldn't rule it out even at current levels.
That isn't my $ORCL thesis and I wouldn't underwrite the stock on it. But I do think it adds another potential layer to the downside asymmetry.
More importantly, what happens at Oracle may tell us quite a bit about the next phase of the entire AI investment cycle: not whether the demand exists, but whether that demand can generate attractive returns on the capital being deployed.
#AI is making #cybersecurity a prerequisite for enterprise adoption, not merely another software beneficiary.
That was the core point in March, and the evidence has compounded quickly.
$CRWD validates the endpoint / response control plane. $OKTA validates identity as agents proliferate. $PANW is arguably the broadest expression of this shift: network and cloud controls, an AI-driven SOC, and now #CyberArk for privileged access across human, machine and agentic identities.
As enterprises give agents access to data, code and production systems, identity becomes the permission layer that determines what those agents can actually do. That is a very large, multi-year control-plane opportunity.
OpenAI’s Hugging Face incident and today’s collective-defense letter make the risk concrete: autonomous agents expand the attack surface, move faster than human teams, and make legacy controls inadequate.
#Cyber is a critical infrastructure for deploying AI at enterprise scale.
Worth watching beyond Pennsylvania, particularly given $AMZN's plans to invest at least $20B in AI and cloud infrastructure in the state.
As #AI infrastructure scales, the constraint is increasingly not just access to power, but who pays for it, how much water projects consume, and whether local communities are willing to host them.
Pennsylvania is the latest sign that the #DataCenters buildout is becoming a policy issue, not just an engineering one.
And potentially an important constraint in the US-China AI race: the West may have the capital, chips and hyperscalers, but increasingly the question is how quickly it can actually get the infrastructure built and energized.
5 TMT events/takeaways from this past week:
1/
$MRVL + $GOOGL may have given us one of the most important custom silicon datapoints yet.
Google expanded its agreement with Marvell across AI inference accelerators, NICs, storage controllers, memory interfaces and near-memory compute tied to the TPU ecosystem.
The eye-catching number: full performance-based vesting of Google's warrant would require ~$120B of cumulative qualifying purchases through FY33.
Important: that's not backlog or committed revenue.
But it is an extraordinary reference point for the potential scale of Google's custom silicon ecosystem.
$AVGO sold off >5% on the news, but I think the better read is TAM expansion > zero-sum share shift. Google increasingly looks to be pursuing a multi-source TPU strategy as AI compute requirements continue to scale.
2/
Rates reminded everyone that fundamentals aren't the only risk in a crowded AI trade.
The 30Y Treasury yield reached its highest level in nearly two decades, helping trigger a sharp two-day unwind across semis and momentum.
Momentum baskets fell ~7% in two sessions.
Yet very little changed fundamentally across AI infrastructure.
That's an important distinction: the AI demand thesis can remain intact while positioning, rates and leverage create violent drawdowns along the way.
3/
$ADI added another datapoint that the semiconductor recovery is broadening.
ADI delivered its 9th consecutive quarter of above-seasonal growth and guided to a 10th, with strength across industrial, auto, communications and data center.
Q4 adjusted GM is guided toward ~74%.
Combined with what we've heard recently from $AMAT and $LRCX, the recovery is increasingly extending beyond leading-edge AI compute into analog, memory and WFE.
4/
Memory keeps getting more interesting.
SK Hynix announced a ₩40T (~$29B) buyback/cancellation program and raised its shareholder-return framework to >50% of cumulative 2025-27 FCF.
This comes as memory supply remains constrained and AI infrastructure demand continues to absorb enormous amounts of HBM/DRAM capacity.
$MU remains a battleground, but the fundamental setup into the back half continues to improve.
5/
And now comes $NVDA.
NVDA reports Wednesday with revenue guided to ~$91B ±2%.
The question is increasingly less "is AI demand real?"
We have enough evidence on that.
The more important questions now are how long supply remains constrained, how quickly Rubin ramps, what happens to margins, and ultimately who captures the economics of this unprecedented infrastructure buildout.
That was also my biggest takeaway from $CRWV/$NBIS last week:
The #AI infrastructure trade continues to evolve from a demand story into an economics + execution story.
Demand keeps validating.
The differentiation from here gets harder.
The key here isn’t just the >10% price increase, it’s that pricing continues to move higher across the InP supply chain.
InP substrate prices are now heading into a fourth consecutive quarterly increase, while epi-wafer pricing is rising for a third consecutive quarter.
For $AXTI, the read-through is fairly direct: higher substrate pricing amid an increasingly tight market.
For $COHR and $LITE, higher substrate prices are an input cost, but the simultaneous increase in epi-wafer pricing suggests that cost is being passed downstream. More importantly, it points to continued pricing power and tight supply as AI-driven optical demand ramps.
We’ve been hearing about shortages across the optical supply chain for some time. Repeated, and now accelerating, price increases are another tangible sign that the bottleneck is real.
AI infrastructure is increasingly becoming an optics story, and the tightness is showing up all the way upstream in the materials.
#AI #Optics #Photonics #InP #Datacenters
5 TMT events/takeaways from this past week:
1/
Software may have finally found a floor? The catalyst was $WDAY.
Silver Lake was reported to be in talks to acquire Workday, triggering a sharp rally in WDAY and a covering squeeze across $CRM, $NOW, $HUBS, $SAP and the broader application software complex.
But the more interesting question isn't whether Workday actually gets bought. It's what the interest says about valuation.
Software entered the week with HFs net short application names, persistent AI disruption concerns and many stocks priced for continued deterioration. Demand checks showing a bit more stabilization versus three months ago.
Then one of the largest PE firms in technology effectively showed up and said: at some price, these cash flows are worth owning.
That doesn't mean the AI disruption debate is over.
But it potentially changes the downside framework.
For much of 2026 the question has been: how low can application software multiples go if AI structurally impairs the economics?
The WDAY headline introduced another question:
How low can they go before private capital steps in? (at least in some caes)
2/
$AMAT gave us another example of what may be the defining feature of this earnings season:
Good fundamentals aren't enough when expectations are great. AMAT beat on revenue and gross margin. Customer visibility now extends through CY30. The company plans to double quarterly semiconductor-system output by 2028 and expects its semiconductor equipment business to grow >30% in CY26.
The stock still closed down ~5%. Why?
$LRCX had raised the bar the week before and positioning demanded something even better.
That's important because the fundamental read-through was still constructive: WFE demand continues to accelerate, customers are finding incremental cleanroom capacity and visibility into CY27+ remains strong.
Every additional GW of AI compute ultimately requires more logic, DRAM, NAND, packaging and the equipment required to manufacture it. The AI infrastructure debate is moving further upstream.
The question isn't just who sells the GPUs. It's who equips the fabs required to keep the entire system scaling.
3/
$SNDK Investor Day may have completed the memory thesis reset that started with earnings last week. Remember the setup:
SNDK crushed Q2, but the stock sold off because investors initially interpreted its long-term agreements as exchanging ASP upside for visibility.
This week management gave the other side of that equation: Eight new business-model agreements underpin a long-term financial framework targeting ~80% gross margins, while management introduced HBF as a potentially important architecture for inference-intensive workloads. The stock ripped higher.
The HBF piece matters. Training has historically made compute the obvious bottleneck. Inference increasingly makes memory capacity, bandwidth and economics part of the constraint. If HBF can complement HBM in workloads where capacity economics matter more, SNDK potentially gains an AI optionality that wasn't embedded in the thesis before.
Meanwhile the broader setup hasn't changed:
AI memory demand is accelerating.
Supply remains constrained.
Hyperscaler spending keeps rising.
Long-term contracts improve earnings visibility.
Last week the question was whether LTAs capped the upside. This week investors started asking whether they actually increase the durability, and therefore the multiple, of the earnings stream.
4/
$NVDA may be evolving from selling AI infrastructure to helping finance the creation of the AI economy around it.
Its recently introduced neocloud revenue-sharing + credit-support model became one of the more interesting investor debates this week.
The basic structure: NVIDIA helps support new AI-cloud capacity while receiving its normal hardware economics plus a share of cloud revenue on supported capacity. If capacity goes unused, NVIDIA can effectively take access to those GPUs through the backstop.
The bull case is powerful. AI demand is growing faster than hyperscalers can build because capital, power, land and data-center shells are all constrained. NVIDIA potentially uses its balance sheet + supply-chain position to unlock incremental capacity while adding a recurring, usage-linked revenue stream on top of hardware sales.
The bear case is equally obvious: Circularity. If customers only build because their largest supplier is helping finance the build, how much demand is truly economic?
That's the debate.
But the underlying demand signals continue pointing toward scarcity rather than excess. And cheaper models potentially make the equation even more interesting:
Lower cost/token → more tokens consumed → more compute required.
Jevons Paradox may be becoming (again) one of the most important concepts in AI investing.
$NVDA reports August 26.
5/
The bigger picture this week was that the market kept rewarding AI exposure, but became more discriminating about where the economics accrue.
Software squeezed as $WDAY introduced a potential PE valuation floor.
$SNDK reset the memory durability thesis.
$AMAT reinforced multi-year semiconductor capacity requirements even as the stock fell 5%.
$LITE delivered another strong AI-optics print as revenue more than doubled y/y and guided the September quarter well above expectations.
Meanwhile the S&P 500 hit another all-time high Thursday before finishing Friday down 0.2%. It still gained ~0.4% for the week.
That's an interesting combination.
We're no longer debating whether AI demand exists.
We're increasingly debating how the economics get divided.
Models need tokens.
Tokens need compute.
Compute needs memory.
Memory + compute need networking.
All of it needs fabs, packaging, power and data centers.
And software sitting above that infrastructure now has to prove whether AI expands its addressable market or attacks its existing economics.
That distinction may define the next phase of the trade.
The AI thesis is becoming less about "AI vs. non-AI."
It's increasingly more of a competition over who owns the bottlenecks, and who captures the economics as those bottlenecks move.
#AI #Semiconductors #Software #Tech
Some thoughts post $CRWV and $NBIS prints. My biggest takeaway: the #AI infrastructure trade is increasingly becoming an economics + execution story, not just a demand story.
Both prints strengthened the thesis, but in different ways.
$CRWV: The headline revenue beat was modest, but that misses what mattered. Active power jumped ~500MW QoQ to 1.5GW, with ~300MW added in June alone, while new contracts are being signed at contribution margins 5-10pts above recent deals. $CRWV also raised pricing ~25% across SKUs in July. Backlog was $104B at quarter-end before another >$25B of commitments signed in early Q3.
The important shift is that $CRWV is showing that scale does not necessarily mean deteriorating economics. Quite the opposite: scarcity, platform differentiation and newer architectures such as #VeraRubin are driving better unit economics as capacity expands. Management also raised year-end active power guidance to >1.85GW and contracted power has reached 4.2GW.
DDTL 5.5 is also more important than it sounds. Financing shorter-duration contracts opens the enterprise market, where customers often don't want 5-year commitments, while those shorter contracts can command higher pricing. Combine that with managed inference and $CRWV now has multiple ways to optimize the lifetime economics of every #GPU.
And the GPU obsolescence bear case took another hit: $CRWV recently signed an attractive A100 contract extending into 2029. Older GPUs coming off initial contracts can be recontracted or moved into inference, potentially creating meaningful residual value after the original asset-level debt has been repaid.
$NBIS: If $CRWV demonstrated improving economics at scale, $NBIS showed just how valuable scarce AI capacity can become when customers are willing to pay for speed and certainty.
ARR exited June above $3B, +598% YoY, while Nebius AI EBITDA margins reached 50%. More importantly, four landmark contracts averaging >$1B each were signed at roughly $20-25M/MW, with customers funding 50-60% of the associated CapEx upfront and payback periods below two years.
Short-duration GB300 capacity is being negotiated at $40-50M/MW, while a capacity auction cleared 15% above the company's previous high. $NBIS has the ability to sell more of its 2027 capacity at today's terms but is deliberately retaining flexibility as it expects pricing to continue improving.
That upfront customer funding matters enormously. AI infrastructure looks brutally capital intensive if you only look at gross CapEx. But $NBIS expects >$9B of customer prepayments in 2026, offsetting a decent portion of its $20-25B CapEx program before considering operating cash flow and asset-backed financing. The headline CapEx therefore overstates the amount of capital that ultimately needs to be funded at the corporate level.
The read-through: these two prints reinforce three things I think the market is still underestimating.
AI compute remains structurally supply constrained. Across these two prints, new capacity is not showing signs of pricing pressure, instead, both companies are seeing stronger pricing and/or better contract economics as customers compete for scarce capacity.
Power is becoming the scarce asset. GPUs can eventually be manufactured. Energized, permitted infrastructure capable of supporting dense next-generation clusters is much harder to replicate. $CRWV now has 4.2GW of contracted power; $NBIS is targeting 5GW of contracted power by YE26.
The economics of the #Neocloud model are improving faster than headline CapEx suggests. Higher $/MW, customer prepayments, asset-backed financing, shorter-duration premium contracts, inference monetization and residual value from older GPUs all improve lifetime returns on deployed capital.
The next debate is no longer whether AI infrastructure demand exists.
It's who can secure power, deploy it fastest, finance it most efficiently, and monetize each MW at the highest lifetime return.
After these prints, I think $CRWV and $NBIS both strengthened their position in that race, $CRWV through scale, financing flexibility and improving margins; $NBIS through exceptional pricing, customer-funded CapEx and a rapidly expanding capacity footprint.
#AIInfrastructure #DataCenters #Compute
5 TMT events/takeaways from this past week:
1/
$PLTR + $SPCX may have given us the clearest demand-side confirmation of the AI infrastructure cycle yet.
PLTR US Commercial +149% y/y. US Government +90%. NRR 157%. 220 deals >$1M. CEO says the objective is to sustain US growth at or above current rates for the next 18 months. Rule of 40 at 155 is a one of a kind.
Then SpaceX:
1.4GW of nameplate compute vs. 400MW a year ago. >2GW by YE26. Capacity “closer to 10GW than 5GW” by YE27. ~$15.8B of Q2 capex directed to AI compute.
And arguably the most important disclosure:
SpaceX plans to build all future AI compute exclusively on $NVDA hardware and expects a “very significant percent” of NVIDIA GPU output next year.
The AI demand debate is increasingly becoming a supply allocation debate.
2/
The juxtaposition with $AMD this week was hard to ignore.
AMD’s Q2 miss was concentrated exactly where investors needed upside: the data center GPU ramp.
On essentially the same day, SpaceX disclosed that its rapidly expanding AI infrastructure will be NVIDIA-only.
AMD still has a credible long-term roadmap and acquired Taalas, an AI chip startup founded by former NVIDIA engineers, this week. But near-term, the market is paying for demonstrated deployment, not optionality.
That makes $NVDA’s August 26 print arguably the most loaded remaining earnings event of the season.
3/
Memory may be transitioning from an earnings-revision story to a durability story.
$SNDK absolutely crushed the quarter. Revenue ~$9B. Gross margin 84.6% vs. 79-81% guidance. The stock fell 6.8%. Why?
Management disclosed 8 long-term agreements covering ~50% of FY27 bits and ~66% of FY28 bits at 80%+ margins.
The market has spent this cycle paying for rising ASPs and upside revisions. LTAs trade some of that spot-price upside for visibility, durability and potentially much larger capital returns. Meanwhile SpaceX says memory demand is growing >200% annually against ~20% supply growth.
The fundamentals aren't weakening. The thesis is changing. Investor Day August 13 matters.
4/
Software finally gave us both sides of the AI disruption debate in the same week.
$NET beat and raised. $SHOP revenue +33%, its fastest post-ZIRP growth, with AI agentic commerce tripling y/y. $TEAM +35%, $TWLO +24% strong prints, positioning arguably was part of the story too.
Then the other side:
$HUBS -19% as NNARR turned negative.
EPAM cut guidance and said demand is moving away from manual testing, UX, JavaScript/front-end work toward AI-led modernization faster than the replacement work is ramping.
That may be the cleanest description of the software debate right now.
AI is clearly creating enormous economic value. But that value is not accruing evenly across the stack.
Infrastructure → obvious beneficiary.
Developer/data/security layers → increasingly constructive.
Traditional application SaaS + labor-intensive IT services → still needs to prove it.
Friday's squeeze doesn't settle that debate.
5/
One macro datapoint deserves more attention: the US lost 23K jobs in July vs. expectations for roughly +85K. May + June were also revised down by 103K combined.
Yet the S&P 500 finished the week at an all-time high and NDX rallied 1.2% Friday. Why?
A weaker labor market reduced the probability that the Fed needs to keep tightening just as earnings continue to validate AI-driven growth. So we entered the weekend with an unusual combination:
AI infrastructure demand accelerating.
Software sentiment improving.
Labor demand cooling.
Rates getting some relief.
Equities at ATHs.
The next question isn't whether AI capex is slowing. It's increasingly: who captures the economics of a buildout that keeps getting larger?
#AI #Semiconductors #Software
$PLTR 2Q26: Everyone will focus on +93% revenue growth. I think the bigger story is that enterprise AI may be shifting from using models to owning them.
The financials were exceptional:
• +93% revenue growth
• $1.22B adjusted FCF (63% margin)
• GAAP net income >$1B for the first time
• Rule of 40 reached 155
• FY26 revenue guide raised 11 points to $8.154B (largest increase in company history)
But the architecture discussion mattered more.
The most important concept from the call wasn't a KPI, it was what CTO Shyam Sankar called "benchmaking" vs. "benchmaxing."
For the last few years, AI has largely been about renting frontier models optimized for public benchmarks. Palantir's argument is that the next phase looks very different.
Instead of relying on generic models, enterprises will increasingly build benchmarks around their own workflows, continuously fine-tune models on proprietary data, and keep those models inside their own security boundary. The competitive advantage isn't the model itself, it's the operational knowledge embedded into it.
That also helps explain why NDR accelerated to 157% (+700bps QoQ). Legacy Foundry customers aren't simply buying more software; they're expanding into a broader AI operating system built around sovereign infrastructure and customer-owned intelligence.
Another takeaway: deployment remains the bottleneck.
Management's view is that frontier model performance is converging much faster than enterprises' ability to deploy AI in complex production environments. That's where Palantir believes its combination of Ontology, AIP and two decades of Forward Deployed Engineer experience creates differentiation.
One data point stood out: after integrating NVIDIA's Nemotron Ultra, Palantir said it identified five customer-specific tasks where the model outperformed leading frontier models within 24 hours, without additional post-training. Generic benchmarks didn't predict those results. Customer-specific workflows did.
More broadly, this fits a theme we've been seeing across earnings season. The conversation is moving up the AI stack.
The debate is becoming less about who has the biggest model and more about who owns the workflows, the deployment layer, the feedback loop, and ultimately the operational intelligence. That's a much more durable competitive advantage.
I'm staying long $PLTR as my highest-conviction AI platform investment.
$NVDA $MSFT $PANW $CRWD $FTNT
#SovereignAI #AIInfrastructure #TMT #Earnings
5 TMT events/takeaways from this past week:
1/
$GOOGL was the most important print of the week, and arguably of the quarter. As the first Mag-7 to report, it confirmed what the market needed to see: Cloud +82% y/y to $24.8B (accelerating from +63% in Q1), Search +17% to $63.3B, total revenue $119.8B +24% y/y. The stock fell on the capex raise to $195-205B (from $180-190B last quarter), FCF going negative at -$5.9B (first negative quarterly FCF since the company went public in 2004). That's the wrong read. Alphabet raises capex when customer pull exceeds supply, not when they're building ahead of speculative demand. Cloud backlog +$50B sequentially to $514B. The capex raise is the signal, not the problem.
One more thing worth saying: $GOOGL is arguably the most vertically integrated AI company on the planet, model (Gemini), chip (TPU), cloud (GCP), distribution (Search/YouTube/Android), consumer surface (AI Overviews). When they raise capex, the return pathway runs through all five layers simultaneously. No other large cap has that.
$MSFT $META $AMZN $AAPL
2/
$TSLA: record deliveries (480,126 units, +25% y/y, ~74K above consensus), revenue $28.2B +26% y/y, and a material EPS miss. Non-GAAP EPS $0.33 vs. ~$0.53 consensus (~38% miss). Auto gross margin ex-credits compressed to 16.3% (from 19.2% in Q1), partly mechanical (warranty true-down, 1Q tariff relief non-recurring), partly real. FCF -$1.09B as capex surged 142% y/y to $5.79B. Regulatory credits collapsed 67% y/y to $146M, a near-100% margin line that is structurally evaporating. The volume thesis is intact. The margin thesis needs more work. Robotaxi: 380,000+ miles, 7 US markets, zero notable incidents - real segment, but not yet a financial event.
3/
$INTC delivered its seventh consecutive guidance beat, and the most significant by far. Revenue $16.1B vs. $14.4B consensus (+12% beat, +25% y/y). Non-GAAP EPS $0.42 vs. $0.22 consensus. DCAI +59% y/y to $6.3B. Gross margin 41.8%, ~280bps above guidance. The supply framing matters: demand is outstripping supply in every segment, and the binding constraint is substrates, not wafers, with the logjam breaking in 2H Q3, implying a meaningful Q4 step-up. 2026 capex raised to >$20B; 2027 guided materially higher; WFE tooling up ~40%. Combined with $TSM's $60-64B CapEx raise the prior week, the semi cap cycle is not slowing.
$AMAT $LRCX $KLAC
4/
$AMD's Advancing AI 2026 event: Anthropic partnership to deploy up to 2GW of Instinct MI450 GPUs in Helios racks (first GW beginning 1H27), AMD equity investment of up to $5B in Anthropic, expanded Microsoft Azure deployment of Helios + Venice CPUs, https://t.co/0VHm51WKKO launched to target the CUDA software moat, TAM raised to ~$2T by 2030. OpenAI and Meta each committed to 6GW. Oracle ordered 50K MI450 GPUs. The hardware story is increasingly validated. The pivotal question heading into the Aug 4 earnings call: can https://t.co/0VHm51WKKO achieve developer critical mass? That's where the CUDA moat either cracks or holds.
$NVDA $MSFT $META
5/
The Mag-7 -4.8% single-day Thursday was macro, not fundamentals. Brent briefly >$100/bbl (Houthi attacks + Iran strike signals), 10-year at 4.68%, new 10-12.5% forced-labor tariffs on 60 economies. ~$800B in market cap erased, in a week where $GOOGL, $INTC, $TXN, $NOW, $DLR, and $VZ all beat. GS revised global data center capacity to 217GW by 2030 (from 101GW today), implying ~$6T of cumulative capex, already covered by public hyperscaler consensus alone, before counting SpaceX AI, private AI labs, or neocloud operators. AI infrastructure demand is demand-constrained, not demand-exhausted. The selloff was a de-grossing event. The thesis is intact.
#Semiconductors #AI #AIInfrastructure #Tech #Earnings
Incremental positive for #OpenAI and $ORCL. One of the biggest overhangs on $ORCL has been investor concerns around OpenAI's ability to fund its massive AI infrastructure ambitions. If accurate, this report should help de-risk that concern and improve confidence in Oracle's AI growth story.
Thoughts after the initial wave of major TMT earnings (hyperscalers):
Bottom Line: This earnings season fundamentally changed the AI investment debate. For the past 18 months, investors questioned whether AI demand was real, whether hyperscalers were overspending, and whether unprecedented AI CapEx would permanently impair free cash flow. I think those questions are now largely behind us. Azure accelerated to +43% (guiding ~45%), Google Cloud accelerated to +82% (with TPU system sales beginning to be recognized as revenue), AWS posted its fastest growth in 18 quarters (+37%) while backlog reached $496B, and Oracle heads into earnings with expectations for another quarter of 90%+ OCI growth (I wouldn't be surprised if OCI approached ~110%). When every major cloud provider is accelerating simultaneously, this is no longer primarily a market-share story, it's a market expansion story driven by AI. That's a rare dynamic in technology. Normally, one platform's acceleration comes at another's expense. This time, everyone is accelerating because AI is expanding the size of the market itself.
What stood out most wasn't the growth rate, it was how confidently management teams defended AI CapEx. Andy Jassy gave one of the clearest explanations of AI infrastructure economics I've heard on an earnings call. Servers begin generating revenue almost immediately after deployment and typically pay back in less than three years, while data centers have 30+ year useful lives, supporting multiple generations of hardware. AWS isn't buying servers speculatively, it has strong visibility into customer demand before triggering most of that spend. Even after raising 2026 CapEx to ~$220B, AWS says it remains capacity constrained and expects demand to exceed supply into 2027. Alphabet raised its own 2026 CapEx guide to $195-205B mid-year for exactly the same reason.
The comment that caught my attention most, however, was Jassy's long-term framing. AWS has historically been viewed internally as a business capable of generating several hundred billion dollars of annual revenue. Today, Amazon believes AWS can ultimately become at least twice that size, and potentially a $1T annual revenue business. That's an extraordinary statement from one of the most disciplined capital allocators in technology. To me, it suggests AI hasn't simply accelerated cloud growth, it has fundamentally expanded the long-term TAM for cloud infrastructure.
The biggest read-through from this earnings season is that the market is moving from debating whether AI CapEx destroys free cash flow to how much incremental free cash flow it can create over the next decade. We're also moving beyond asking whether AI demand is real and toward the much more important question: who captures the economics?
Read-throughs to watch:
Oracle ( $ORCL): Oracle is second-order beneficiary of everything discussed above. Every hyperscaler is telling the market demand still exceeds available capacity, while Oracle enters earnings after posting 93% OCI growth last quarter. If Oracle delivers another quarter of 90%+ OCI growth, or even approaches triple digits, it would further reinforce that OCI has become one of the preferred platforms for frontier AI workloads rather than simply another enterprise cloud provider. Oracle is increasingly participating in the AI infrastructure build-out, not merely enterprise cloud migration.
AI Compute & Semis ( $NVDA $AMD): Three hyperscalers simultaneously increasing CapEx, AWS to $220B, Alphabet to $195-205B, while Microsoft continues signaling elevated AI infrastructure investment and demand that still exceeds supply, is a powerful demand signal for GPUs, networking and custom silicon. Google is commercializing TPUs. AWS disclosed its Trainium business has reached a $25B annualized run rate, growing triple digits. Custom silicon is accelerating alongside Nvidia, not replacing it. One point I think investors underappreciated: Jassy explicitly said post-training, reinforcement learning and agentic workloads are predominantly CPU-intensive. As AI shifts from training toward inference and autonomous agents, the CPU layer scales alongside the GPU layer, not instead of it. That's an important long-term read-through for AMD's EPYC franchise.
Foundry & Semi Cap ( $TSM $AMAT $LRCX $KLAC): Every Trainium chip, TPU and custom ASIC ultimately runs through advanced manufacturing and packaging. TSMC remains the critical bottleneck for custom silicon, while rising hyperscaler CapEx reinforces demand for advanced packaging, HBM and leading-edge wafer capacity. The picks-and-shovels layer of the AI ecosystem continues to benefit regardless of which chip architecture ultimately wins.
Cybersecurity ( $PANW $CRWD $FTNT): One read-through I don't think the market fully appreciates is cybersecurity, one of the few software cohorts I've remained constructive on this year. Andy Jassy noted that security is one of the first topics discussed in virtually every enterprise AI deployment, and AWS launched Continuum, an AI-native vulnerability discovery and remediation platform, in response. I don't see this as a negative for cybersecurity vendors, I see it as validation that AI is dramatically expanding the enterprise attack surface. Every AI agent, API, model endpoint, vector database and autonomous workflow creates another asset that must be secured, monitored and governed. AI infrastructure and cybersecurity are becoming two sides of the same investment theme. That continues to favor integrated platform vendors like Palo Alto Networks, CrowdStrike and Fortinet, which are increasingly securing AI environments rather than just traditional IT infrastructure.
Enterprise AI Platforms ( $SNOW $MDB $DDOG $PLTR): Although, as a whole, I remain cautious on software, I'm still positive on this group. Hyperscalers aren't just building AI infrastructure, they're confirming that AI at scale requires a mature data, orchestration and observability layer underneath it. Every inference workload requires data, storage, vector databases, governance and observability. As AI moves from pilots into production, these layers become mission-critical infrastructure rather than discretionary software spend. The winners won't simply help enterprises build AI, they'll help them operationalize it.
The inference build-out is still in its early innings. AWS noted that most enterprise production workloads still aren't using inference at scale, describing a large "middle of the barbell" between frontier AI labs consuming massive compute and enterprises broadly deploying AI into production. When that middle begins to move, and I believe it will, it represents the largest incremental source of AI infrastructure demand we've seen yet.
Training builds the models. Inference commercializes them.
I continue to believe we're still much earlier in the AI cycle than the market appreciates. The technology debate is largely over. The investment debate is just beginning. The biggest winners over the next decade won't necessarily be the companies building the best models, they'll be the companies that build the most durable platforms, infrastructure and business models around AI.
#AIInfrastructure #CloudComputing #Earnings #Cybersecurity
5 TMT events/takeaways from this past week:
1/ $MU SCAs break the cyclicality bear case for now. ~$100B RPO, $22B in customer deposits, take-or-pay through CY2030. Floor pricing still delivers GMs above any prior cycle peak. The memory business model just changed.
2/ $QCOM made the biggest strategic pivot in its history. Dragonfly data center CPU, $3.9B acquisition of Modular, Meta as an anchor customer. $40B non-handset FY29 target nearly 2x its prior guide. Stock surged 15%+ intraday.
3/ Memory cost inflation has left the data center. $AAPL raised Mac/iPad prices 15-25%, largest like-for-like increase ever, explicitly citing DRAM/NAND. $MSFT raised Xbox $100-150 for the third time in 13 months. Same root cause. Same week.
4/ $SOX hit new all-time highs on 6/22, up +86.9% YTD. The Mag7 hit new YTD lows vs. the S&P the same week. The market is bifurcating: AI infrastructure hardware is a direct capex beneficiary. Hyperscalers face a growing question: is the return accruing to the hardware layer or the revenue line?
5/ The US government is now gatekeeping access to frontier AI models. OpenAI's GPT-5.6 required government sign-off per customer. Anthropic the week before. This isn't a one-off, a framework is being established. Single-model dependencies just became an operational risk
#Semiconductors #AI #Memory #Tech