$IREN: Generational Buying Opportunity?
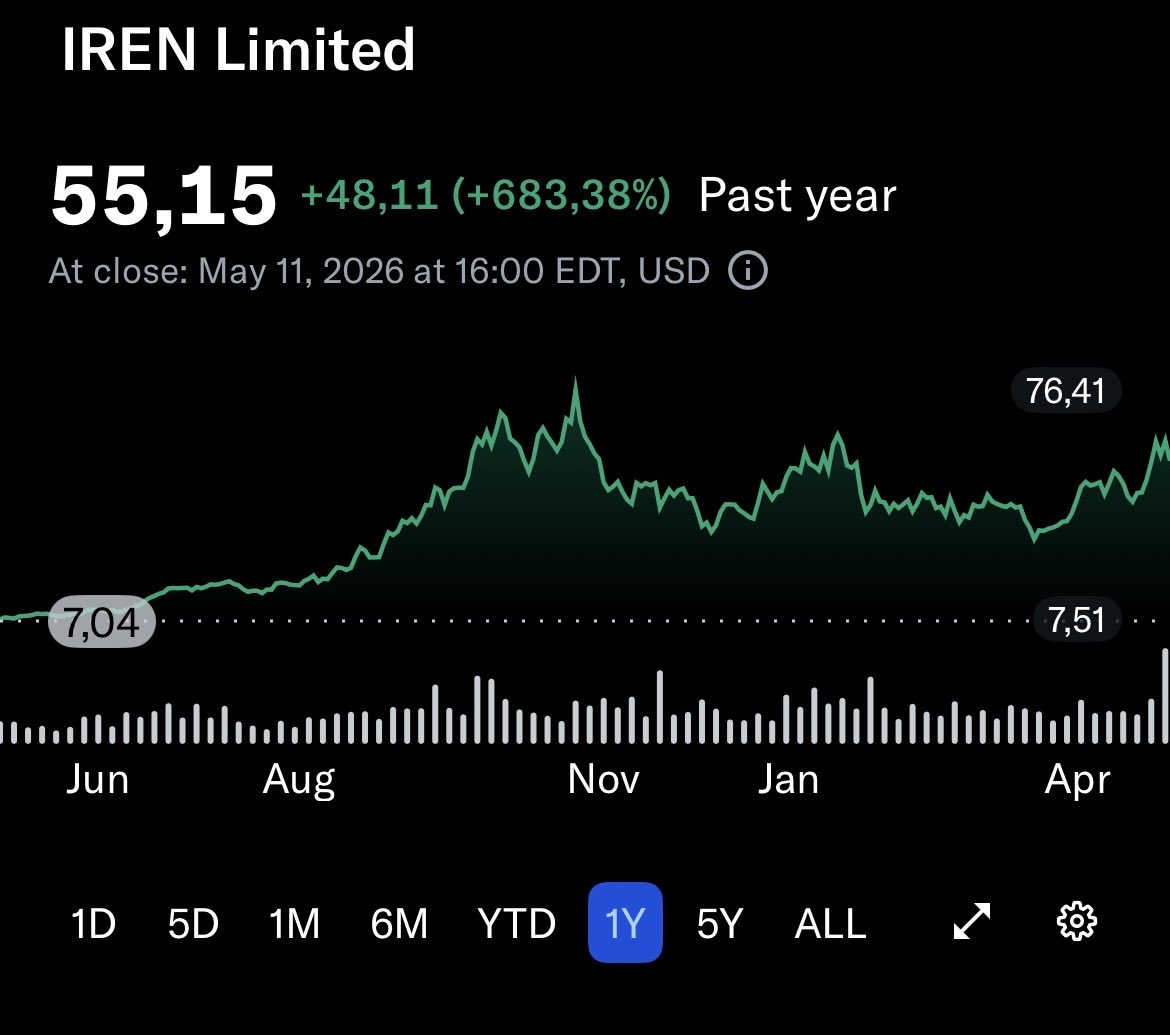
Even after today's incredible market recovery, $IREN is still down nearly 50% from its local highs made in June.
There is no doubt that this has been one of the most vicious sell-offs in the company's history.
The question any rational investor should be asking at this point is whether the drawdown is justified. Is the market getting this right, or is it mispricing something and presenting investors with a significant opportunity?
While it's true that $IREN has been underperforming its peers this year, the honest truth is that most AI and data center related stocks have been sold off aggressively over the past few weeks.
Some of it comes down to valuations getting stretched, but a lot of the market-wide panic traces back to a couple of catalysts that spooked investors out of high beta AI stocks.
The first that comes to mind is the recent release of Kimi, a Chinese open weight model that's knocking on the door of the frontier, roughly one generation behind in capability.
To me this is a DeepSeek 2.0 moment, plenty of panic with little substance behind it. It's true that broader adoption of open weight models threatens the market position of the frontier labs, which have enjoyed extraordinary growth curves so far. But it is by no means a bad thing for hardware makers or cloud providers like $IREN.
After all, end users still have to run the model somewhere, meaning on a cloud provider's servers built from AI hardware. If anything, the commoditization of the model layer is a great thing for the companies upstream of it, as cheaper tokens lead to greater adoption of AI (think Jevons paradox).
The second scare, and the most recent one, is more nuanced. On Monday a report claimed that a Shanghai-based, state-backed firm has begun mass-producing homegrown DUV lithography machines, the deep-ultraviolet immersion tools ASML has dominated for years. $ASML fell as much as 8% intraday, and a lot of AI stocks went down with it.
I have since read plenty of reasonable takes from people far more knowledgeable on lithography than me. Some argue $ASML retains a significant lead for many years to come. Others point to China's track record of commoditizing high-end tech, pressuring the pricing power and market share of Western competitors, and argue it's only a question of time until they catch up.
As an $IREN investor, the eventual outcome is pretty much agnostic to me. It's either neutral or potentially even positive.
If China stays behind the frontier of DUV lithography for another decade, it's a non-event. If they catch up quickly, then if anything it should be read as a positive for anybody downstream of the hardware sellers.
Cheaper hardware directly reduces the capex a cloud provider needs, which is already a positive on its own. But push the thought further and ask what happens with the cost savings from cheaper hardware. This is a topic explored at length in our recent deep dive; The Golden Age of Neoclouds.
In a typical competitive market, those savings get passed down to the consumer, making it a neutral event for cloud providers. That only holds, however, if market participants can deploy enough of the cheaper hardware to compete the savings away through undercutting. I've argued in the report that the primary constraint heading into the end of this decade becomes access to power, and with it the ability to bring data centers online at scale.
The end result is that market forces, constrained by data center supply, will lead to most upstream cost savings consolidating at the cloud layer instead of passing through to the end consumer. Users still benefit from token costs falling through technological improvements, but hardware prices coming down is primarily a gift to cloud providers, at least until the power bottleneck lifts, which won't be for a very long time as I've argued in detail in the deep dive.
So to sum up, China getting into DUV lithography is either neutral or positive for $IREN. For some semi-related companies it's either neutral or negative, which makes the sell-off more rational as it relates to them.
So why is the market selling off the entire AI sector without caring about the nuances of how these events hit individual companies differently?
For one, markets rarely behave rationally. After a hot run, any negative-sounding news becomes an excuse to sell, and often to sell everything and ask questions later. Many investors also generalize instead of thinking impacts through the way more sophisticated ones do. And the AI industry being young and not yet well understood, with a limited track record, adds to the pile.
In any case, this has produced what I consider a generational buying opportunity in $IREN (NFA, of course).
Today the stock trades at ridiculous levels relative to the company's fundamentals. By the end of next year $IREN will have over 1.2 GW of data center capacity online, which should support ARR comfortably above $12 billion. Ironically, $IREN trades at a market cap of $12b today. Let that sink in…
I also get the concerns about profitability and dilution, but as someone who has done extensive modelling on this, I consider both fears overblown.
$IREN's most recent deals with $NVDA and AI-native enterprises carry very attractive project-level margins of over 25%. That accounts for guided COGS, depreciation of both the DC infrastructure and the GPUs, financing costs, and a hypothetical 21% tax if these projects were taxed in isolation (which they aren't, of course).
This gives a good picture of where $IREN's net income margins trend as the company scales. Management is investing heavily into branding and talent right now, but those expenses won't rise anywhere near as fast as the megawatts coming online, so operating leverage does the rest.
Today $IREN holds about 5.8 GW of secured power across a rapidly growing powered land portfolio. Once fully built out, that should comfortably carry $50-$60b in annual revenue. At net margins around 20%, which I deem a realistic long-term target at that scale, you're looking at $10-$12b of net income.
I believe $IREN is roughly 5-7 years away from that point. Given the tremendous earnings growth the path implies, multiple consecutive years of more than 100% growth, a PE of 50 would be very fair, if not conservative. That implies a market cap of $500-$600b.
The way I see it, the opportunity couldn't be more clear.
Even accounting for massive continued dilution, say outstanding shares more than tripling from today's levels, we're still looking at a share price around $500 in a relatively short timeframe.
And on dilution specifically, model out the pipeline and you'll notice the need for it diminishes over time as operating cash flows scale, all of which can and will be reinvested into growing the pipeline.
$IREN is currently in what I consider phase 1 of a decade-long growth spurt, with operating cash flows still tiny relative to where they'll be a few quarters from now, so the need for equity raises is at its highest right now and should gradually level off as revenue-producing capacity comes online.
Long story short, dilution isn't something I lose sleep over. It primarily comes down to whether $IREN delivers on the buildout of its powered land portfolio, which I believe they will given their track record.
The other factors I watch closely are competitors' ability to bring compute online and the useful lifespans of GPUs. Luckily both are trending in the right direction, with power scarcer than ever and GPU lifespans extending well beyond what most initially expected.
TLDR:
As someone invested in the stock since $4.8, I believe $IREN today trades at one of the most attractive valuations in the company's history, especially on a risk-adjusted basis.
Thank you for reading, cheers! ✌️
$IREN is no longer a miner → it is now a NVIDIA‑aligned AI hyperscaler. Sweetwater becomes the global DSX showcase.
$IREN now sits at the center of the 5‑GW AI‑factory buildout, the largest AI‑infrastructure deployments ever announced.
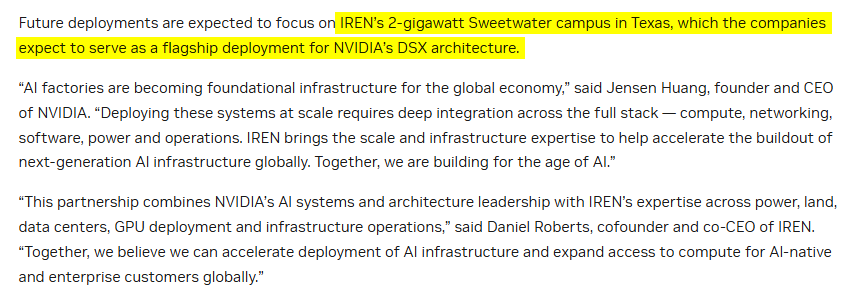
👉Sweetwater becomes the primary global showcase for NVIDIA’s DSX AI‑factory architecture
NVIDIA explicitly stated that $IREN’s 2‑gigawatt Sweetwater campus in Texas will serve as the flagship deployment for DSX. This is not a small detail.
Sweetwater becomes the reference design for future AI factories. Every hyperscaler, enterprise, and sovereign AI buyer will look at Sweetwater as the model.
IREN becomes the first and most visible DSX partner globally.👀
$IREN Tourists
These days it's getting painfully obvious who the 10% of investors are that succeed over the long term, versus the 90% that get chopped up by the market.
I cringed every time I saw larger accounts on X proudly declare having sold $IREN sub $40. Meanwhile, the exact same people were bull posting nonstop at all time highs.
We call them tourists.
They were never true investors, they were speculators, meaning they never truly understood what they owned. And selling $IREN at these levels is about as clear a demonstration of that as it gets.
Something tells me those decisions won't age well...
This is BEYOND insane:
AI compute demand is now growing at over 2 TIMES the rate of Moore’s Law, creating a massive shortage.
Just to meet current demand, $500 billion must be invested in data centers PER YEAR until 2030.
What does this mean? Let us explain.
(a thread)
🧱 $IREN: 1GW+ operational, expanding to 2.3GW, NVIDIA GPUs ordered, AI-ready, real revenue.
💭 $FRMI: 0 MW, no GPUs, no revenue, just PowerPoints and promises.
One is real AI infrastructure — the other is a story stock with SAME market cap!
$IREN is insanely cheap here. 🧠⚡️
The Fourth Industrial Revolution is defined by GPUs as the new workers. i.e. millions of computers inside AI factories, turning raw data into intelligence.
Everyone talks about Time to Power.
An even bigger bottleneck is Time to Data Center… or more simply, Time to Compute. That’s the race.
Some ppl still bagholding scam cos like $MARA $CLSK — deep underwater 💦
I was there too.
Almost 4 months ago I sold it all & went all in $IREN $CIFR + others 🔥
Best move I ever made.
It’s never too late, potential here is still 10x+ 🚀
Give up the dead weight & move forward.