#KMCSpeciality Hospital is on path to achieve 1000cr Revenue by FY31/FY32 implying 20-25% CAGR over next 5 years
Lets consider this simple math
FY25 beds occupied - 225, Revenue 232cr (1.03cr/bed)
FY26 bed occupied - 251, Rev 306cr (1.22cr/bed)
Co is adding 591 beds (500Trichy + 91 B'lore) to its existing 330 bed capacity, taking the total to 921 beds by FY30, in a phased manner.
Considering 70% utilization of 921 beds = 645 and modest 6-7% increase in ARPOB, #KMCSpeciality is poised for a 1000cr Revenue in FY32, if not FY31. (Note that ARPOB has been increasing by >10% annually for last 3-4 years).
That implies >20% Revenue CAGR for next 5 years!
Thats a solid growth road-map.. and along with growth, comes re-rating which hopefully should give even better stock price CAGR
Discl: Bought at 65-70 levels and holding. Not a recommendation, DYOR
#Valueinvesting
#Multibagger
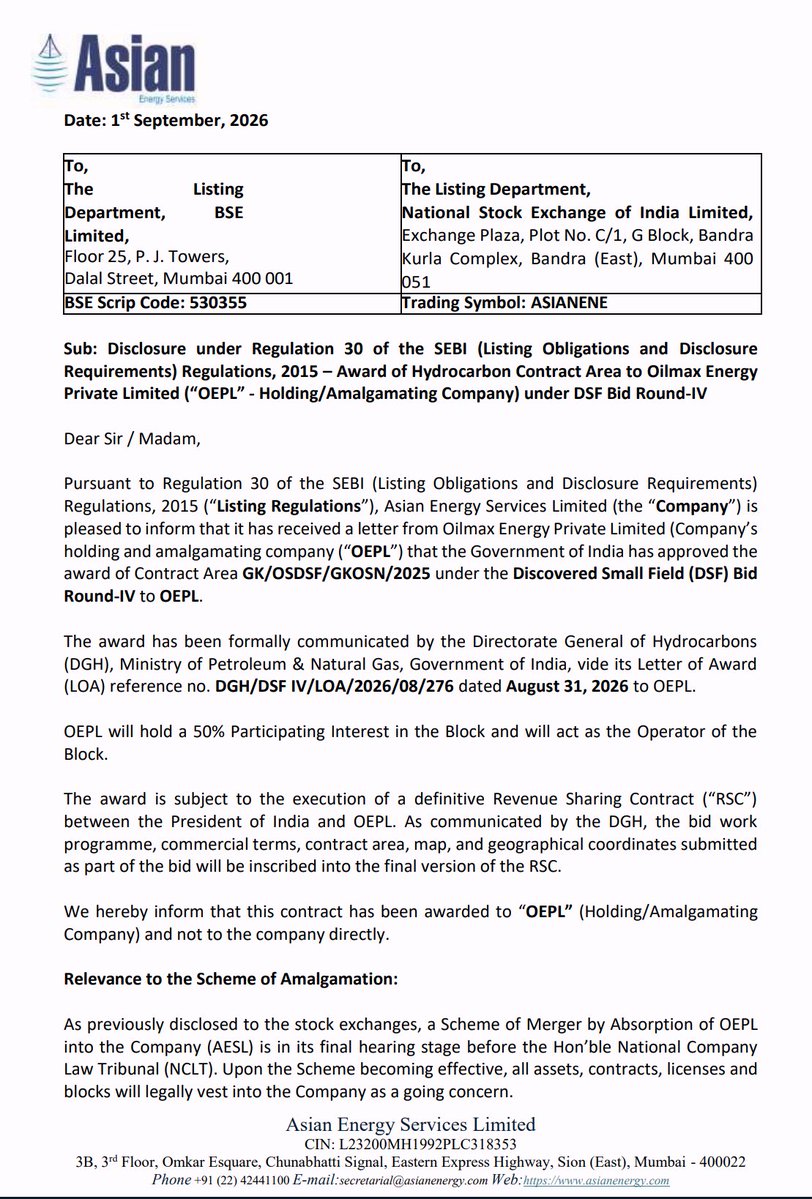
Asian Energy services:
Oilmax Energy Private Limited - which is geeting merged into Asian Energy Servies - have received a new contract under the Discovered Small Field (DSF) Bid Round-IV to OEPL.
...............
I had written about this company earlier.
Quick summary of the special situation here and the growth triggers.
Asian Energy Services × Oilmax: an interesting energy special situation
Oilmax Energy is being merged into listed Asian Energy Services. This is not a conventional acquisition — Oilmax shareholders receive AESL shares, while Oilmax's assets and liabilities move into the listed company. The agreed swap ratio is 117 AESL shares for every 10 Oilmax shares.
The strategic logic is interesting:
AESL: seismic → EPC → field development → O&M → production services
Oilmax: owns the actual oil & gas assets
Post-merger, AESL combines upstream asset ownership with the technical/engineering capability to develop and operate those assets.
Oilmax currently produces ~2,500 boepd, with historical EBITDA margins of ~55%.
The bigger opportunity is the production ramp:
→ Amguri + Tiphuk + Duarmara + Indrora/Mevad
→ Target ~10,000 boepd by FY29/30
→ Revenue ambition ~₹1,000cr
→ EBITDA potential >₹400cr
Meanwhile, the existing AESL services business has a ₹1,754cr order book, with management guiding 30–40% FY27 growth and 17–18% EBITDA margins. Kuiper adds an international technical-services growth engine.
Management's longer-term ambition is ~₹3,000cr revenue and ₹700cr+ EBITDA.
That's what makes the merger interesting: AESL provides the growth/service platform, while Oilmax can become the high-margin earnings engine.
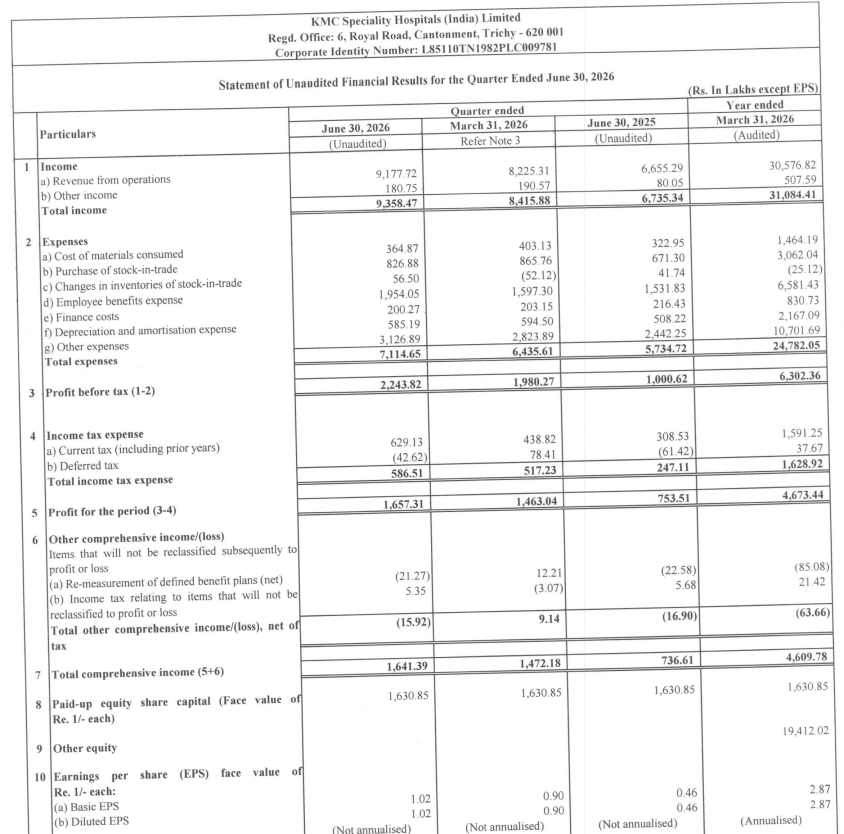
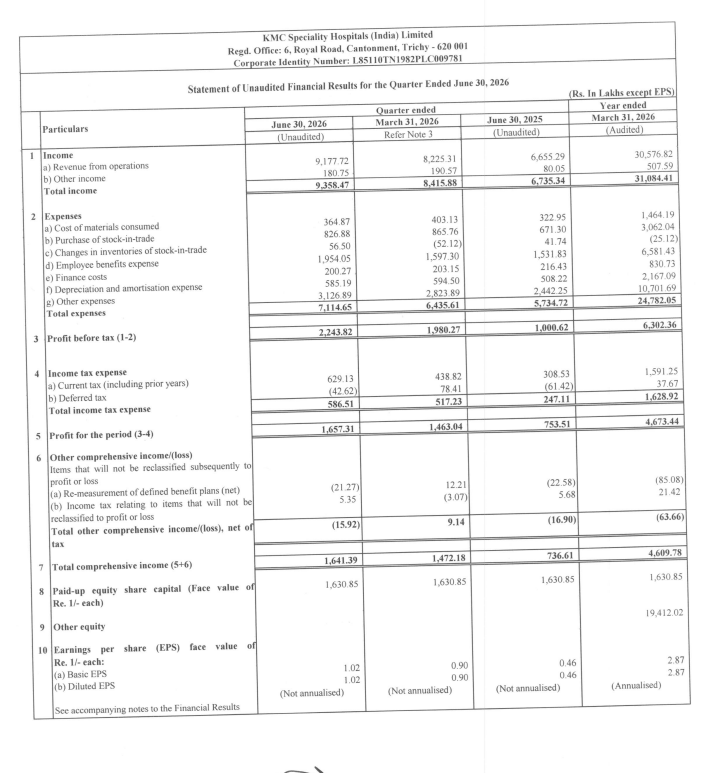
#KMCSpeciality Hospital results are Bestest ever
Sales 91.8cr +38% yoy
EBIDTA 28.4cr +73% yoy
Margins 31% vs 25% yoy
Profit 16.6cr +121% yoy
Results are by far the best ever, which I believe is led by improved utilization in new hospital
Happy to have fished the stock at ~67 levels
#Valueinvesting
#Multibagger
Sudeep pharma
Catch is : Lithium Ion Phosphate
However their core business is as such that makes 25% to 27% of PAT margins
These times of PAT margins are rare in companies
Also the existing business is growing decent 30% pace
#sudeep