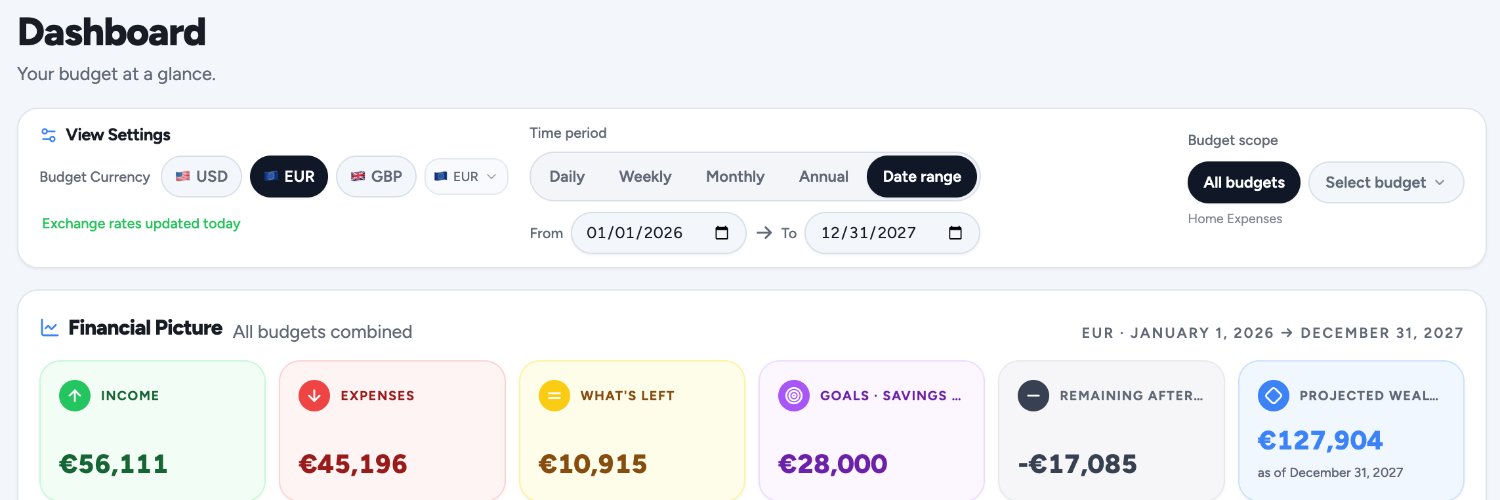
Most budget apps want your bank login. Clear Budget doesn't. Add income, expenses, any currency, any frequency, and see what's left. No account needed.
https://t.co/gnae3AReNW
@SparkingFIRENC This is a great example of why mixing weekly, monthly and annual expenses in one budget gets interesting. Seeing everything converted to the same period makes the full picture much easier to understand.
@The_Money_Buddy This is exactly why changing the time period can make a budget click. The same numbers can feel completely different when you see them daily, weekly, monthly, or annually.
@sbsun Most of the time it's a timing problem, not a spending one. If you get paid weekly or biweekly but your big bills are monthly, the mismatch creates a false crisis. You have the money, just not in the right week.
Mint shut down and most replacements want your bank login or charge more than Mint ever did. People just want the simple thing: add your numbers, see what's left. Not a dashboard, not a subscription bigger than your streaming bill.
The hardest part of going freelance isn't losing the salary. It's losing the certainty that your income is real. First quiet month hits and you have no system for turning uneven payments into something you can actually live on. Without that, every slow week feels like proof you
@Olking07 I’d stop comparing. Two people can manage their money exactly the same way and still have completely different financial pictures because their incomes are different. Your progress makes more sense measured against your own goals.
@uncvoss A budget can show you exactly where the problem is. It can’t magically make the numbers work. Sometimes cutting small expenses helps, and sometimes the income simply doesn’t cover the cost of living.
@BoomerDivvies As a French person, I can confirm France doesn’t normally cost $23k for two weeks 😂 This sounds less like a France budget and more like a luxury France budget.
@Idontgive2u This is exactly why a budget should show you the numbers, not judge you for them. Sometimes you can organize every expense perfectly and the amount left is still the amount left.
@acenter102 This is the kind of budgeting I like 😂 Spend less on the things you don’t care about so you can enjoy the trip without feeling like you’re restricting yourself everywhere.
@tinybird420@girlabductor This is actually a great example of budgeting for replacement rather than constantly upgrading. $250 every few years can look very different from turning a new phone into another monthly payment.
@seunogunseyee right?? sometimes seeing the timing laid out makes you realize the problem isn’t necessarily the total money, it’s the cash flow between paydays 😭
@DistroFi_app Exactly. They’re not really “extra” checks when you look at the full year — they’re part of the 26-paycheck cycle. Planning for them upfront makes the whole picture much clearer.
biweekly pay means two months a year you get three checks instead of two. most people waste the third one. it's not a bonus, it's 26 pay periods not dividing evenly into 12 months. plan monthly assuming two checks and you're undercounting your income by two paychecks a year.
"Bills keep piling" is almost never a spending problem. It's a timing problem.
Weekly income, monthly rent, quarterly insurance, each on its own clock. You have the money, just not in the right week.
One comparable view turns the pile into a schedule you can plan around.
Starting a six-month contract feels like regular income until you realize it has an expiration date. Most budget tools treat every month as permanent. You spend like the contract lasts forever, then panic in month five. Plan around the real end date.
@blond3dBee This is such an important point. A shared financial picture matters even if only one person handles the day-to-day finances. Both people should know what comes in, what goes out, and what’s left.
@0xfablo@jadonxn@MEXC I think the key is separating your expected grocery budget from what you actually spend. When prices change, you can see the difference clearly and adjust the next period instead of pretending the original budget still works.
@AjihMichael The income volatility point is key. Even with the same annual income, someone with variable pay has a completely different cash-flow problem from someone receiving the same amount every month. Timing matters as much as the total.