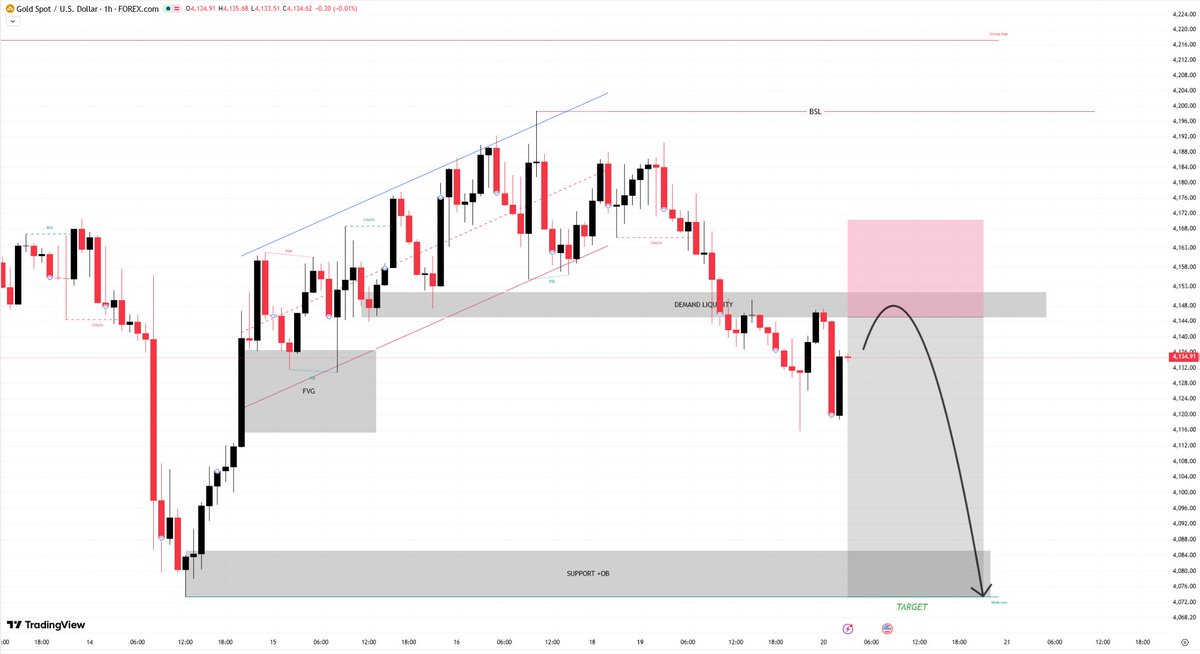
#XAUUSD
Demand and Liquidity Zone — 4,145–4,152: Following a strong bearish move, the price is currently reacting near this marked zone.
#GOLD
If the price continues to face resistance, the market may be at risk of further downside.
Downside target: 4,073–4,085✅️
Please "like" this post if you find our entry levels and trade direction helpful. 💙
THIS 49-MINUTE LECTURE EXPLAINS THE MATHEMATICS BEHIND THE PRICE OF AN OPTION.
Not a trading strategy.
Not a prediction.
A framework for answering one question:
what should a derivative actually be worth?
The professor starts with the one-step binomial model.
The stock can move up.
Or down.
Build a portfolio that replicates the option's payoff.
And suddenly you don't need to guess the future price.
You can price the derivative by constructing the same payoff another way.
Then comes the idea that changed modern derivatives:
risk-neutral valuation.
Under the risk-neutral measure, the expected payoff is discounted at the risk-free rate.
The actual expected stock return disappears from the pricing equation.
That leads directly to the Black–Scholes equation.
And the lecture shows something even more interesting:
Any tradable derivative has to satisfy the same fundamental pricing equation.
The reason is hedging.
Construct a replicating portfolio.
Continuously adjust the position.
Eliminate the relevant source of risk.
Then the derivative's price is no longer whatever the market feels like paying.
It is constrained by the cost of replication and no-arbitrage.
The lecture then connects Black–Scholes to the heat equation through a change of variables.
A problem from financial markets...
turns into a problem from mathematical physics.
And that's the part most traders miss.
Black–Scholes isn't fundamentally about predicting whether a stock will go up or down.
It's about constructing an equivalent financial payoff and pricing it without arbitrage.
The market can be uncertain.
The stock path can be random.
But a carefully constructed hedge can still impose structure on the price.
So instead of asking:
“Where will BTC be at expiration?”
the quantitative question becomes:
“What portfolio replicates this payoff, and what should that portfolio cost today?”
That's the idea sitting underneath modern options pricing.
Don't predict the payoff.
Replicate it.
Politicans debating raising $ 30 trillion US debt limit bad comedy, “kabuki theater.” Facts are: US bankrupt. Unfunded liabilities as Social Security are over $250 trillion. Financial market “derivative assets” measured in quadrillions…thousands of trillions. WTF. Buy G,S, BC.
Black-Scholes Equation was Developed by Fischer Black, Myron Scholes and Robert Merton in 1970s, it calculates the profit on a financial derivative based on the stock price.
This equation allows us to model the value of a financial derivative at various stock prices.
@MediaCellPPP@BBhuttoZardari PML-N and PPP follow dynastic politics—power stays within families. PTI, in contrast, promotes common parliamentarians to top positions.
@MediaCellPPP@BBhuttoZardari PML-N and PPP follow dynastic politics—power stays within families. PTI, in contrast, promotes common parliamentarians to top positions.
@RubinakhalidPPP PML-N and PPP follow dynastic politics—power stays within families. PTI, in contrast, promotes common parliamentarians to top positions.
@FaisalJavedKhan PML-N and PPP follow dynastic politics—power stays within families. PTI, in contrast, promotes common parliamentarians to top positions.
@PTIofficial ChatGPT said:
PML-N and PPP follow dynastic politics—power stays within families. PTI, in contrast, promotes common parliamentarians to top positions.
@KaliwalYam ChatGPT said:
PML-N and PPP follow dynastic politics—power stays within families. PTI, in contrast, promotes common parliamentarians to top positions. @CMShehbaz
@obaidM02 Aslaam o alaikum bahio ..siasat choro.. asaal musla ikhlaqiat ka hae ..yae Jo risar nae families ko target kurna Shuru kur di hae yae qabil qabool nai..