Would you trust an AI agent with your money? 👀
We're getting into the future of agentic finance tomorrow on The Adoption Pod with Neeraj Prasad from MoonPay Labs.
I'm especially curious how close we are to AI agents actually transacting on our behalf.
Tuesday, 9 PM ET. Come hang out!
Would you let an AI agent pay your bills?
Tomorrow on The Adoption Pod, @neerajprasad from MoonPay Labs joins me and @nickisanders to talk all things agentic finance.
T.A.P. in every Tuesday at 9 PM ET.
I’m humbled to announce my latest launch.
After watching yet another board “express full confidence” this week, I asked myself: what if CEOs could plan their personal lives with the same rigor they bring to quarterly guidance?
So I built the CEO Affair Allowance Calculator.
Key learnings from the data:
1. Founders get a 2.5x multiplier. That’s not me, that’s corporate governance.
2. Every mention of “AI” on an earnings call buys you goodwill.
3. A signature outfit is worth about three-quarters of an affair.
4. Nothing, and I mean nothing, survives a foreign intelligence asset.
Free for all CEOs. Everyone else, please continue to read your code of conduct.
https://t.co/aRPnXrhfgs
Just found out my kindergartener nephew panicked and starting crying during his Veterans Day performance this morning because he couldn't remember if it was him or his dad who is the veteran when the school asked all the vets to come sit in the front row.
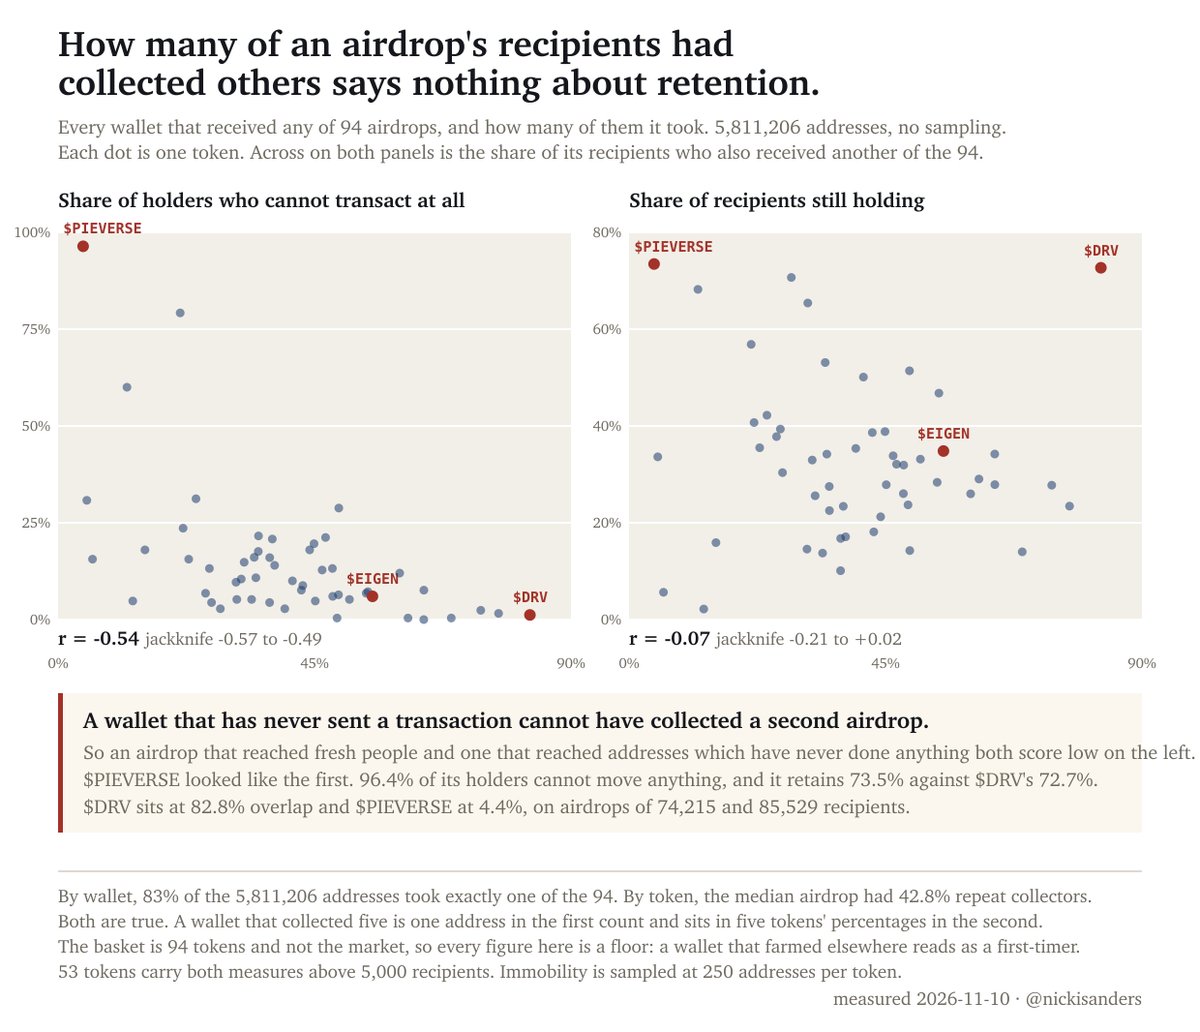
Crypto assumes airdrops are farmed by a recirculating class that collects everything. I took all 94 airdrops in my holder baseline and counted how many of them each wallet received. 5,811,206 distinct addresses, every Transfer event, no sampling.
Counting wallets, that class barely exists: 83% of the addresses took exactly one. Counting airdrops it looks nothing like that, because the median token had 42.8% of its recipients already holding another. Both numbers are right. A wallet that collected five is one address in the first count and sits in five tokens’ percentages in the second, so repeat collectors get counted repeatedly in exactly the view that makes them look common.
The spread between tokens is where it gets interesting. $DRV paid 74,215 wallets and 82.8% of them had collected others. ethereum:0x0e63b9c287e32a05e6b9ab8ee8df88a2760225a9 paid 85,529 and 4.4% had. They retain 72.7% and 73.5%.
That pair is the result. Overlap and retention correlate at -0.07 across 53 airdrops, jackknife -0.21 to +0.02, crossing zero. Whether an airdrop landed on practiced collectors or on people who had never seen one tells you nothing about whether they stayed.
What overlap does track, at -0.54 with a jackknife of -0.57 to -0.49, is the share of a token’s holders who hold no ETH and have never sent a transaction. It is the tightest relationship in this dataset and it is nearly mechanical once said out loud. A wallet that has never sent a transaction cannot have collected a second airdrop, so an airdrop that reached fresh people and one that reached addresses that have never done anything both score low.
I had ethereum:0x0e63b9c287e32a05e6b9ab8ee8df88a2760225a9 pegged as the first kind until I checked. 96.4% of its holders cannot move anything.
The basket is 94 tokens rather than the market, so every overlap figure here is a floor. A wallet that farmed thirty airdrops none of which are in my set reads as a first-timer.
Big milestone for @tZERO. 🚀
Regulated exchange. Regulated clearinghouse. One infrastructure platform.
With its latest CFTC approval, tZERO now holds both exchange and clearinghouse registrations, expanding the products it can support across securities, tokenized assets, derivatives, and potentially event contracts.
Why does this matter? Because launching a financial product is only one piece of the puzzle. Markets also need regulated venues to facilitate trading, clearinghouses to manage counterparty risk, and infrastructure to support the entire lifecycle of a transaction.
Having both registrations under one platform gives tZERO a much broader foundation to build on and gives financial institutions a path to bring new products to market without building that entire stack themselves.
This is about much more than tokenizing assets, it's about building the infrastructure for the next generation of financial markets.
Regulated exchange. Regulated clearinghouse. One infrastructure platform.
With today’s CFTC approval of our Designated Contract Market (DCM), @tZERO has now secured both exchange and clearinghouse registrations – a major milestone in expanding our multi-asset Infrastructure-as-a-Service business.
The approval also satisfies the first earn-out milestone under tZERO’s proposed business combination with FG Imperii Acquisition Corp. and a key business target that will foster the company’s growth in 2027.
These registrations expand what we can build with financial institutions – from securities and tokenized assets to derivatives products, including event contracts and other eligible instruments, subject to applicable regulatory approvals.
Our partners bring their brands, customers and financial products. We provide the regulated infrastructure to help make their offerings possible.
Building markets for a tokenized world.
https://t.co/MJxA6vYvjp