Many economists forget that the first-order problem of an aging society, one with high life expectancy and low fertility, is how to redistribute income from workers to retirees. How fast output grows is, surprisingly enough, the lesser question.
If you have roughly as many retirees as workers, what each worker produces must be split in two, one part for the worker, one part for the retiree. At a basic level, it does not matter whether we do it through taxes, as in a pay-as-you-go social security system, or through capital income, as in a fully funded one. Workers will not be happy to see half of their income taken away, whatever the absolute level of that income.
This redistribution will poison the political system and lead, with high probability, to dysfunctional policies. We are already seeing it across Europe in the fights over retirement benefits. And much of the American unhappiness about the profits of large corporations, largely owned by the old, is the same conflict, only in the fetishized form of equity ownership.
Claims of the form “technological progress (e.g., advances in AI) will fix the problems brought by aging” miss the political economy of the situation. Aging is about politics, not TFP.
Last article of 2025.
What would have happened if the Fed hadn't raised rates in 2022?
You can't answer this with an RCT, DiD, or RD. That's not a failure, it's the nature of the question.
Why macro never had a credibility revolution, and why that's not a bad thing.
Link: https://t.co/3XK086Ptof
🇺🇸🇪🇺 The $750bn US energy purchases are not legally binding. The $600bn EU investment pledge is an "intention". The EU did not commit to US defence purchases. The EU did not commit to address non-tariff barriers in agriculture or digital taxes.
Apart from that, a historic deal.
There is an urgent need to channel retail savings into capital markets to develop those markets and finance EU priorities. An EU savings standard could increase retail participation, benefiting savers, boosting investment and supporting strategic priorities.
Extremely happy to share that the paper “Interlocking Directorates and Competition in Banking”, joint with @GuglielmoBarone and Fabiano Schivardi, has been published in the Journal of Finance @JofFinance -https://t.co/CO8kClCQma
(1/N)
Public funds to Italian firms in disadvantaged areas (ex. Law 488/92) permanently increased employment, but allocation matters: Firms selected by objective rules create more jobs per € than those favored by local politicians. https://t.co/VNZ50R98pK
President @realDonaldTrump vowed to do new things and we have something new: the American capital flight trade. It's a major pattern in markets when the president does something consequential and new, we see four things: stocks go down, bonds go down, the dollar goes down and gold goes up. The signature's very clear. It's revulsion against American assets. Foreigners less willing to put money here and Americans eager to diversify out of the country.
https://t.co/M3O7WinypR via @YouTube@BloombergTV
Meanwhile some members of the ECB's Governing Council believe the biggest risk we're facing right now is to cut rates too much. Not geopolitics, tariffs, over-regulation, lack of competitiveness, tech war, but too low interest rates. Careful what you wish for.
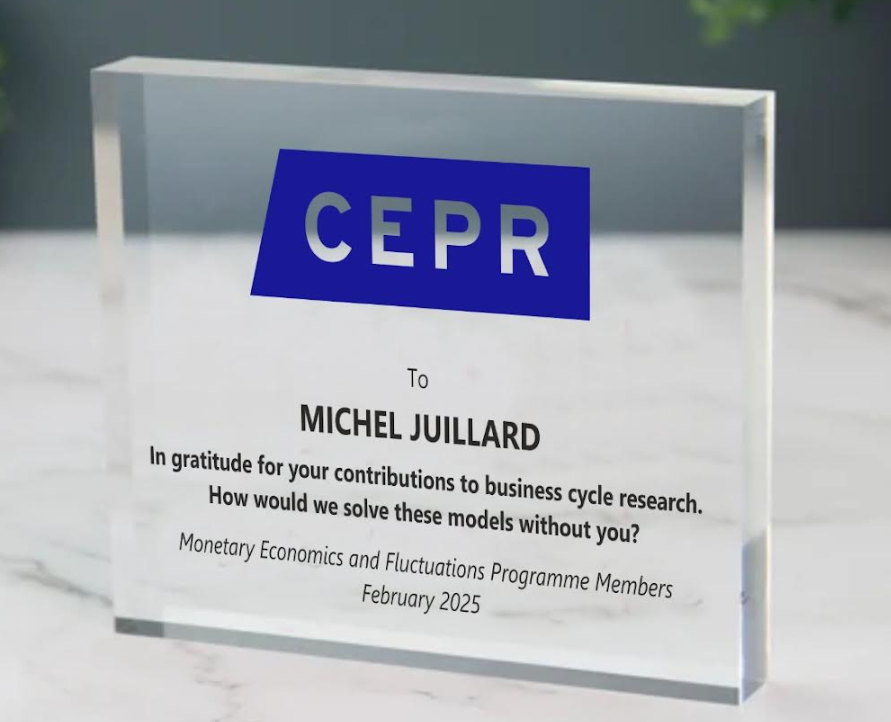
On 10-11 Feb , @banquedefrance hosted a conference to honour M. Juillard’s contributions to macroecon modeling & computational economics & 30 years of @DynareTeam
CEPR's MEF programme presented a plaque recognizing his impact on researchers worldwide
🔗 https://t.co/zL7Wg7v4m1
1/10 Europe just got a brutal wake-up call about green energy math. When wind & sun disappeared in December, electricity prices shot up 20X. Our current plans for batteries and storage won't solve this for decades. Here's the real numbers 🧵