With just four device companies having reported Q3 results, the next Semiconductor market record is well underway.
The numbers are staggering. The four giants reported 19% QoQ and 196% YoY revenue growth.
https://t.co/0pRbk8aYVJ
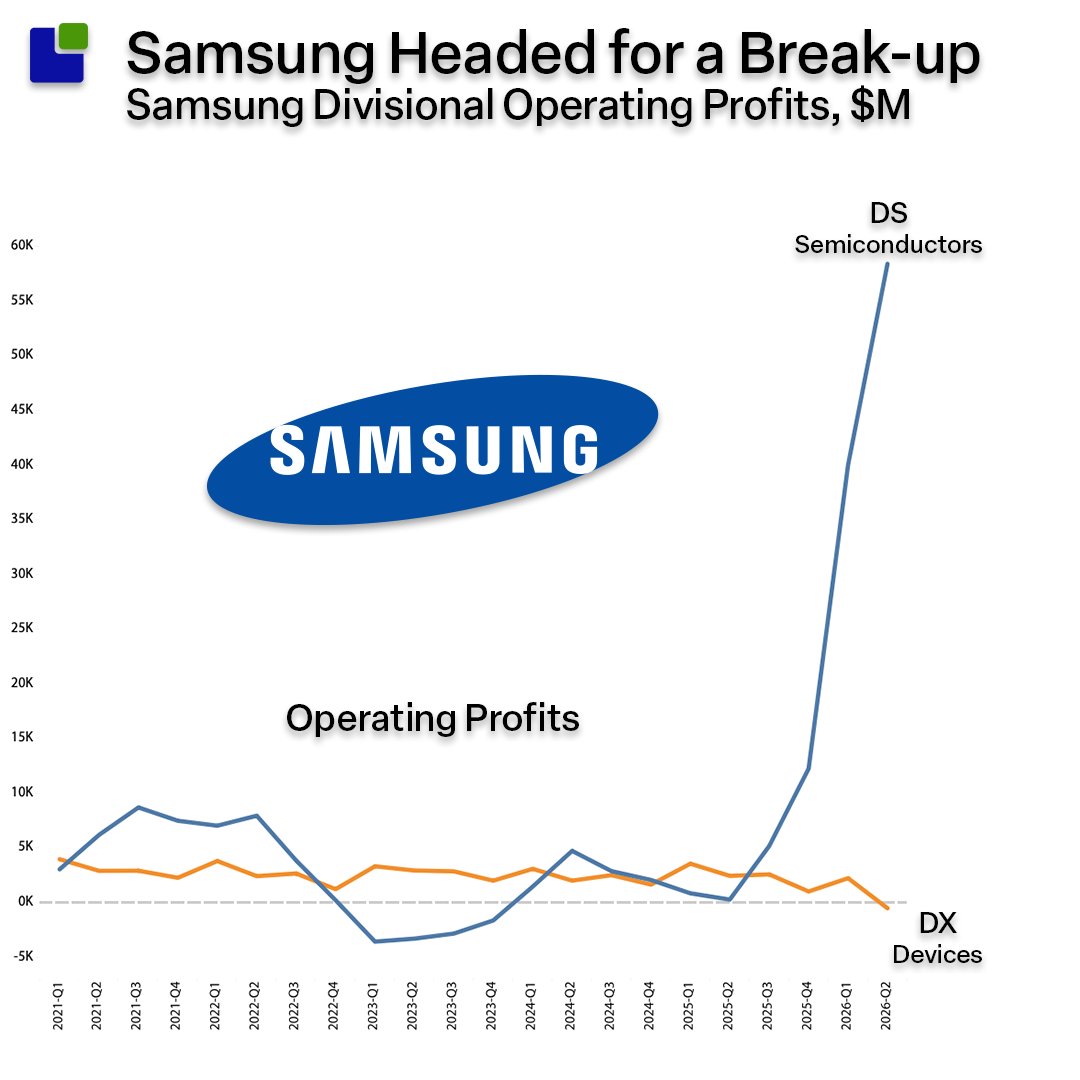
Samsung's semiconductor division strike will go down in history as the most successful union strike ever.
So far, the bonus model tied to divisional operating profits has yielded 17B$ in accumulated value and will likely exceed $25B in 2026.
https://t.co/t8Y1iXKKOA
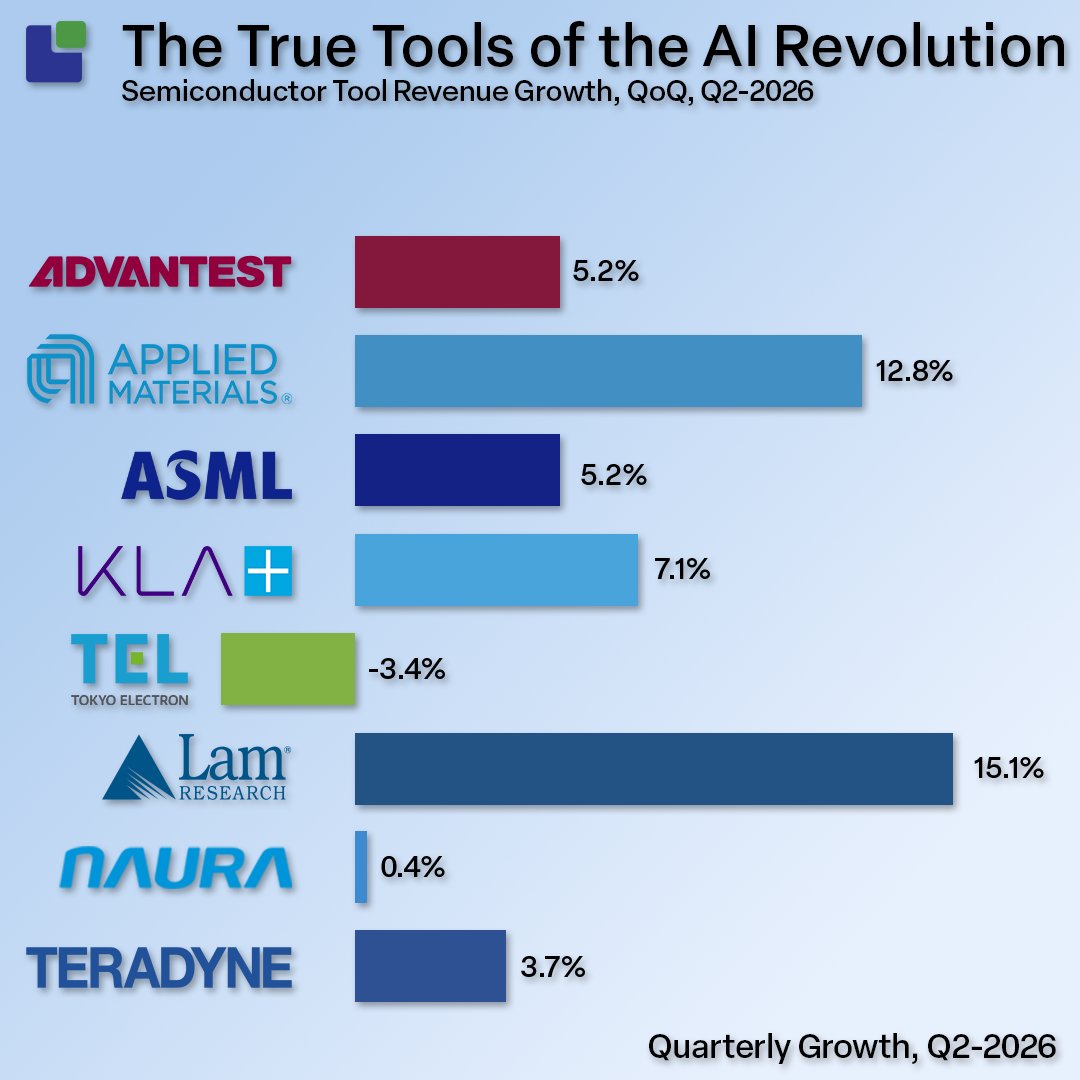
Despite the fanfare, the actual revenue from semiconductor tools has been growing at a modest rate of 23% YoY. In the same period, the semiconductor market grew by 130%
https://t.co/k4j94E221M
Where chips are made is no longer irrelevant.
This makes GlobalFoundries' EUR 1.1B investment in expanding its Dresden site with new cleanroom and laboratory space vital to a resilient European supply chain.
https://t.co/wb8MqbyoY8
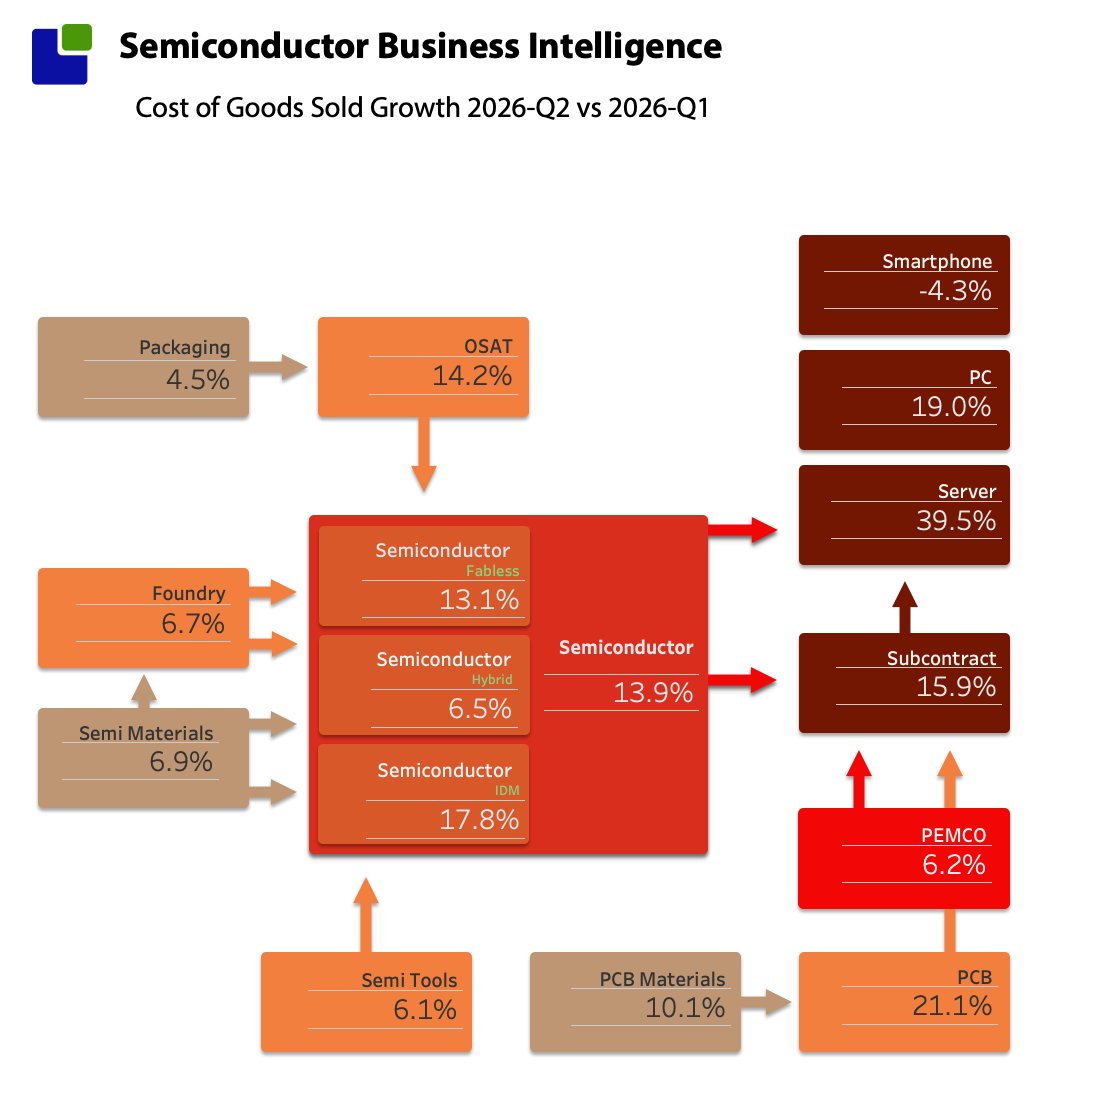
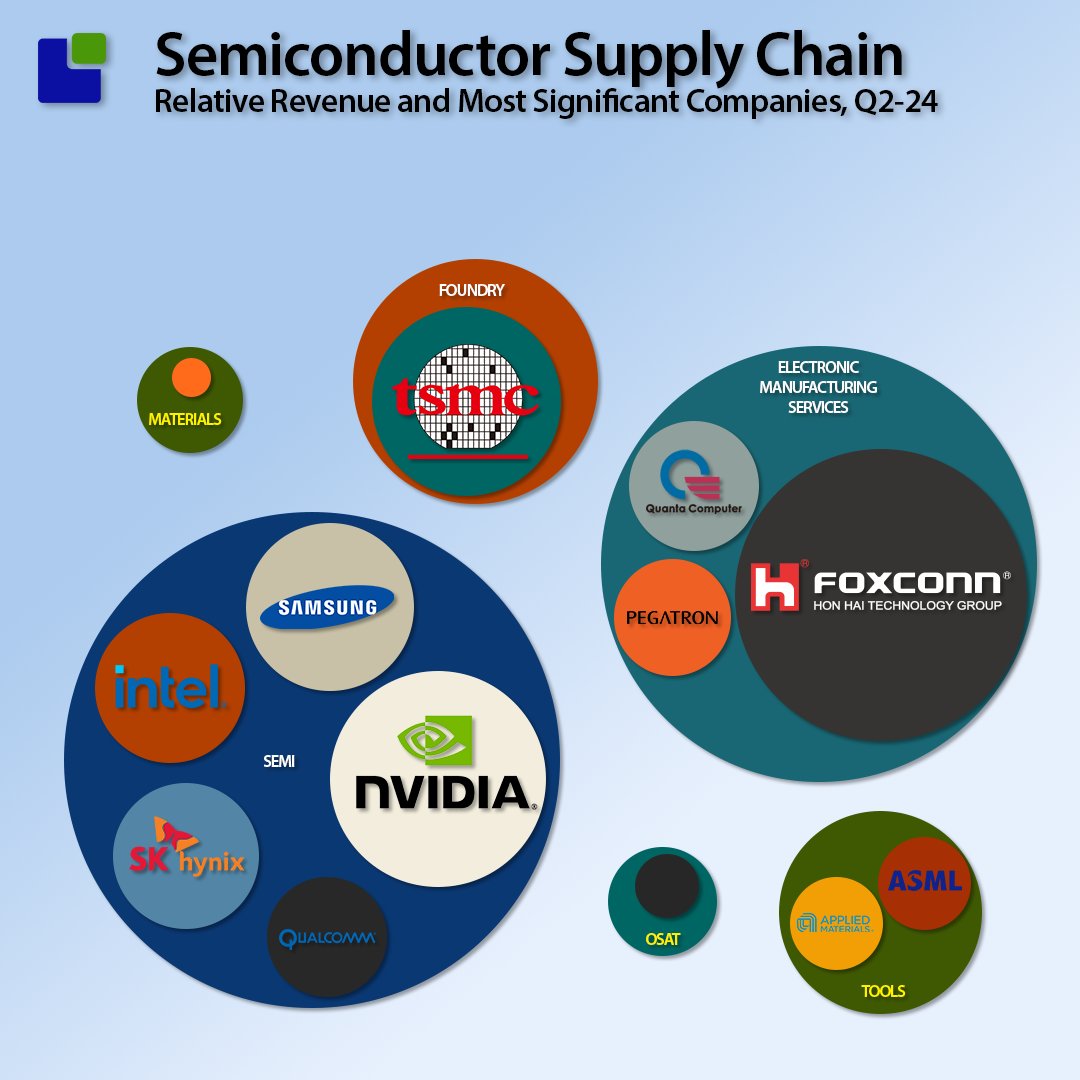
To understand the flow of materials in the semiconductor supply chain, it is more useful to examine the Cost of Goods Sold than Revenue.
https://t.co/jqHIpnc9Y7
Long before I realised they had a role in the AI Infrastructure supply chain, I used Ajinomoto products in my kitchen. The inventor of umami in powder form should have a place in every serious spice cabinet.
https://t.co/0pRbk8aYVJ
On the surface, the Oracle result was very strong from a cash-flow perspective, but the bride was not entirely dressed in white.
You can read more about the changes in strategy of the large hyperscalers here: https://t.co/Hg9LgRe65o
While the DX division has lost the power battle, its employees have lost the bonus battle and must live on one-tenth of DS employees' bonuses.
When the people begin to dislike each other and the power struggle is over, the hacksaw comes out.
https://t.co/t8Y1iXKcZ2
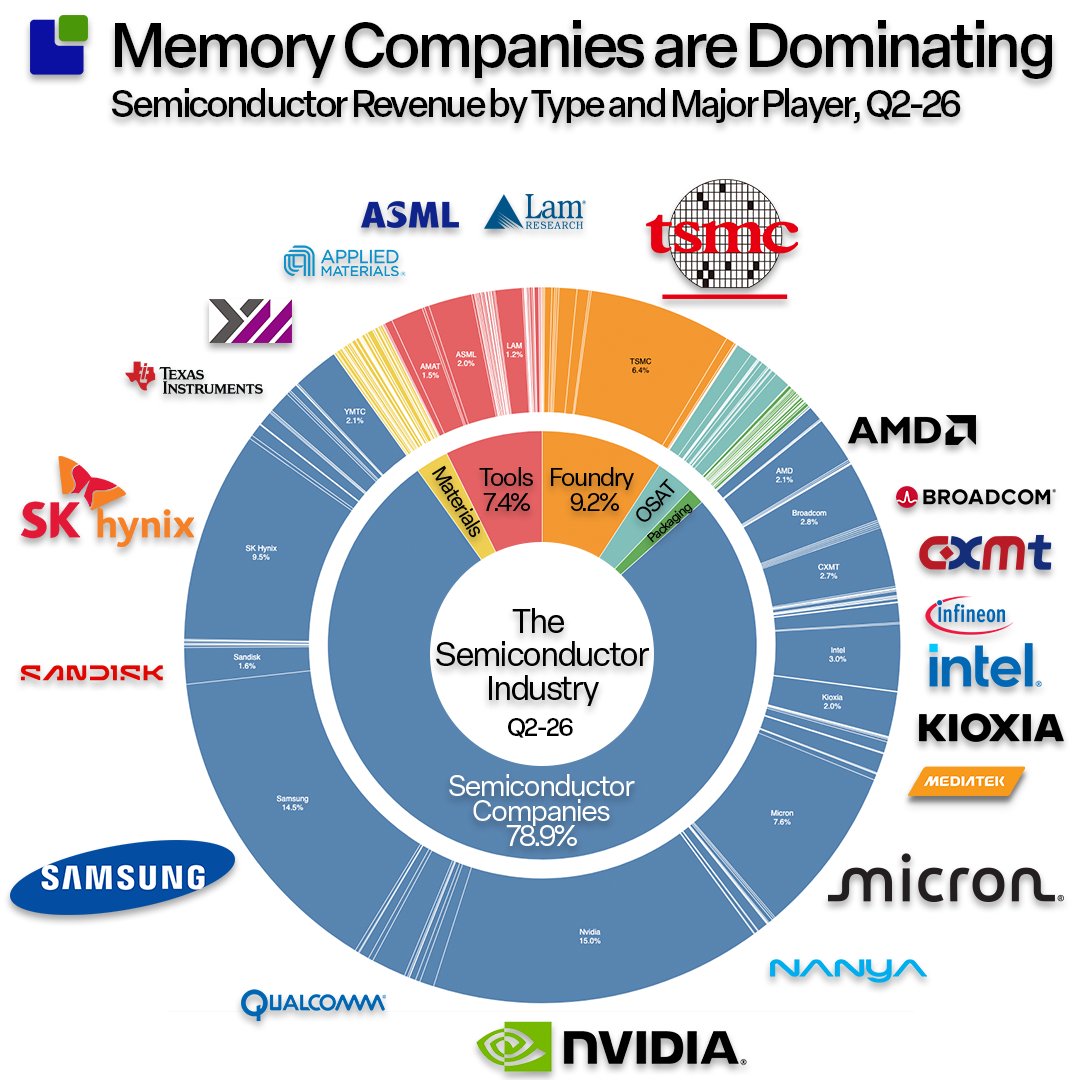
The entire semiconductor industry recorded its first half-a-trillion-dollar quarter in the second quarter of 2026. Revenue grew by more than $100B QoQ to $545B, or 22.7% growth. Of the total, $75B was driven by memory growth https://t.co/0pRbk8aYVJ
The sniper rifle has been put away.
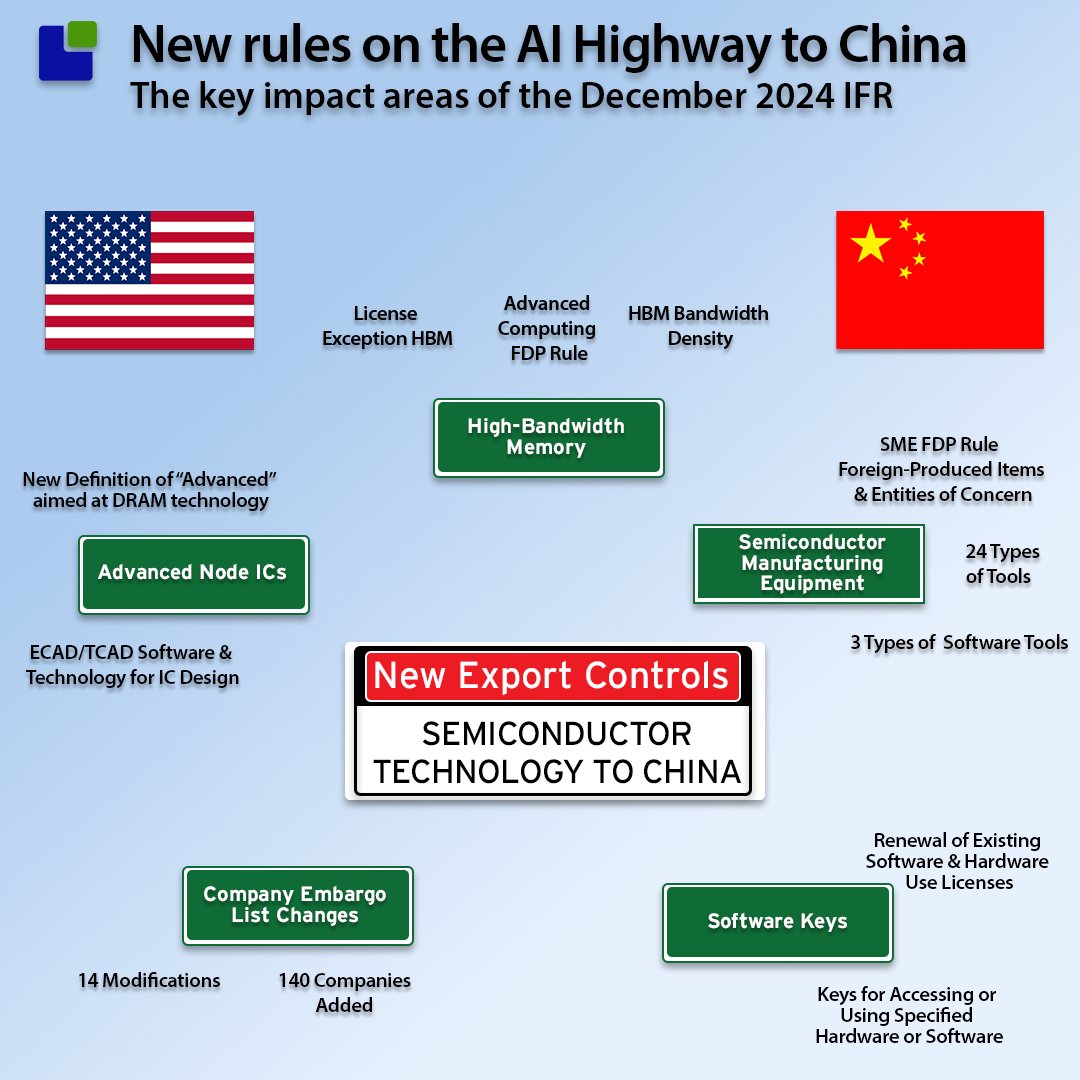
As of the end of this month, the US government is significantly tightening the control of advanced computing and semiconductor manufacturing technology.
High bandwidth memory features prominently, as does the advanced packaging of HBM and GPUs.
140 companies, including investment companies and entities outside China, have been added to the embargo list.
The Foreign Direct Product rule is extended, allowing the US administration to influence the export of subcomponents with the slightest traces of US technology.
Also included in the Christmas gift to China is the inclusion of software keys to enable design software and semiconductor manufacturing equipment already in use. This could cripple the installed manufacturing capacity in China.
ASML which this could impact, has thrown the hot potato on to the Dutch government by stating they follow Dutch legislation.
The new administration has been armed to the teeth.
https://t.co/rO15Q44Hyc
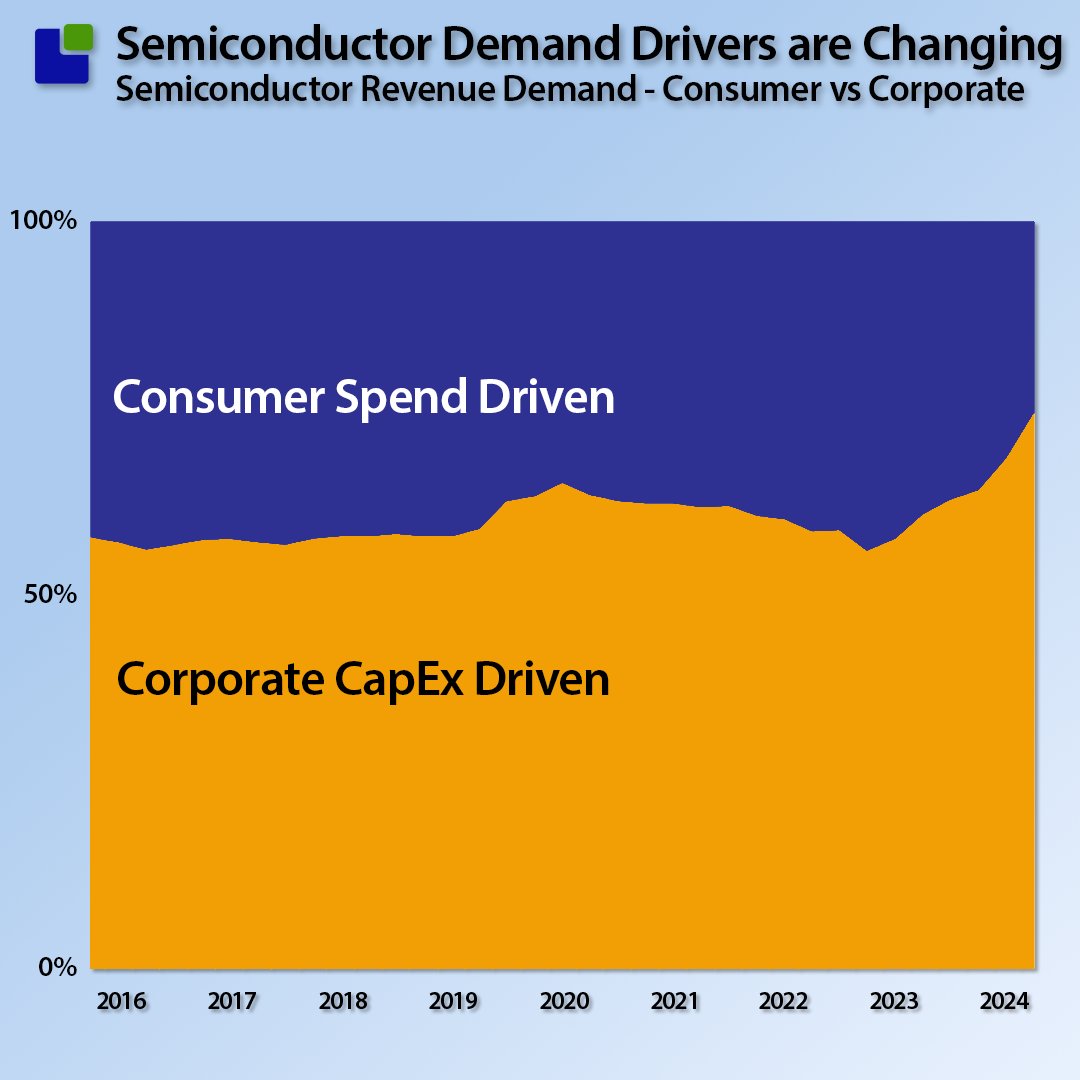
The AI revolution has made the semiconductor industry's demand equation less dependent on consumer sentiment.
This can dramatically change the semiconductor's four-year boom-and-bust cycle, during which we collectively make the same mistakes as the last cycle, laying the foundation for the next.
One critical element that will drive this trend forward is Nvidia's success outside the training needs of cloud customers. Will Nvidia also succeed in the enterprise segment's inference business?
Read more here:
https://t.co/MEqduBs6dQ
The first stage of Nvidia's impressive growth journey has been fuelled by the AI training needs of Cloud companies and AI Natives like OpenAI.
While the AI investment commitments from the cloud companies remain strong, Nvidia is looking to develop more income streams.
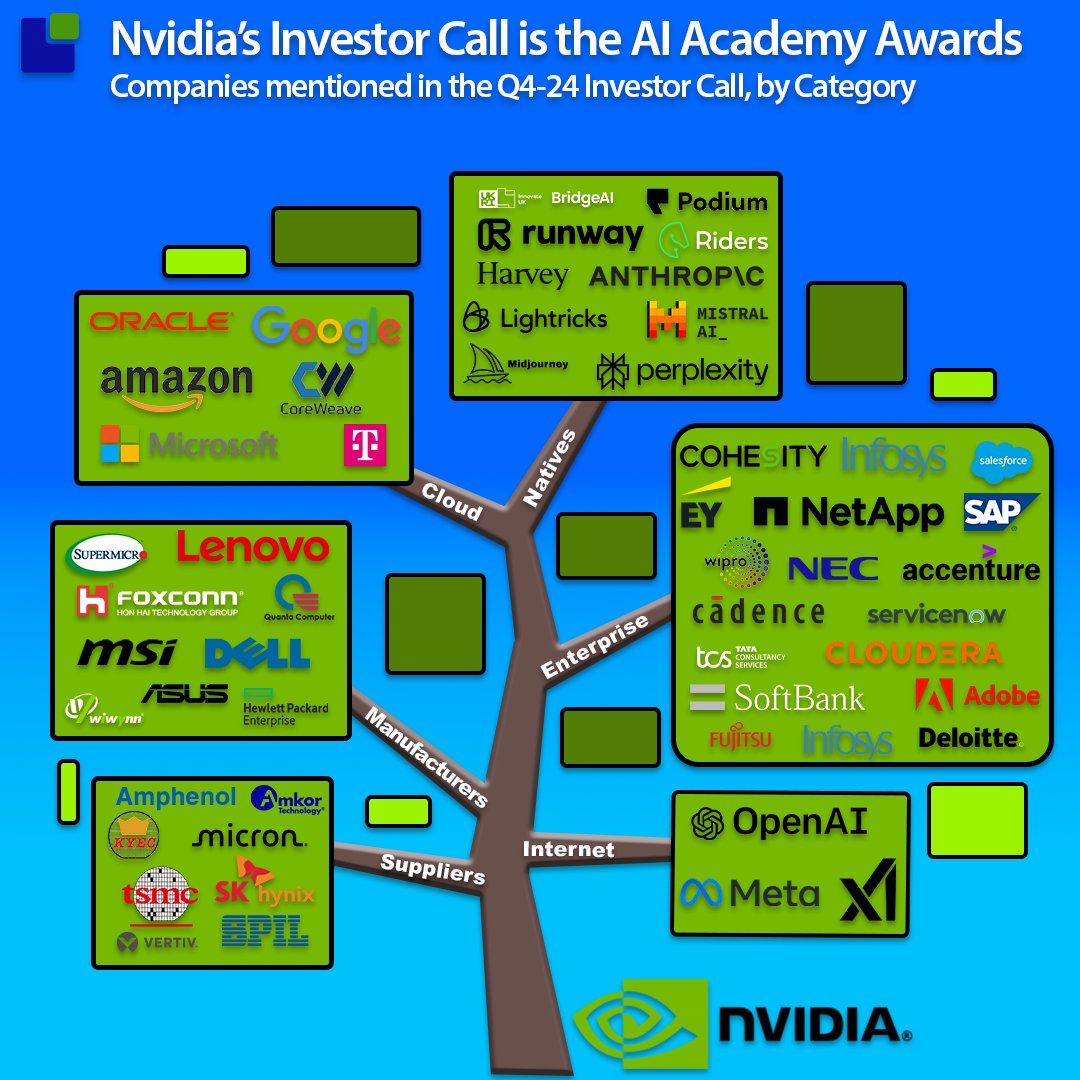
Given the number of names mentioned in the conference call, the Enterprise segment is a high-value target. Nivida mentioned 19 Enterprise companies in the call.
I have yet to detect meaningful AI investments outside Tesla in the enterprise segment, but I could be missing something. The AI models could be deployed elsewhere.
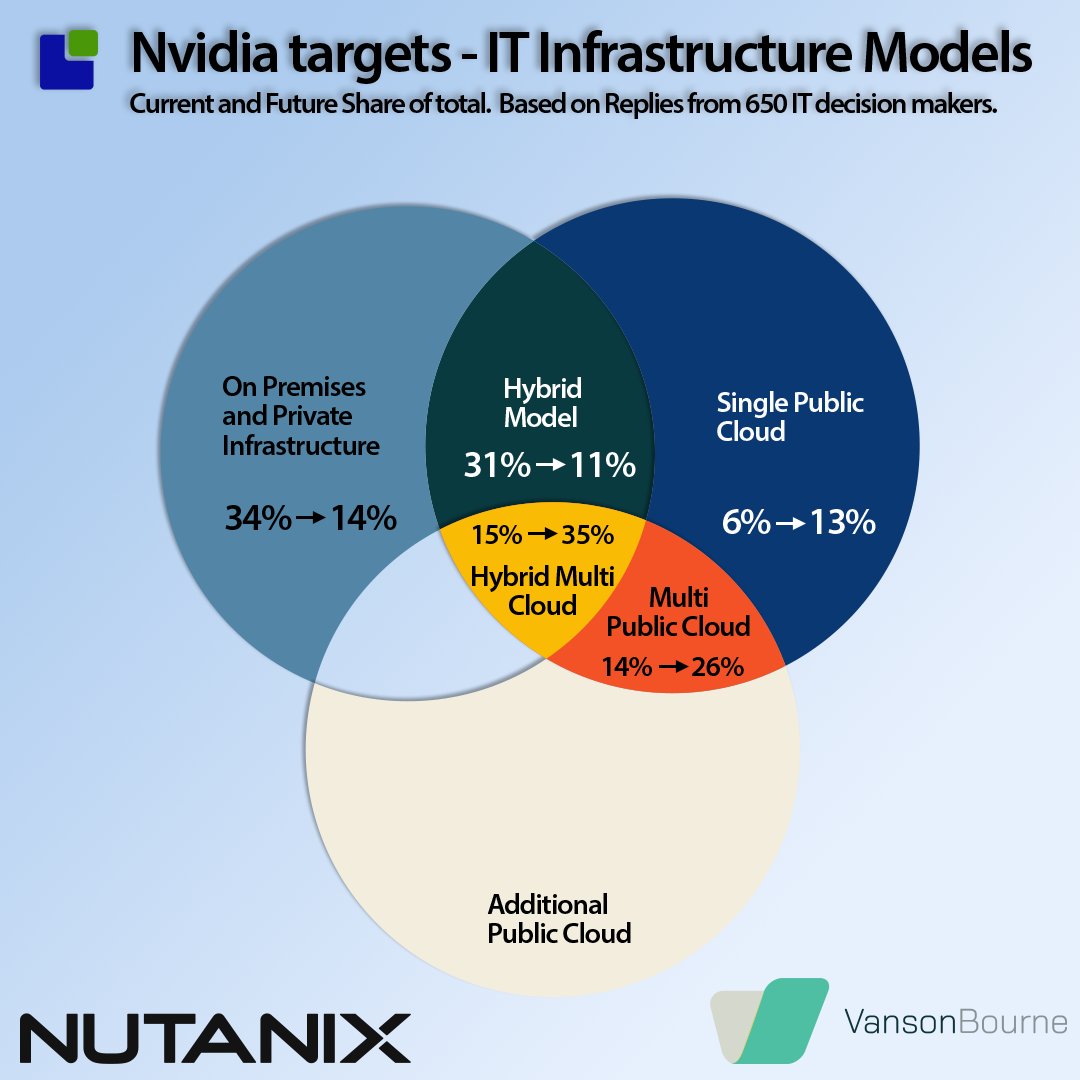
As an IT infrastructure novice, I needed to upgrade my knowledge. This is what I found. https://t.co/v7j76TUm6q
The semiconductor industry simmers and bubbles. The demand is shifting rapidly to data centre CapEx while the supply chain is trying to catch up. From one semiconductor cycle to many. From a complex supply chain to an even more complex supply chain.
I will present my analysis at the online MicroFab Summit 2024 conference (https://t.co/RYy9O1cAyD). Register today to attend on December 11-12! To receive a discount code for your registration, please email Jessica Ingram at [email protected].
@microtechv@MikePinelis #MicrofabSummit
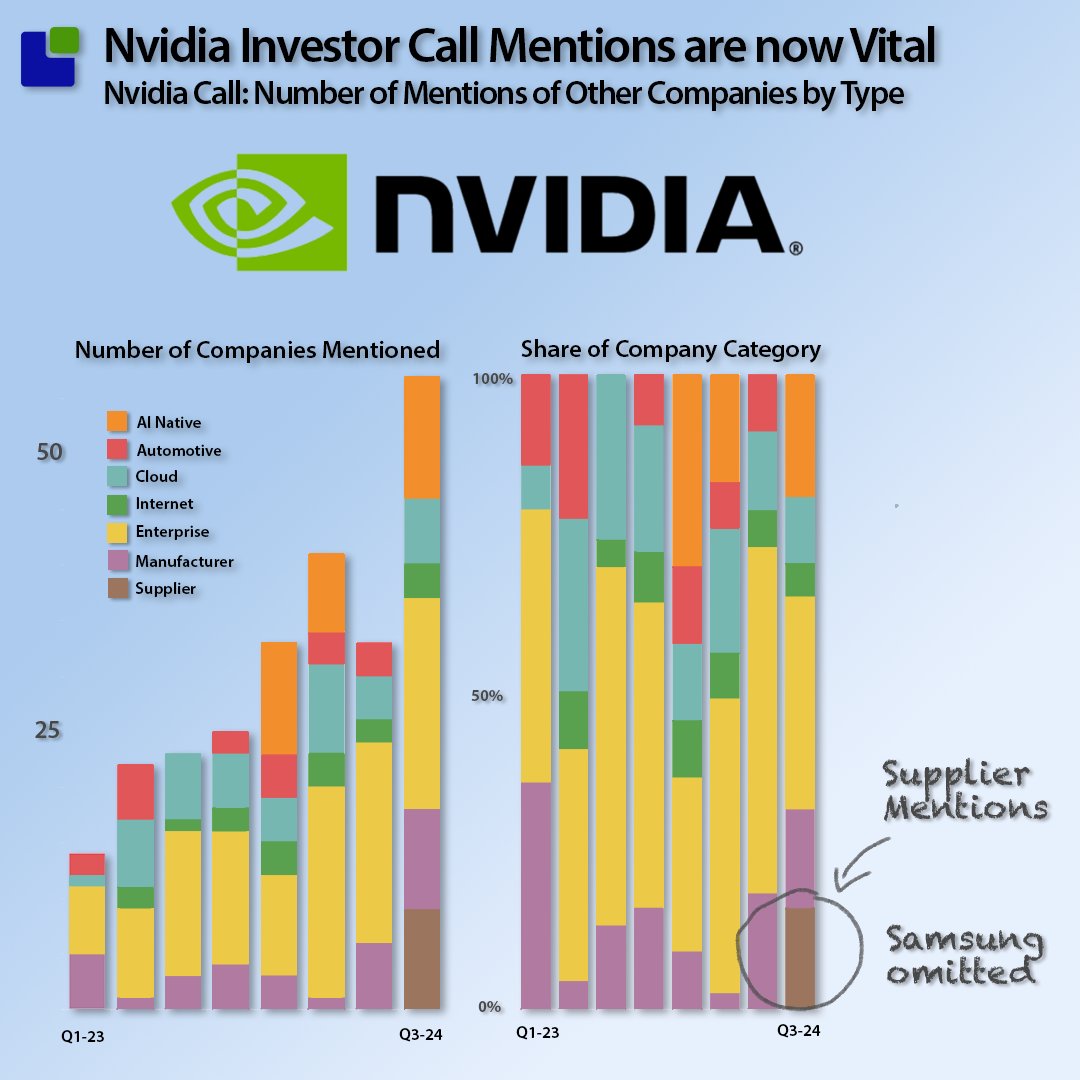
If you think it is irrelevant to be mentioned on an investor call, you should talk to Samsung. They were not mentioned in the Nvidia Investor Call, while their two main competitors, SK Hynix and Micron, were.
Jensen was immediately confronted with the omission: "Nvidia is working as fast it can to certify Samsung’s AI memory chips", CEO Jensen Huang tells Bloomberg TV. This did not make things less embarrassing for Samsung.
From being a rarity in the Semiconductor industry, Nvidia has increased the number of company name drops from 14 before AI popped to 57 mentions in the latest call.
For the first time, Jensen mentions suppliers. Given the insatiable demand for Blackwell, it is reasonable that they are on his mind.
If you think mentions and omissions are essential, check whether your company or competitor was mentioned.
We've got you covered:
https://t.co/GlE4kuZJpZ
There is no company name-dropping in most investor calls in the Semiconductor industry except for competitor names. Information about suppliers and customers can be sensitive, and in general, it is not shared.
However, a graphics gaming company changed that right before becoming an AI GPU company. On the investor call just before the lid went off the AI kettle, Nvidia mentioned 14 companies in their investor call. Last week, that number had grown to 57 mentions! The call is turning into the AI Academy Awards.
From not wanting to be mentioned, companies likely need to be mentioned on the Nvidia call. That means you are at least a billion-dollar friend to Jensen and worth noticing.
I take a look at the data and share it with you in this free blog post:
https://t.co/GlE4kuZJpZ
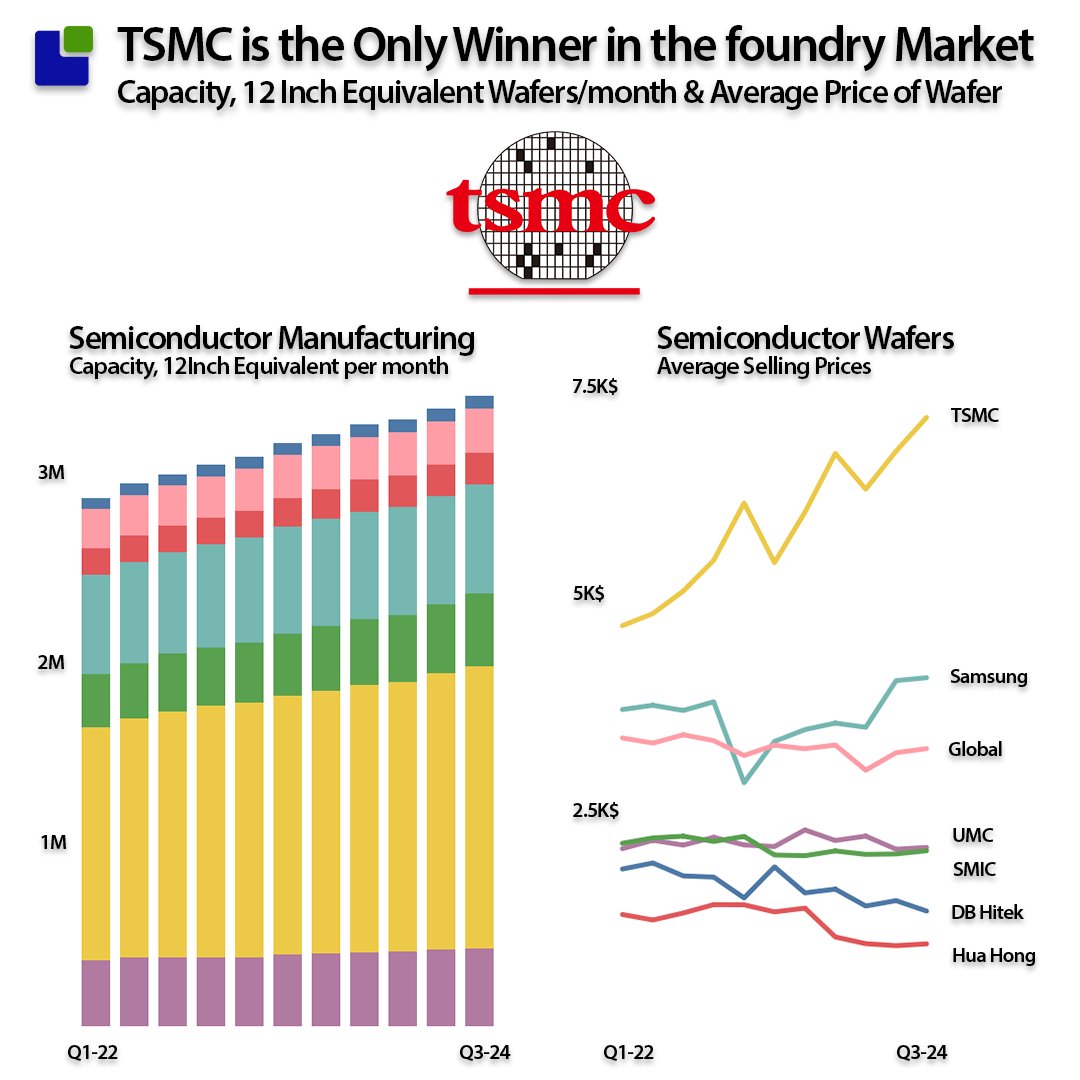
Despite responding to the market downturn by cutting CapEx investments, semiconductor foundries had to fight over fewer orders while more capacity came online.
The capacity is growing at 8%, similar to the current average global semiconductor market growth.
The problem is the timing. When you invest at the peak, you get it in the trough.
With declining utilisation rates, some of the less fortunate foundries had to fight over the scraps and have seen declining wafer ASP's.
TSMC's leadership in technology meant they could afford to compete and outcompete everybody in the mature technologies but decided not to.
Despite 3 quarters of improving utilisation rates, TSMC is still only at 72% utilisation rate. This typically means depressed profitability, but the Taiwanese powerhouse is capturing 90% of all the operating profits in the foundry market.
TSMC could have crushed the competition in this down-cycle but decided not to. Only TSMC knows why, but the company has more depth than your average corporation.
Read more about the foundry industry here:
https://t.co/9CmrURg1GV
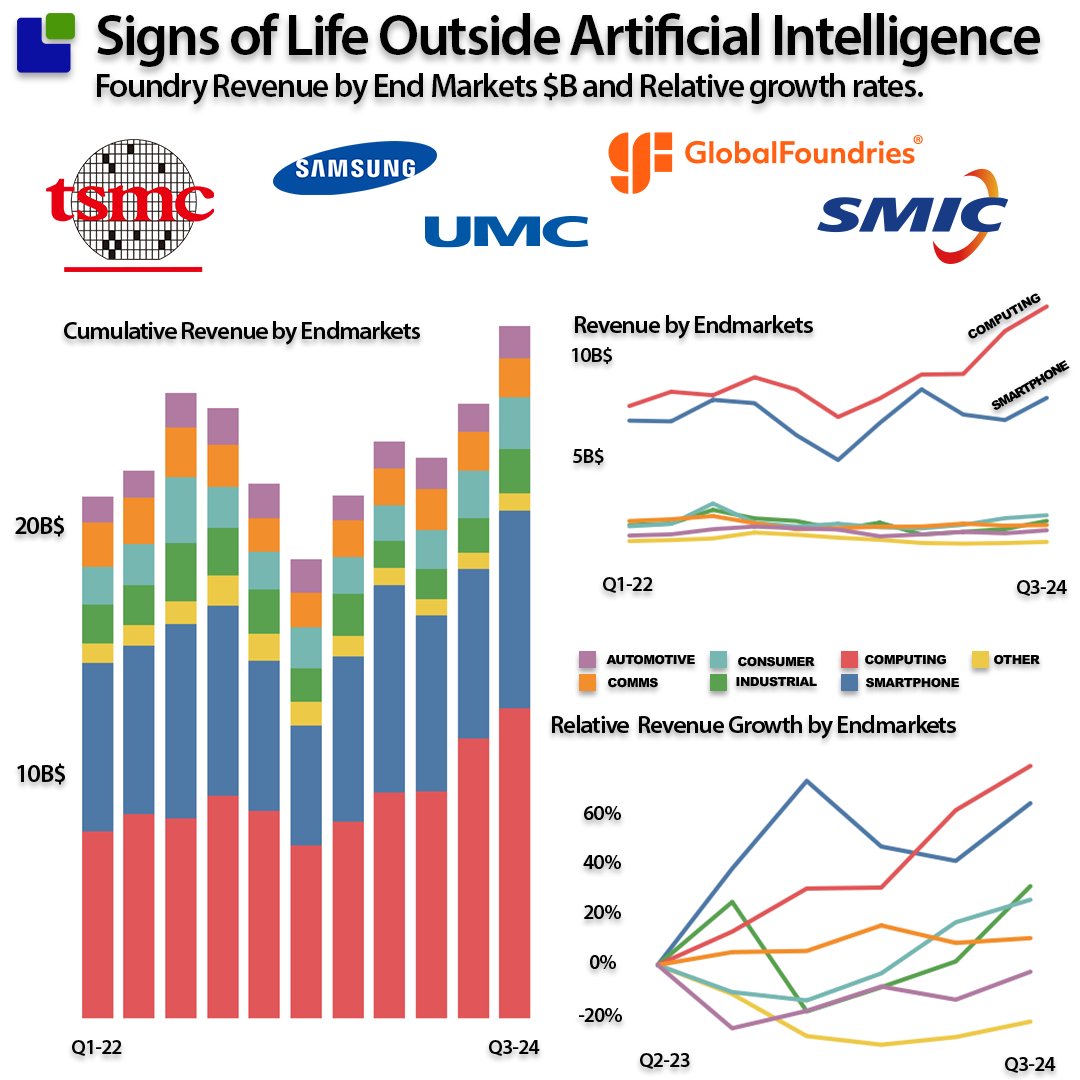
The supply chain is whispering while accelerated computing continues dominating the Semiconductor industry after Nvidia's release.
The Hybrid Semiconductor companies dependent on the Industrial, Automotive and Communications markets guided Q4 revenue down collectively. But now recovery sprouts are beginning to show in the shadow of TSMC's computing business. The foundry business is ahead of the Semiconductor business in the cycle, and the people tuning the machines know what is coming.
Read more about insights from the business of the foundries in my blog:
https://t.co/wYMwaMzkNS
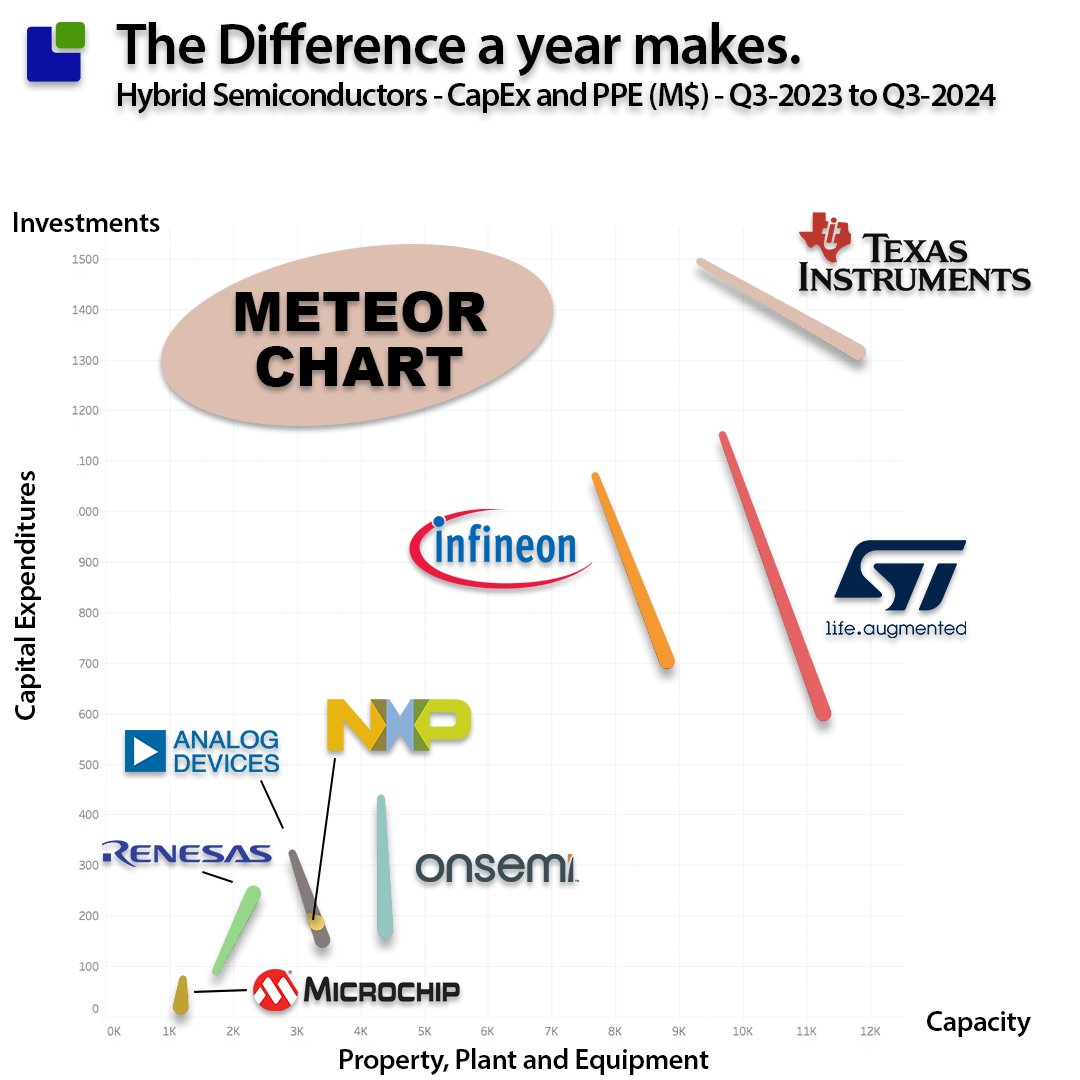
To get a quick overview of Hybrid Semiconductors' current and future fab capacity, I use the Meteor Chart (which I call the Fireworks chart in better times). It shows the distance travelled in a year regarding the financial value of the capacity (Property, plant, and equipment) and the investment in future capacity (CapEx).
Two leading comets have significantly reduced their CapEx over the last year. While Texas Instruments is also spending less, the Lone Star company spent more than its two large competitors combined in Q3-24.
The Meteor Chart is a snapshot in time and cannot stand alone, but when used effectively, it can tell a story. https://t.co/IjdHbmkicr
Like a slow rollercoaster, the Semiconductor industry moves in four-year cycles. The cycle length is more or less constant, but the timing of cycles is different in each industry subsector.
While Nvidia will report on its own upcycle tomorrow, the Hybrid Semiconductor Companies will remain stuck on the downslope for at least another quarter.
The cycles are no surprise, but navigating the downcycle is risky, and two CEOs did not make it. The two companies that changed leadership pursued two very different strategies.
While Microchip took the frugal route of expense control, pay cuts and reduction in CapEx, Wolfspeed maintained its wild spending spree on fab expansions despite not being profitable for years. Where the two companies strayed away from the pack was in operating profits. While Microchip stayed profitable, it got too close to the line for CEO survival.
Read more about the status of Hybrid Semiconductor Companies here: https://t.co/kFEI6jhJ2o