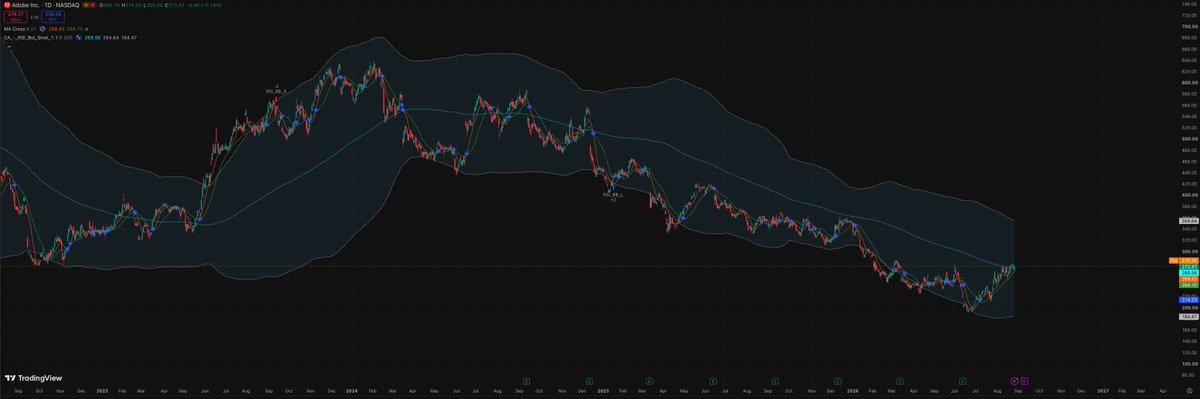
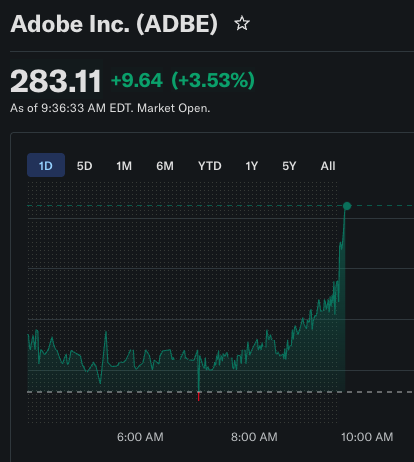
$ADBE closed at 290 yesterday, i got it right before the open at 275 ish.
i received some dm to ask if i was still holding. guys, of course i am holding on it, read the post, the thesis is mid term at least, and i am looking for a +100% at least on this one so i won't start thinking about exiting the position before we get to 500/share
going long $ADBE mid term horizon.
not a trade -> a thesis.
the stock sits around 276. that is roughly 34% below its 200 WMA. for a business like this it almost never happens.
so i looked at what broke.
last quarter revenue was 6.62b, up 12.7%. eps beat. net margin near 30%. return on equity 65%. they raised full year guidance.
nothing in the numbers is broken.
what broke is the story. the market decided ai kills creative software. canva, figma, image models, pick your reason. morgan stanley cut it to underweight this month.
and the funds left. last quarter more of them cut than added. fisher dumped almost the whole position. norges trimmed. the people who wanted out are already out.
that is the setup i like. good numbers, bad narrative, empty positioning.
adobe is a cash machine. massive free cash flow. they buy back stock every quarter. share count keeps going down. you get paid to wait.
at low teens forward earnings you are not paying for growth. you are paying for the company to still exist in five years. i think it will.
the moat is not the ui. anyone can ship a nice ui now. the moat is the file formats, the plugins, the team workflows, the twenty year old muscle memory of every creative pro on earth. that stuff moves slow.
management is changing too. new cfo. i want to see what they do with pricing.
the risk is simple and i take it seriously. if firefly does not land and they keep giving tools away for free, cheap gets cheaper. that is the bear case and it is not stupid.
earnings on september 10. options price around a 10% move.
i am sized for that. not all in.
IBKR and TR are not meant to be competitors.
Show me how I can put in production a fully automated high frequency trading strategy on TR please.
You don't have an API. You don't offer any algorithm to manage orders (VWAP, TWAP and others). You don't offer market on open/close order. And the list goes on.
You should compare TR with @Revolut maybe. But if someone from IBKR is moving to TR, it does not mean that you are better than IB, it just means that this user should not have been on IB in the first place.
So, stop "lebron james-ing" yourself and get back to work
alibaba $BABA just banned its own staff from using claude code.
from july 10, BABA employees can't touch anthropic's coding tool at work, over what alibaba calls embedded backdoor risks. they're told to use qoder, alibaba's own tool instead.
the backstory: last month anthropic accused alibaba's qwen team of copying claude, calling it the biggest attack of its kind. now alibaba swings back. the US and china are unplugging their AI from each other.
the ban itself is symbolic, not financial, BABA barely moved. but it feeds the real story: china goes all in on its own stack.
who wins that shift: qwen (owned by alibaba), baidu ($BIDU) with ernie, tencent ($TCEHY) with hunyuan, plus the private labs deepseek
people need to look at the chines market more in depth..
@KryptoKokotek@Avalanche I wasted too much of my time in crypto, I now prefer to stick to tradfi only. But indeed, very good news for avax, i hope they can capitalize on that for the next cycle
Not saying it won't happen, but "CEO is a Harvard educated lawyer" does not mean much tbh.
Also, Carlos could hire and "Harvard educated lawyer".
Finally, assuming someone is going to commit fraud to prove your point is IMO not the best way to convince your audience.
but indeed, let see what happens!
$GENB is the closest thing to buying early Moderna again, same lab, same people, same machine.
it was built by flagship pioneering, the exact venture firm that created moderna.
noubar afeyan, the man who co founded and chairs moderna, is also the chairman and a big backer here.
stéphane bancel, moderna's founding ceo, sits on the board too.
so does frances arnold, who won a nobel prize for engineering proteins, which is literally what this company does.
they use generative AI to design brand new drugs from scratch, turning discovery from a game of chance into engineering.
NVDA already put money in, its venture arm backed the round alongside amgen.
amgen went further and signed a multi target partnership to build drugs on the platform.
the money behind it is serious, abu dhabi's sovereign fund, fidelity and t rowe all in.
it IPO'd in february, raised 400m, and holds years of cash to run.
17 programs in the pipeline, the first ones already moving into human trials.
one honest flag, it is pre revenue and clinical stage, so the trials have to work or the story breaks, this is high risk.
but if the platform delivers, you are early on the next moderna, backed by NVDA and the people who built the first one.