@KatKanada_TM Slow bleed til 2032 with moments of “we’ve bottomed” only to realize detached homes are still way over valued to affordability of household NET income
30% minimum to go!!!
Tying up $8.5B in cash at as it melts at 7% min per year is overkill. I understand the sentiment and security of 5 years cash. But then that risk is eliminated 5x, therefore the div should be reduced to much lower if they had 5 years cash. Instead that extra amount over 1-2years could be better utilized on debt, stock buybacks, BTC. They always have the BTC to cover the 1 year minimum, especially at higher prices. We are in agreement 99% of the time but not the 5 years. Respect!
Yes, and/or utilize the BTC in treasury to create enough annual revenue to cover the dividend payments. The BTC number go up narrative is not enough, especially in the down market and now any purchases to take advantage of cheap BTC or replenish cash reserve are dilutive to common.
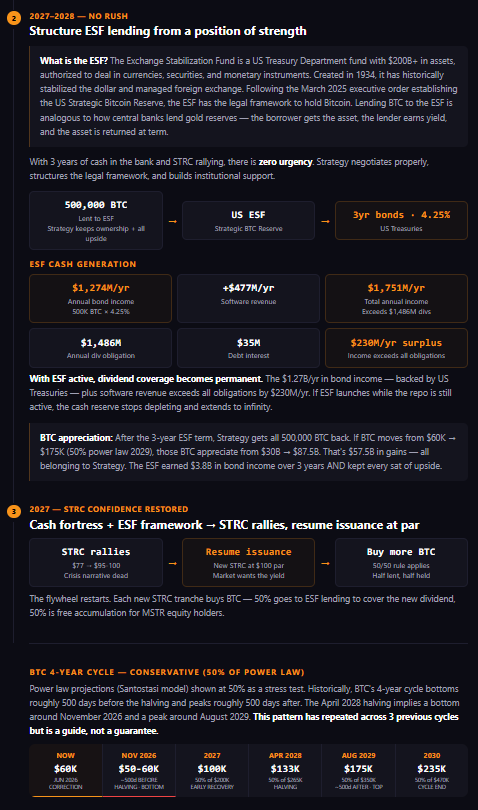
Has Strategy considered utilizing the Exchange Stabilization Fund with the US Gov. to free up enough capital over 3-4 years and use a chunk of the BTC to generate a safe yield via US Treasuries over 3-4 years at 4.25% yield, enough to offset the cost of the dividends+? The revenue is the safest play and the sell would be STRC shareholders are getting 11.5% yield back by BTC and US Bonds. Sitting on all that BTC and not utilizing that capital seems like a missed opportunity to generate needed revenue, all while still getting the BTC appreciation. In the short term to kill the fear, a 3 year runway Repo to fund the divs without technically selling BTC, while getting a cap loss offset on paper would probably calm the nerves and destroy the short interest.
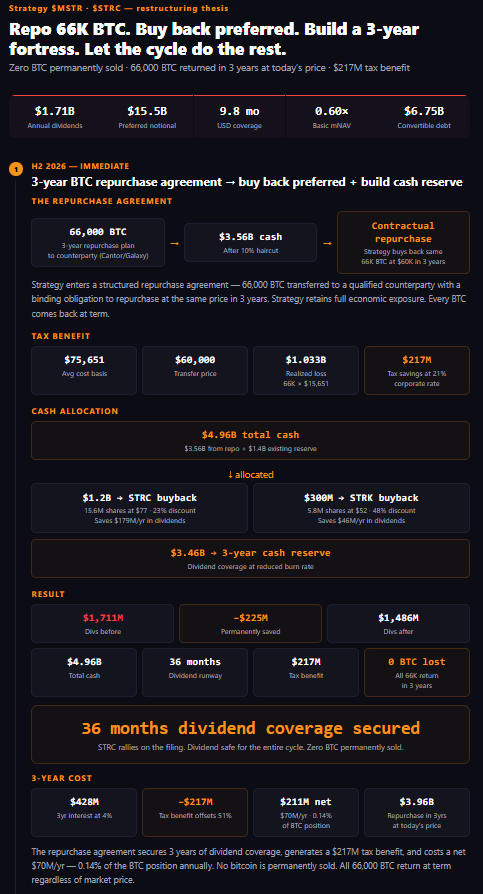
They have more levers. Repurchase agreements, collateralized loans, refi, do nothing for now. The most advantageous is a Repo over 3 years and secure 3 years runway of dividends as well as buy back some Prefs at huge discounts.. plus get the tax breaks and let BTC do what it does over the next 3 years.. rinse and repeat.
I 100% agree, time and USD reserve is priority. Lots of talking about selling BTC or MSTR common in dilution to raise cash for STRC divs. They have better options that are especially advantageous now below cost basis. They could go to the capital markets (Cantor/Coinbase) and do a (Repo) Repurchase agreement at 4% for 66000 BTC raising $3.6b to give a total cash of $5b in reserves, buy back a chunk of Prefs at huge discount and have a 3 years dividend runway. Cost is $428m in interest but the tax benefit is $217m from base cost of 75000 per btc. Net cost is reduced to $211m net to buy 3 years of dividend runway, buy back prefs, reduce div costs and secure the STRC back as well as let BTC do what BTC does over 3 years. Buying time is what matters right now. Then start working on future revenue streams that fully cover the dividend obligations such as the Exchange Stabilization Fund and using the treasury BTC as collateral for US Treasuries at 4.25% to fully cover future debt obligations. This is a real flywheel. In essence the STRC 11.5% is a dividend funded and secured by US Government Bonds. Like it or not, its the most secure form of revenue there is. This is a rinse and repeat as BTC continues to mature. Purists will hate it. See the illustration phases.
Everyone talking about selling btc or MSTR common in dilution to raise cash for STRC divs. They have other options that are especially advantageous now below cost basis . They could do a 25% LTV collateralized loan for 1.8b cash or even better go to the capital markets (cantor or Coinbase) and do a Repurchase agreement at 4% for 66000 btc raising $3.6b to give a total cash of $5b in div reserves or 4 years runway. Cost is $285m in interest but the tax benefit is $217m from base cost of 75000 per btc. Net cost is $68m to buy 4 years of dividend runway and secure the STRC back as well as let btc do what btc does over 4 years. Time is what matters right now.
@BitPaine They desperately need to utilize the BTC treasury to generate revenue to cover the divs if this is going to survive. How? Lend 720k BTC to the US Exchange Stabilization Fund. Buy 3 year US Bonds at 4% to fully cover the divs. Sell no BTC, no dilution, keep gains. The math works.
@AdamBLiv They need revenue. Revenue to pay for the divs,the debt, and the new BTC. The financial engineering is not going over well and walking a highwire. They can use the BTC to generate rev via the USA Exchange Stabilization Fund. 3yr bonds at 4.25% yield would cover everything.
@BitPaine @Z06Z07 @saylor@phongle Or.. they buy enough US treasuries over 5 years at 4% via the Exchange Stabilization Fund (about 450000 of their BTC) to fully cover the Dividend at 100%.. STRC holders get us gov bond basically for 11.5%. Strategy never loses the BTC as it matures over 5 years.
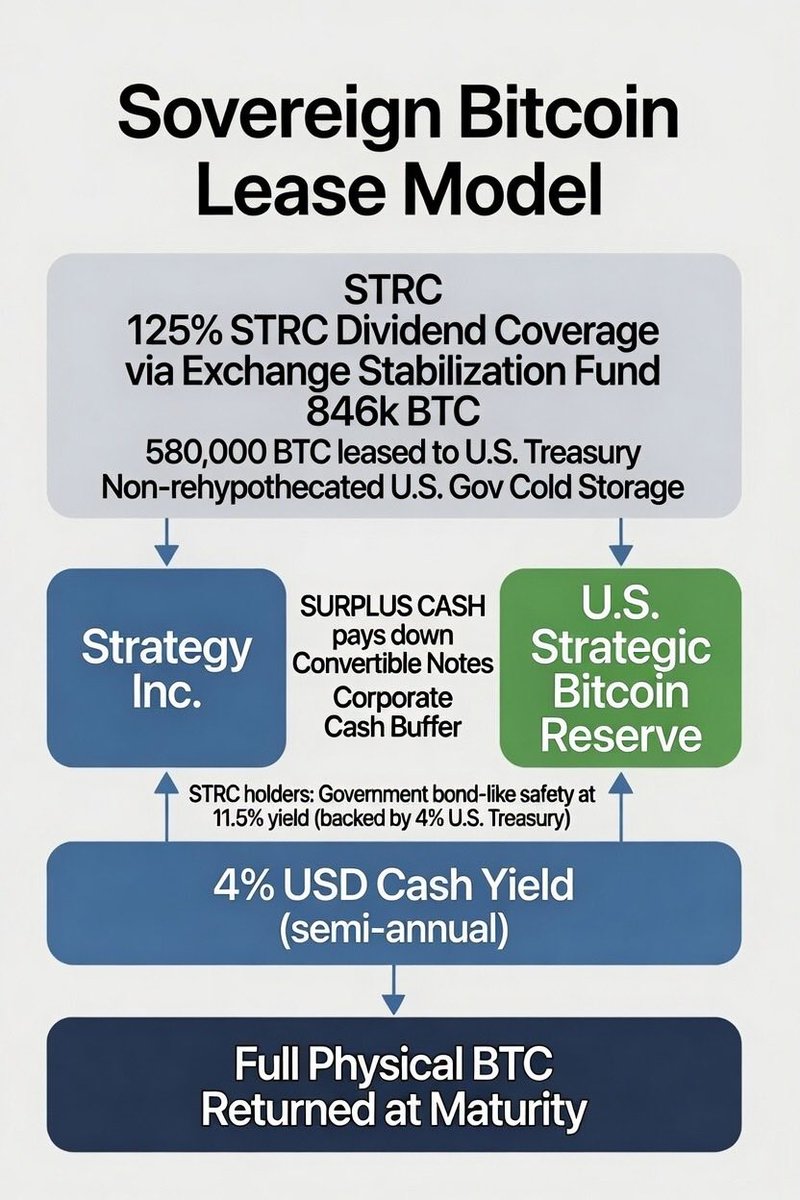
@saylor Chap2.. 30B of US treasuries 5y at 4% with 50% of the BTC as collateral. 130% of STRC div covered and backed by US bonds. $100 peg easy as there’s no more risk. Perpetual machine begins. 30% pays off CBs. Never sell the BTC. Goose makes eggs. Repeat!
@AdamBLiv 2/5 Simple flow: Strategy sends BTC to secure U.S. cold storage (non-rehypothecated). Gets 4% USD yield semi-annually. Same sats returned in Year 5.
Delivers 107–124% coverage of ~$1.2B STRC dividend + surplus buffer.