Prometheus Institutional🔥
Prometheus is built on deep research into how the economy & markets work. We translate that into systematic programs across global markets. We offer an ever-evolving, forward-looking, signal-based view of the global macroeconomic landscape.
Link ⬇️
Yes, everyone is concerned about AI capex.
However, an underappreciated factor in the macro dynamic is that much of the current profit growth (about 50%) is fueled by the dis-saving of households.
Our next note @prometheusmacro will be on this subject
Hikes cause recessions when they drain private income. Since 1967, outside of COVID, a recession has never begun within a year of net interest drag falling.
Today, it is falling, so the Fed's hikes so far aren't doing the work they used to.
Our measure of industrial equipment production continues to accelerate within an expansion, and with industrial earnings expectations holding near their highs, the backdrop for industrial profits remains supportive
Hiking cycles are never fully priced in. In 2022, the curve priced cuts while the Fed delivered 533bps of hikes.
The Fed's inertia means policy tends to move further than markets expect at any given time.
High Nominal Growth -> Demand Destruction
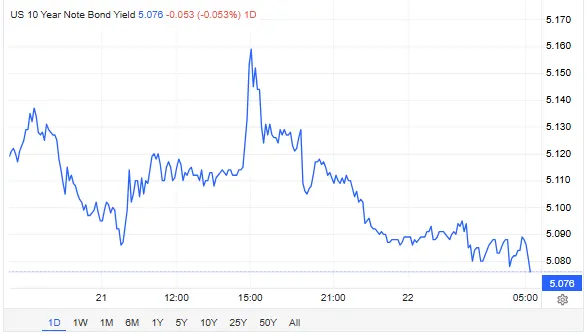
Financial markets looked right through the drags on the economy from high oil prices for most of the year. As oil gets back to Iran war highs, we are seeing an important shift in the market action.
https://t.co/9Shk6IfGGv
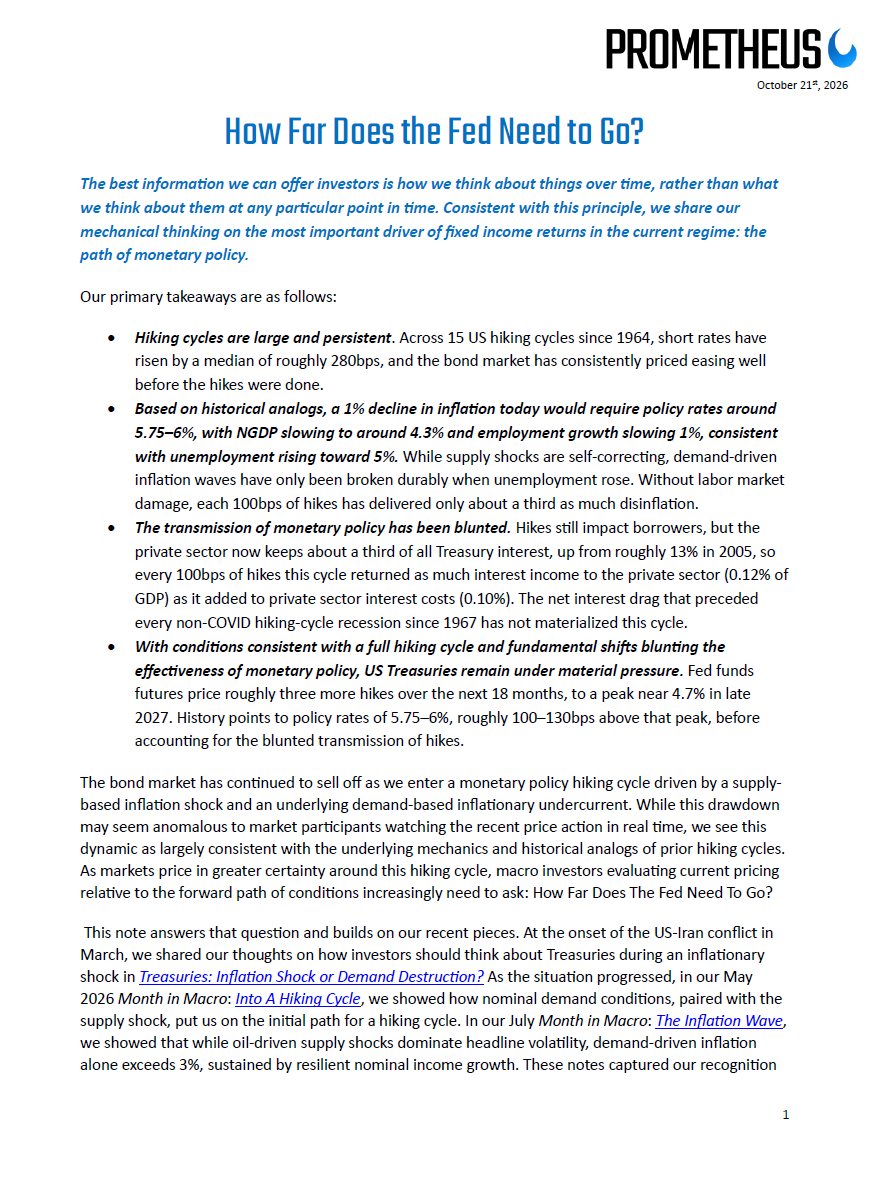
How Far Does The Fed Need To Go?
Over 30 pages of fundamental & systematic research, we assess how much the Fed needs to hike rates to meet its policy objectives.
We find that risks remain skewed toward the Fed needing to raise rates materially more than priced
Free. Link ⬇️
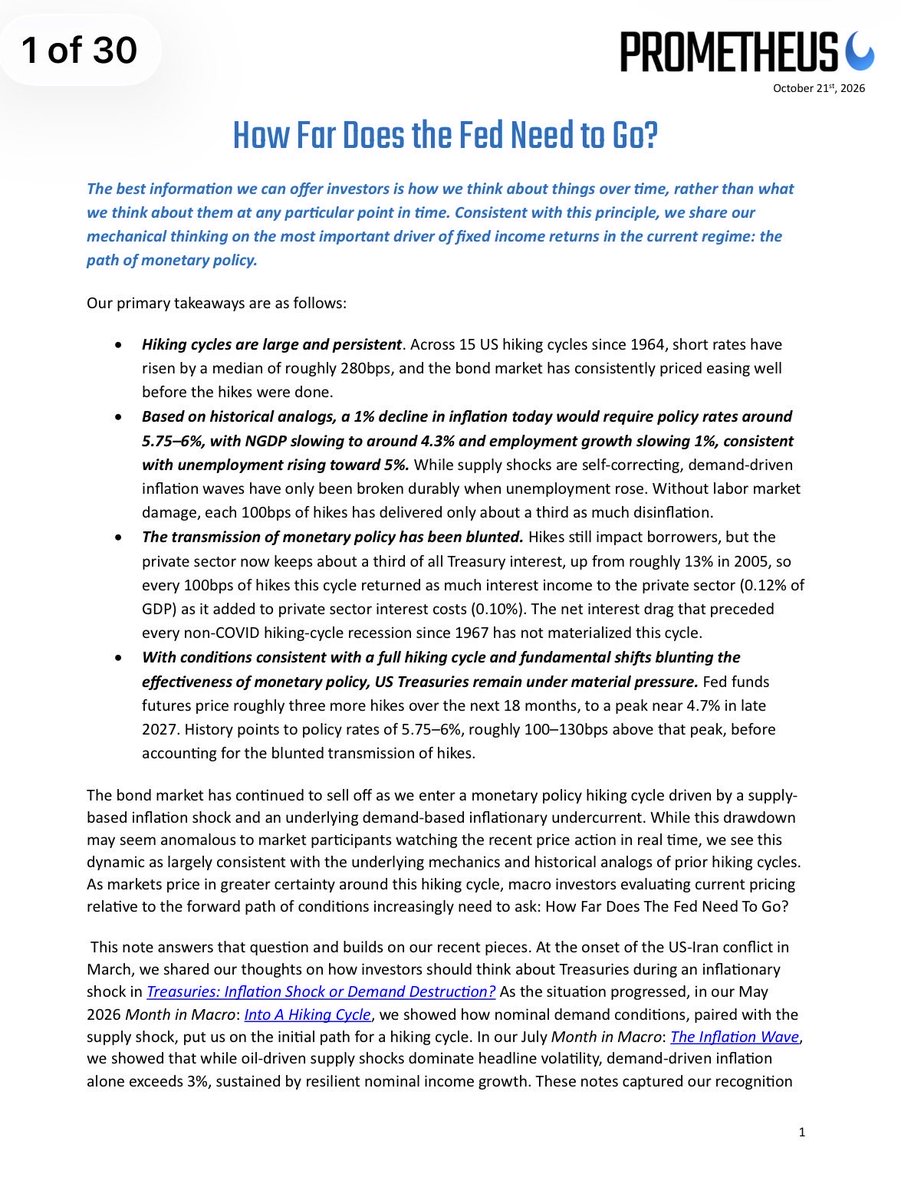
How Far Does The Fed Need To Go?
Over 30 pages of fundamental & systematic research, we assess how much the Fed needs to hike rates to meet its policy objectives.
We find that risks remain skewed toward the Fed needing to raise rates materially more than priced
Free. Link ⬇️
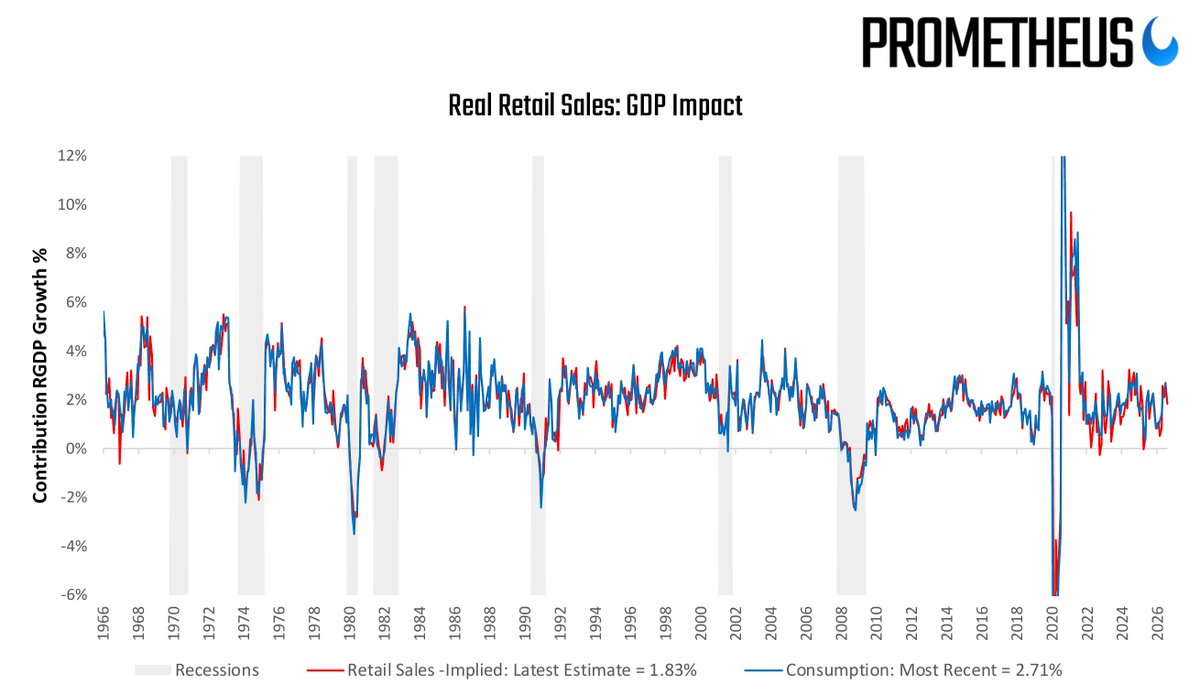
Our retail sales-implied estimate of real consumption points to a slowing contribution to GDP growth, as gasoline-driven nominal gains fail to translate into real spending.