$NUAI – FOR EVERYONE WHO WANTS TO UNDERSTAND THE NUAI INVESTMENT CASE AND WHY I’M SO BULLISH. 🔥
I genuinely believe the next 60 days could completely transform NUAI, and I think the market is massively underestimating what’s coming.
Here’s what I’m expecting before mid-January:
First, a definitive 207MW lease agreement, potentially with Anthropic, on terms comparable to RIOT’s recent deal. If the agreement isn’t ready immediately, a binding LOI could be an intermediate step.
Second, approval of the air permits for the additional 550MW.
And finally, another agreement covering Phase 2, potentially bringing the total to 757MW under long-term contracts.
Remember, NUAI has already disclosed a non-binding LOI covering BOTH phases with the SAME prospective customer.
Now look at the valuation.
At my recent reference market cap of approximately $437M, NUAI reported $187M in total cash, including restricted cash, only $20M in outstanding debt and no convertible notes.
It already has 207MW of firm power secured through a 20-year agreement with Vistra.
And RIOT’s recent $28 BILLION AI infrastructure agreement demonstrates just how valuable long-term contracted capacity can become.
I’ve said this repeatedly: being late to the AI infrastructure race could turn out to be NUAI’s biggest advantage. No billions in legacy mining debt, no massive GPU investment requirements, and the opportunity to structure deals around today’s market conditions.
My personal bullish price expectations:
207MW signed: $12–15.
757MW contracted with attractive economics and financing: $20–25+.
And yes, I believe this could happen before January 15, 2027. That’s my prediction, not a guarantee.
NOW HERE’S WHAT I REALLY ENCOURAGE EVERYONE TO DO.
Don’t just follow the share price or other people’s opinions. Spend an hour understanding the actual business.
1. Read RIOT’s $28B agreement. Understand the economics and capital-efficient structure.
https://t.co/OovTHjUHsw
2. Read NUAI’s 20-year Vistra agreement. Understand the importance of securing 207MW of firm power.
https://t.co/2o0NBg0ejL
3. Read NUAI’s Q3 earnings release. Pay attention to the LOI covering both phases, the balance sheet and the progress toward a definitive lease.
https://t.co/56onS8xtzF
4. Most importantly, LISTEN to NUAI’s November 12 earnings call. Hear management explain the negotiations, financing and development plans.
https://t.co/B0xGePfJid
I believe once you understand all four, you’ll see why I’m so bullish.
The market is focused on 207MW. I’m looking at the potential for 757MW.
Read the agreements. Listen to management. Connect the dots.
Then make up your own mind.
I’m extremely bullish, and I’m holding. 🔥
$NUAI President & CFO Ted Warner took the stage at @cantorfitzgerld Convergence to discuss the evolving AI infrastructure market and how New Era’s competitive power position provides a foundation for building a scalable platform.
Securing power is only part of the equation. How soon that power can be delivered, how projects are financed, and the development models used to bring capacity online are becoming increasingly important considerations for investors.
With 207 MW of firm, contracted power expected to become available in Q3 2027, New Era sees a compelling opportunity to pair its near-term power position with a modular, phased development strategy designed to accelerate deployment, reduce upfront capital requirements, and provide greater flexibility in how capacity is delivered. This is all supported by a world class team that’s experienced in building hyperscaler data center infrastructure.
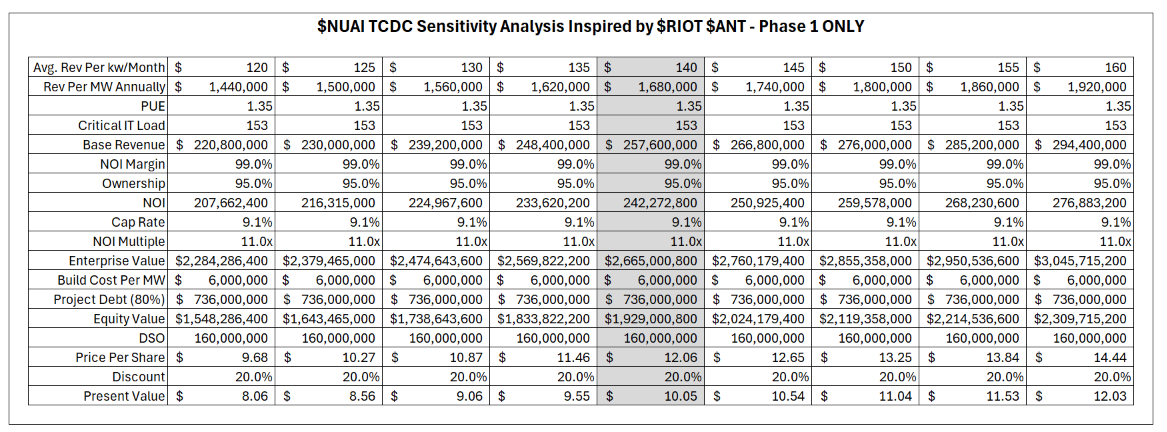
$NUAI Phase 1 Signed is Worth $10 Today
Inspired by my friend @SmallCapSnipa publishing the Northland sell side analysis, I found it appropriate to keep it simple and stick to the same format.
Warning: this analysis is for Phase 1 only, and does not include Phase 2 or Phase 3 at TCDC that will at a minimum power 1.2 GW or 6x Phase 1.
Now let's talk through some assumptions before you read the output I produced attached.
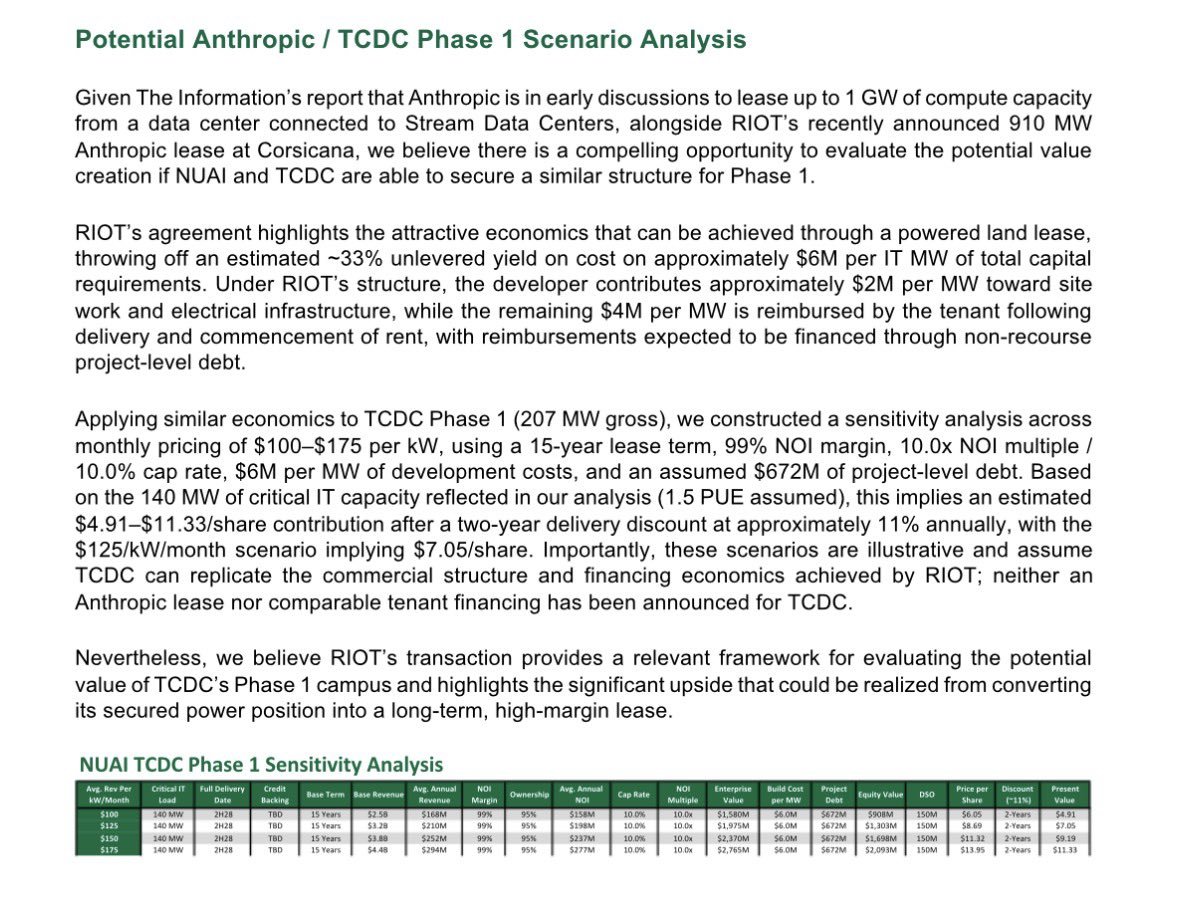
1) Rent - $riot executed for $130/kw/Month with $ant but my base case is $140 due to $NUAI being responsible for development and construction of the modular data centers versus just the powered pads and a later LOI date in September as power became harder to find in 2027
2) PUE - Northland is far too conservative as the $riot deal is 1.1. The initial LOI asked for 756 MW IT but landed on 910 MW IT because $ant opted for a simpler modular build and will be able to adjust power down during peak temperatures but will pay for the max capacity. My base case is 1.35 for now.
3) NOI / Ownership - 99% NNN and 95% for Vistra 5% share.
4) Multiple - Northland uses at 10 cap or 10x multiple but I find that cash return too high and believe 11x is more appropriate as a 9.1% cap rate is almost 4% higher than the 5.35% average of the 10 year and 20 year treasury. That's a very wide credit spread and the multiple should likely be 11.5x or 12.0x.
5) Build Cost - Same $6m assumption with 80% debt assumed.
6) DS0 - Used fully diluted shares of 160m from earnings to be conservative
7) Discount - Northland uses 11% for 2 years for a 2028 delivery but that's far too conservative as I believe delivery will be Q4 2027 given the modular build. That said, I upped the discount to 20% for one year for time value of money and execution risk.
Ted Warner just telegraphed Phase 1 delivery and most likely Phase 2 at the Cantor panel to mitigate regulatory risk upon approval of the company's air permit by starting construction as soon as possible.
I've never been more bullish on a setup because management is keeping it super simple which will result in accelerated institutional adoption as the deal structure can be digested in 5 minutes. See $riot performance following their deal versus peers.
Load up. Final call.
NFA DYOR
Many investors will sell the absolute bottom of this drawdown/correction.
Missing the life changing gains that will come over the next 6-12 month, entirely.
I’m just gonna go ahead and say it.
If you sell here you’re retarded.
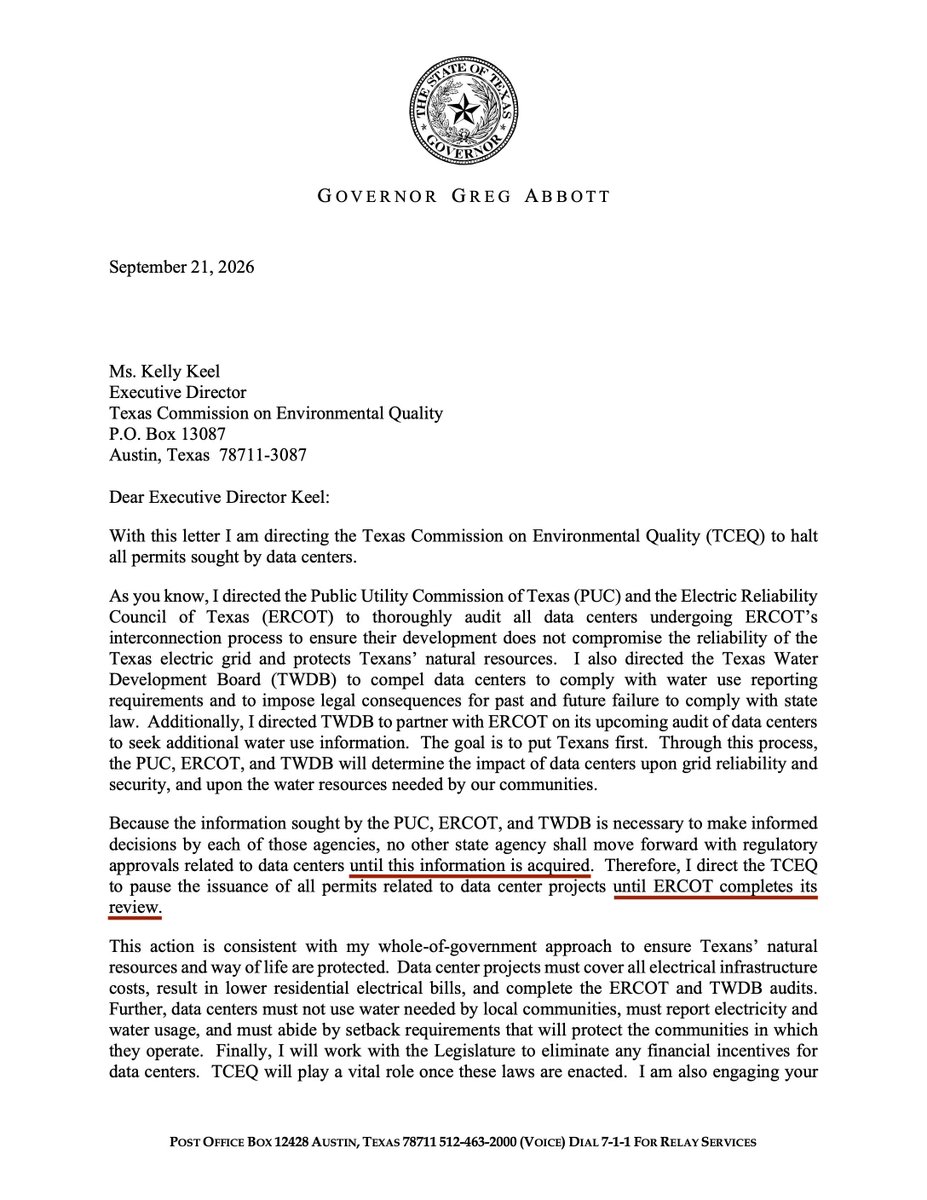
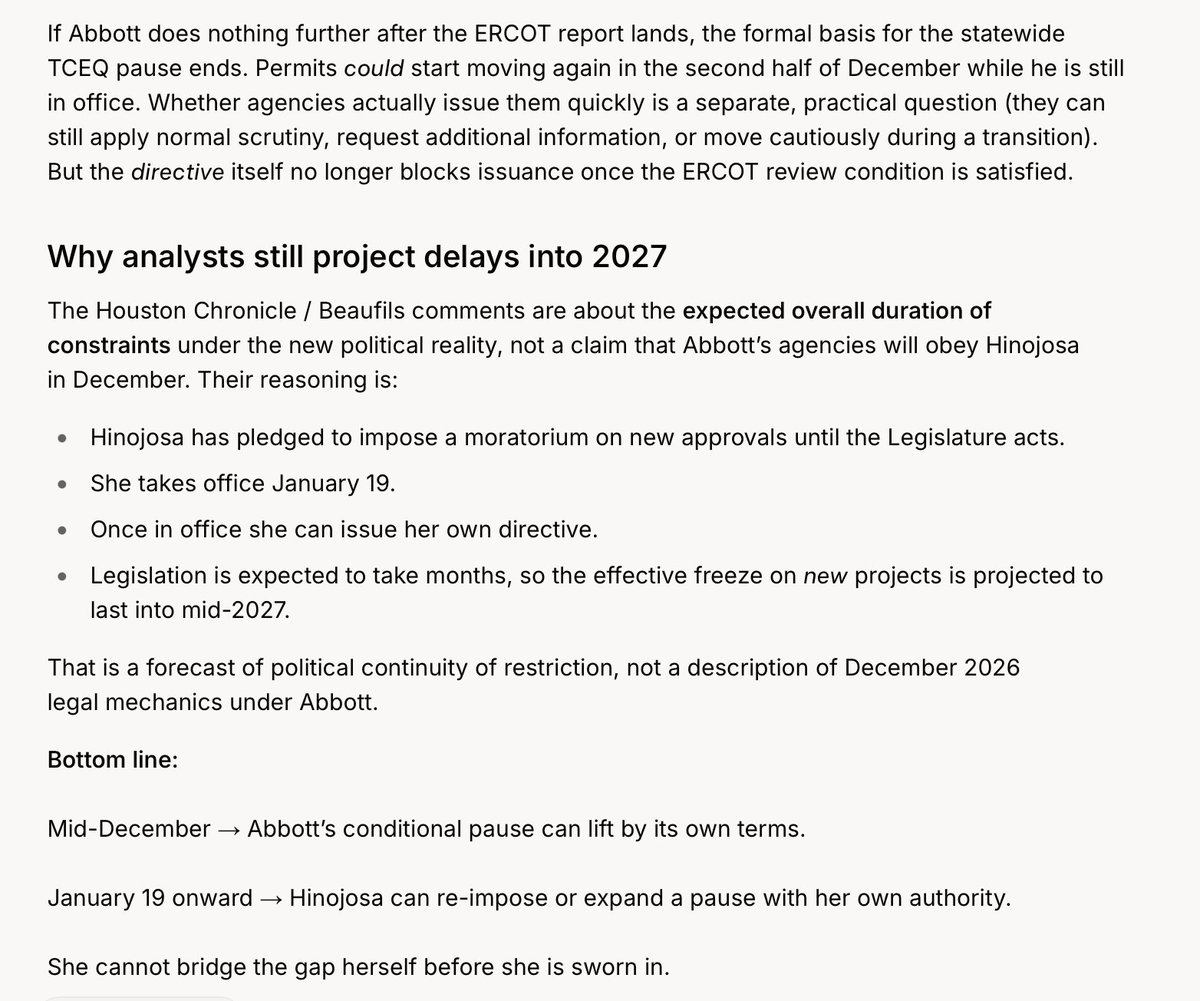
1/ Gov. Abbott left a kill-switch in the Texas data center permit freeze. He directed TCEQ to pause permits “until ERCOT completes its review”—the basis lapses December 10, when conditions are met. Furthermore Hinojosa's industry-wide freeze is legally vulnerable. Here's why...👇
$IREN this too shall pass. Just to recap the last 24 hrs:
1) a coordinated FUD campaign
2) our Canadian employees being taken out in a bus accident (praying for them 🙏), and
3) the Nasdaq doing -500 bps, triggering algo selling below the 200 SMA.
ALL leading up to earnings tonight.
Oh and we’re now trading below cash on hand with no major debt maturities for years; 1/2 of current fair value (net debt) by my math.
… okay 😂
Still buying. 70% larger position than April 2025 now.
1/ Everyone take a deep breath. Texas data centers aren't going anywhere. The Texas governor has very limited authority to stop them. Calls for a pause or moratorium must be approved by TCEQ—the permitting authority of Abbott appointees. Here's how Texas permitting really works👇
@euwyn Do we even have 1 MW of data center in space right now? Current prototypes (Google Suncatcher, Starcloud, etc.) are still in the ~1 kW range. Let’s get the first real one online before we start talking hundreds of MW or GW.